
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should Earnings Expectations Require Action From Renasant Stock Investors?
- Renasant is set to report September quarter results on October 27, with the market focused on the company’s expected higher earnings and revenue versus the prior year.
- The more recent downward revision to the $0.94 EPS consensus has turned attention to how current business conditions line up against those earlier expectations.
- This article explores how Renasant's upcoming earnings release and shifting EPS expectations could influence the broader investment narrative.
Scan how Renasant's setup compares to other regionals by reviewing a curated list of solid balance sheet and fundamentals (25 results) that could be better positioned for the next earnings surprise season.
Renasant Investment Narrative Recap
To own Renasant, you need to be comfortable with a regional bank that leans on steady mid single digit loan and deposit growth, disciplined costs, and fee income from areas like wealth and SBA lending. The big near term swing factor is whether core profitability holds up as funding costs and commercial real estate payoffs interact with that plan.
The upcoming September quarter is important because it tests that framework in real time. Expected higher earnings and revenue help the near term story, but the recent softening in sentiment around the $0.94 EPS line highlights the main risk right now, pressure on returns if Southeast credit quality or loan demand softens.
The most relevant data point heading into this print is the latest quarterly expectation of $0.94 per share, which implies a 22.1% increase year on year. That puts a spotlight on whether Renasant can keep net interest margins and fee income resilient enough to match the step up embedded in that figure.
Recent downward tweaks to that EPS view and an Earnings ESP of 1.06% indicate that analysts may be less confident about a clean beat. For investors, the key question is execution: whether management can keep credit costs contained, loan growth disciplined, and expenses tight enough for this quarter to support, rather than weaken, the existing catalyst path.
Renasant's current analyst blueprint points to revenues of US$1.2b and earnings of US$367.6 million by 2029, built on an assumed 5.4% yearly revenue growth rate and an earnings increase of about US$53.5 million from US$314.1 million today.
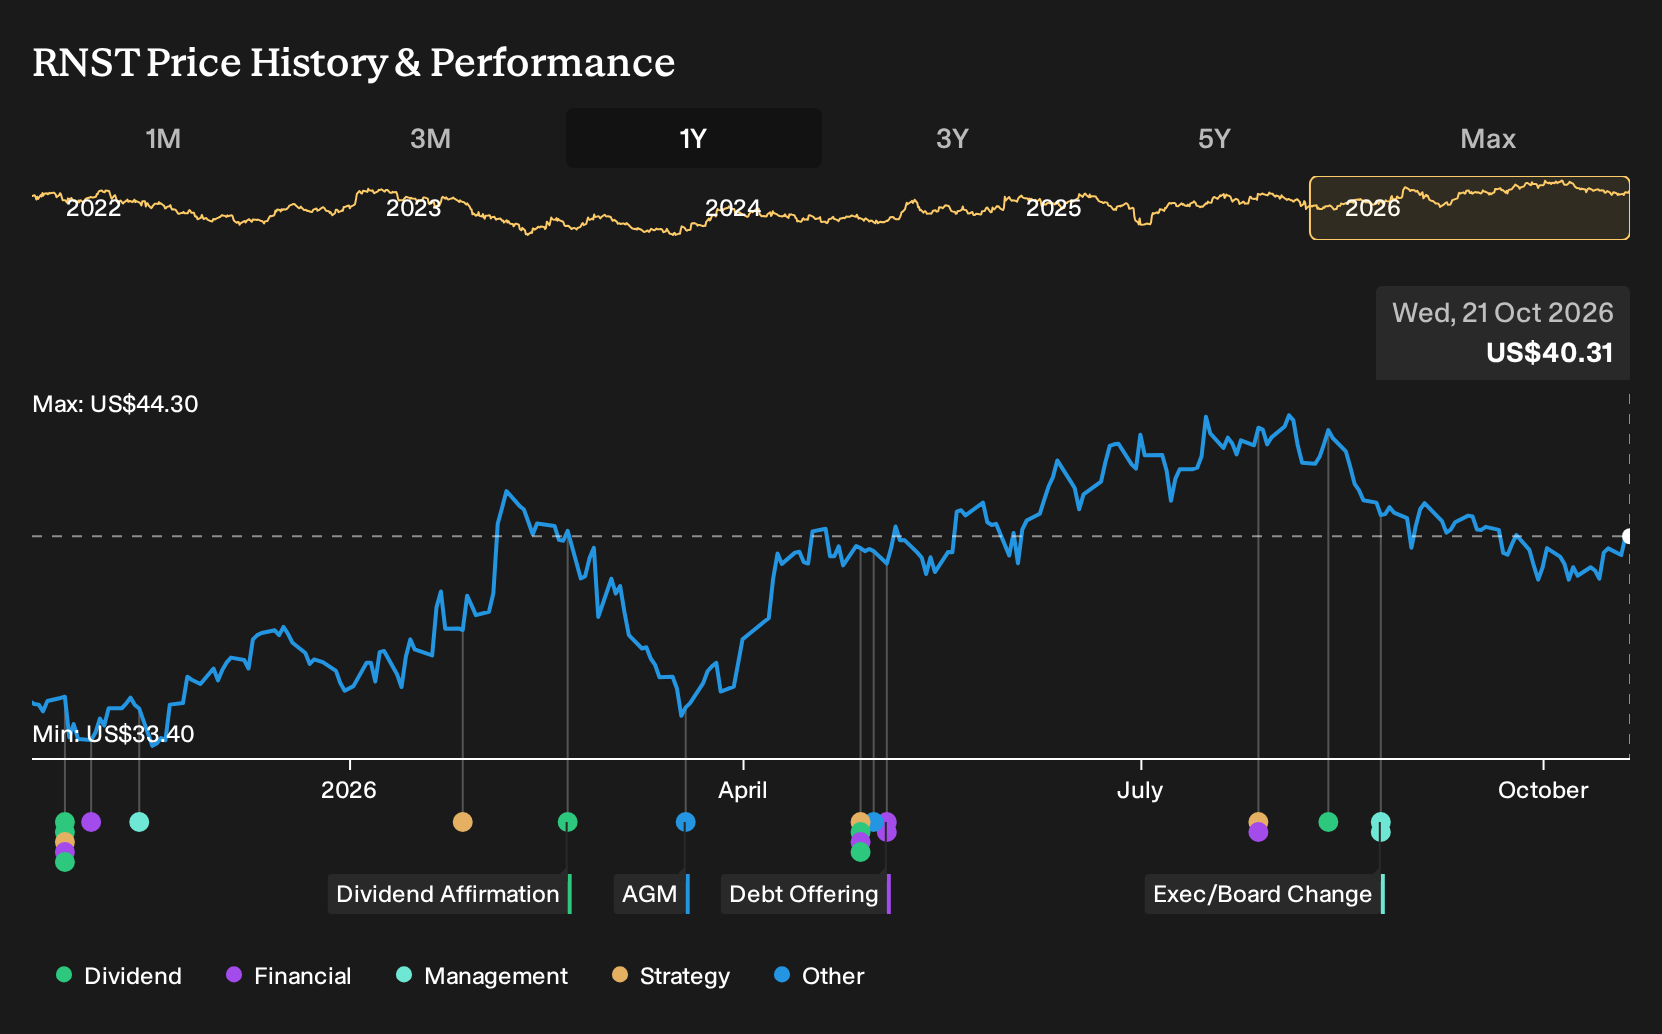
Uncover why Renasant's fair value indicates an 18% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between US$47.71 and US$53.33, which already shows how far private views on Renasant can stretch. These were formed before the latest EPS revisions, so you now need to weigh them against regional credit risk, loan demand shifts, and your own read on future earnings resilience.
Explore 2 other Renasant fair value estimates, including one that suggests it could be worth just $47.71.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Renasant research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Renasant. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which can help you evaluate Renasant's overall financial position at a glance.
Looking for more investment ideas beyond Renasant?
If the Renasant story has sharpened your thinking, broaden your watchlist by using the Simply Wall St Screener to spot other companies that fit the kind of risk and return profile you care about most.
- If resilience and balance sheet strength matter to you, start with a curated 31 resilient stocks with low risk scores that aims to prioritise durability when conditions change.
- For investors who want potential mispricing backed by fundamentals, scan a focused 33 high quality undervalued stocks that filters for quality businesses trading below their assessed worth.
- If you prefer firms with staying power and room to run, check a targeted 21 high quality undiscovered gems that highlights quality that has not yet attracted wide attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com