
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
A.P. Møller Mærsk (CPSE:MAERSK B) Eyes Vietnam Rail Terminals, Is The Stock 18% Overvalued?
A.P. Møller - Mærsk (CPSE:MAERSK B) is back in focus after APM Terminals signed a non-binding deal with Vietnam’s Hateco Group to explore a nationwide rail freight terminal network.
The Hateco rail agreement comes after a strong run in A.P. Møller - Mærsk’s shares, with the 90-day share price return up 38.69% and the year-to-date gain at 61.54%. The 1-year total shareholder return of 89.74% suggests that momentum has been building rather than fading.
Scan beyond A.P. Møller - Mærsk to find other logistics-backed plays with pricing or balance sheet appeal using our hand picked 189 high quality undervalued stocks.
After a near 90% 1 year return and a share price above the consensus target, A.P. Møller - Mærsk now forces a choice: lean into the momentum or wait for the valuation to come back to you?
Most Popular Narrative: 18% Overvalued
A.P. Møller - Mærsk closed at DKK23,730, while the most followed narrative places fair value closer to DKK20,167 using a 6.24% discount rate. That gap creates a tension between strong recent returns and more cautious long term assumptions on shipping and logistics economics.
The ongoing decline in average freight rates due to industry overcapacity, combined with intensifying digitalization and the rise of asset-light competing platforms, poses a structural challenge to Maersk's pricing power and long-term revenue growth. If investors are discounting these headwinds, forecasts for sustained high profitability or outsized long-term earnings may be too optimistic.
See why 65 investors see A.P. Møller - Mærsk as 18% overvalued.
Result: Fair Value of DKK20,167 (OVERVALUED)
Still, if Gemini delivers deeper cost savings or the terminals keep ROIC near current levels, A.P. Møller - Mærsk could surprise anyone anchored to this fair value.
Find out about the key risks to this A.P. Møller - Mærsk narrative.
Another View: A.P. Møller - Mærsk On Earnings Multiples
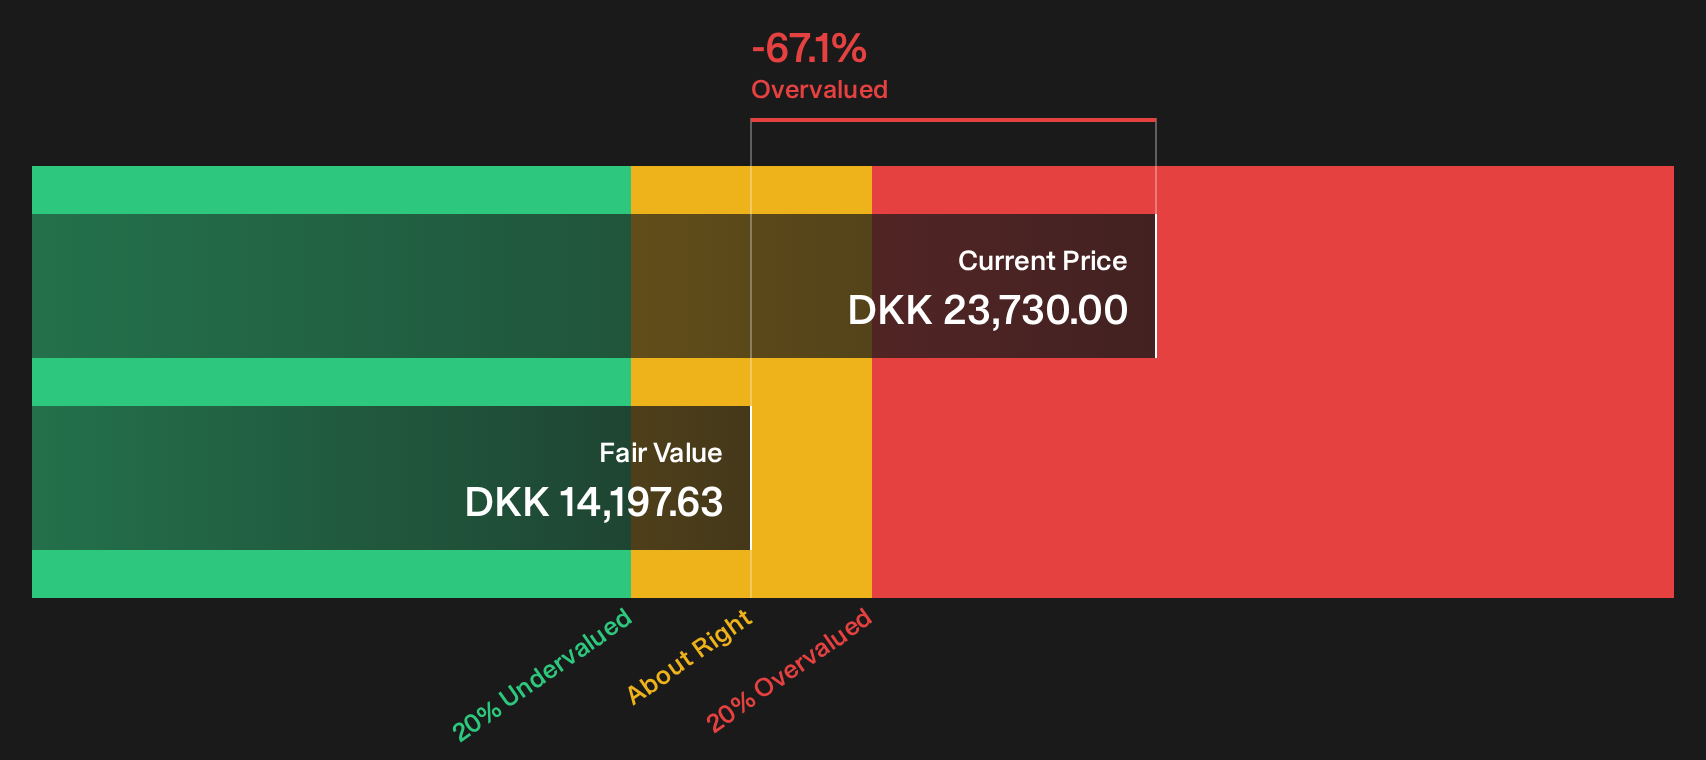
The SWS DCF model flags A.P. Møller & Mærsk as expensive, with the DKK23,730 share price sitting above an estimated future cash flow value of DKK14,197.63. That gap points to limited margin for error if earnings or cash flows come in softer than expected. Does the current price fully reflect that risk, or is the market comfortable paying up for the story anyway?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
If the combination of strong recent returns and cautious fair value estimates around A.P. Møller - Mærsk leaves you undecided, move quickly to review the underlying data for yourself. Then weigh those findings against the 4 important warning signs.
Looking for more investment ideas beyond A.P. Møller - Mærsk?
If A.P. Møller - Mærsk feels fully priced to you right now, broaden your watchlist and let a few targeted stock shortlists do the heavy lifting.
- Target resilient income potential by reviewing 221 dividend fortresses that aim to pair higher yields with business models built to handle rougher conditions.
- Hunt for quality at a discount through the 618 high quality undiscovered gems that focus on strong fundamentals the wider market may be overlooking.
- Dial down portfolio stress by scanning 227 resilient stocks with low risk scores so you are not scrambling for safer ideas after volatility has already hit.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com