
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
TTM Technologies (TTMI) Expands AI Capacity, Is The Upside Already Priced In?
TTM Technologies (TTMI) is back in focus after management laid out fresh guidance alongside a new capacity buildout plan, tying billions in projected sales to rising demand for AI infrastructure hardware.
Despite the fresh capacity plans and guidance, TTM Technologies’ recent trading has been choppy. The share price has risen 6.95% over the last day but fallen 17.63% over 30 days and 29.48% over 90 days, even as the year-to-date share price return is 44.67% and the 1-year total shareholder return is 83.43%. This indicates that longer-term momentum has been strong, while shorter-term sentiment has cooled.
Scan beyond TTM Technologies and see how other PCB and AI hardware suppliers are shaping this surge in infrastructure demand with a curated list of 55 AI infrastructure stocks.
TTM Technologies is lining up significant AI-focused capacity plans, and its guidance points to the potential for much larger sales. The business case appears strong. The open question is whether the recent share price slide already reflects that strength.
Most Popular Narrative: 52% Undervalued
Against a last close of $102.15, the most followed narrative anchors TTM Technologies at a fair value of $211, using a 9.03% discount rate and tying that gap directly to AI and defense driven expansion.
Global capacity investments of more than US$1.2b through 2029 in Syracuse Ultra HDI, Penang and multiple China expansions, together with initial European manufacturing footholds via Swiss Technology Group and ILFA, position TTM Technologies to support reshoring, AI and regional defense demand and to scale future revenue. Penang’s progress toward breakeven helps protect margins.
Find out how 46 investors see TTM Technologies as 52% undervalued.
Result: Fair Value of $211 (UNDERVALUED)
Still, the narrative could crack if TTM Technologies ends up with underused new capacity, or if higher debt leaves less room to absorb setbacks.
Find out about the key risks to this TTM Technologies narrative.
Another View: What TTM Technologies’ P/E Is Telling You
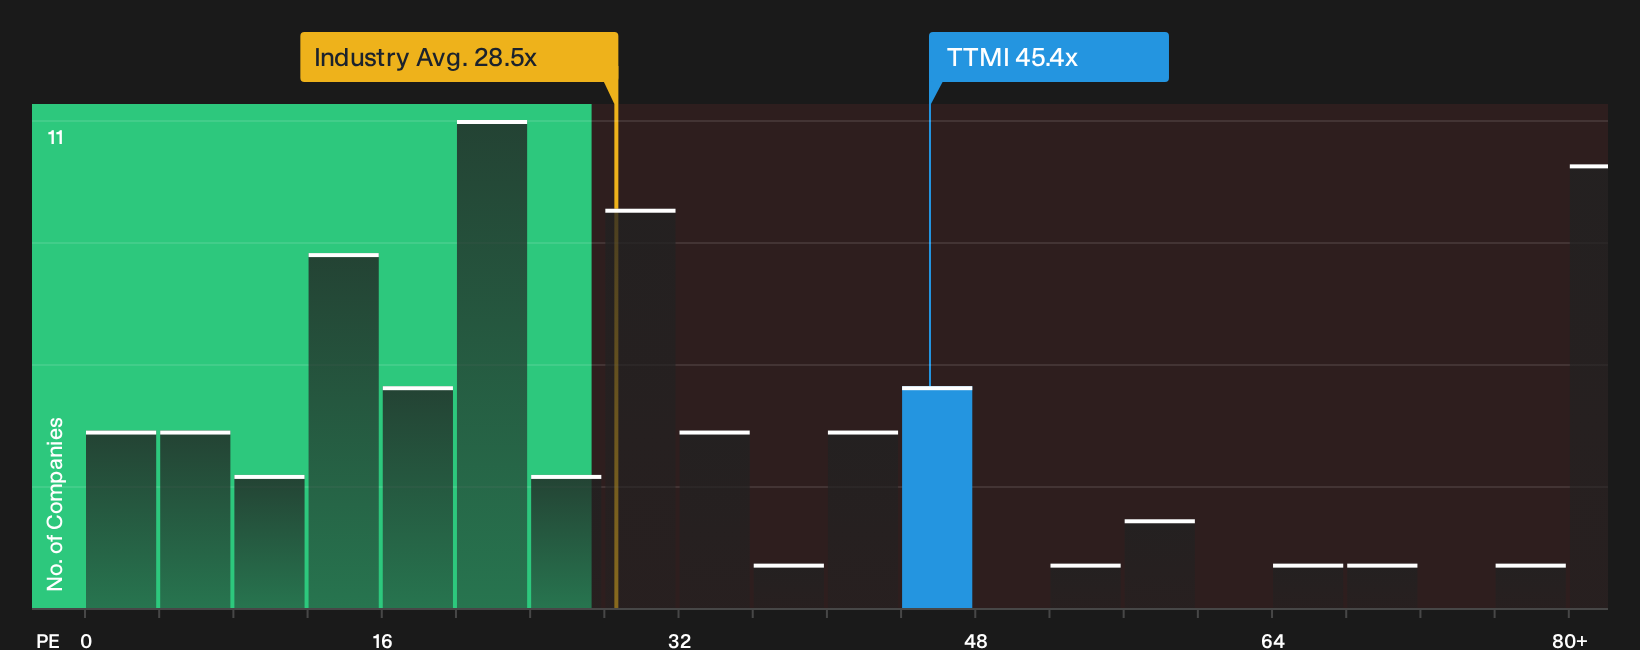
Against the narrative fair value of $211, TTM Technologies trades on a P/E of 45.4x, which is higher than both the US Electronic industry at 28.5x and its peer group at 29.9x, even though the fair ratio points to 65.7x. That gap frames extra upside if earnings unfold as expected, but it also raises the question of how much room is left if sentiment cools or forecasts get trimmed.
See what the numbers say about this price in our valuation breakdown, then compare them to the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this mix of enthusiasm and caution around TTM Technologies feels familiar, consider taking action while sentiment is still shifting and weigh the data for yourself. The fastest way to pressure test both sides is to review the 4 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond TTM Technologies?
If TTM Technologies has sharpened your focus on quality opportunities, do not stop here. Broaden your watchlist with ideas filtered for strength, resilience, and value.
- Target resilience by focusing on companies with sturdier finances and lower perceived risk through the 31 resilient stocks with low risk scores.
- Hunt for underappreciated quality by scanning a curated pool of potential value opportunities using the 33 high quality undervalued stocks.
- Zero in on balance sheet strength and fundamental support by working through the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com