
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Beacon Financial (BBT) Could Be 17% Undervalued After Earnings And Buyback Update
Beacon Financial event recap
Beacon Financial (BBT) just packed several important updates into one day. The bank reported third quarter earnings, detailed fresh credit charge-offs, affirmed its dividend, and expanded its share repurchase authorization.
These updates arrived after a mixed stretch for Beacon Financial. The share price now stands at $28.00, and a 1-year total shareholder return of 20.85% indicates that long-term holders have fared much better than recent buyers, as shorter-term share price momentum has faded in recent months.
Scan how Beacon Financial compares to other regional lenders by running the hand-picked list of solid balance sheet and fundamentals (25 results) that focuses on banks with durable funding and sturdier fundamentals.
Beacon Financial now trades at $28 after a strong 1 year showing but a softer recent run. Do the current earnings, buyback plan and charge-offs still leave more upside than downside for new buyers?
Most Popular Narrative: 17% Undervalued
On the most followed narrative, Beacon Financial screens as undervalued, with a fair value estimate of $33.67 against the recent $28 close, and that gap hinges on how its merger, funding mix and credit costs play out.
Sticky, lower cost deposits from Berkshire combined with disciplined deposit beta management as rates move lower provide a favorable funding mix that can protect the net interest margin and support more resilient revenue and earnings across cycles.
See why 4 investors see Beacon Financial as 17% undervalued.
Result: Fair Value of $33.67 (UNDERVALUED)
Still, Beacon Financial carries clear pressure points, including elevated criticized office and equipment finance exposure, as well as merger integration work that could unsettle clients and staff if mismanaged.
Find out about the key risks to this Beacon Financial narrative.
Another view on Beacon Financial’s valuation
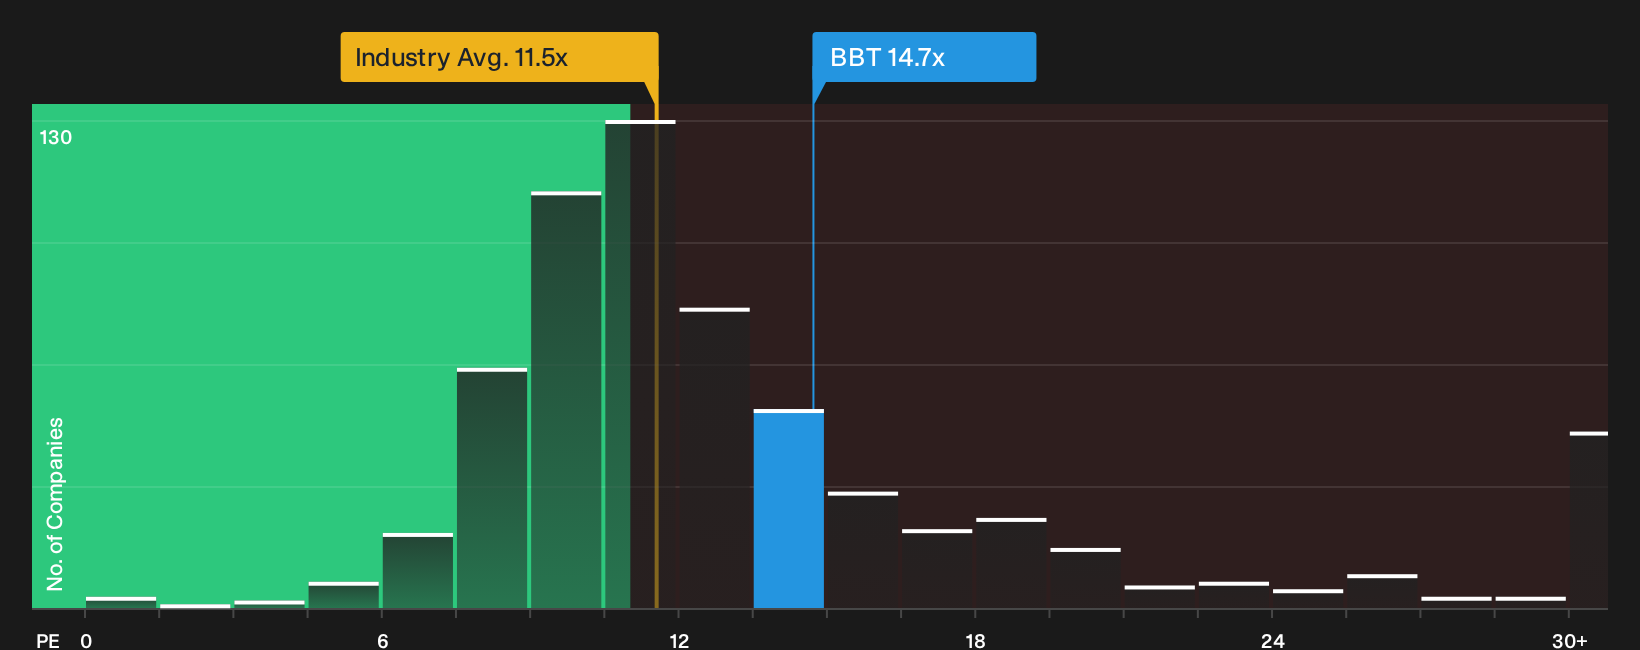
The story looks different once price ratios are brought in. Beacon Financial trades on a 14.7x P/E, which is richer than both its direct peer group at 11.1x and the wider US banks sector at 11.5x. It is still below a fair ratio of 17.4x that the market could move toward over time. That mix of premium pricing today and theoretical headroom on the fair ratio raises a simple question for investors: Is the bigger risk paying up too early or hesitating if the stock edges closer to that higher multiple?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals often create the most interesting setups. This Beacon Financial story is no exception, so review the data, weigh the trade offs, and pressure test whether the potential upside feels worth the clear risks in your own portfolio using the 4 key rewards and 1 important warning sign.
Looking for more Beacon Financial style investment ideas?
If Beacon Financial caught your attention, do not stop here. Fresh opportunities keep surfacing, and a few minutes with the Simply Wall Street Screener could reshape your watchlist.
- Target stronger value potential by reviewing companies that appear mispriced on quality and fundamentals through the 33 high quality undervalued stocks.
- Lock in more predictable cash returns by scanning income-focused opportunities via the 7 dividend fortresses.
- Prioritise resilience first by filtering for sturdier businesses and balance sheets using the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com