
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
DHT Holdings (DHT) Books Fresh VLCC Coverage On A Valuation Debate
DHT Holdings (DHT) has put fresh numbers on the table for its very large crude carrier fleet, with roughly half of fourth quarter spot days and most revenue days already locked in.
The share price reaction has been punchy. DHT Holdings has a 1-day share price return of 3.5% and a 30-day move of 7.6%, contributing to a 90-day gain of 31.2% and a year-to-date share price return of 105.8%. This has helped deliver a 1-year total shareholder return of 126.5% and a 5-year total shareholder return of about 4.6x, suggesting that momentum has been building as investors weigh stronger booked charter coverage against shifts in VLCC rates and oil prices.
Look beyond DHT Holdings and compare it with a hand-picked 33 high quality undervalued stocks that combine strong cash generation with solid balance sheets.
DHT Holdings has rerated sharply on booked VLCC coverage, yet the share price still sits only slightly below the average analyst target while implying a very different intrinsic value range. Where does fair value really land now?
Most Popular Narrative: 2.8% Undervalued
The prevailing DHT Holdings narrative pegs fair value at $24.85, a touch above the last close at $24.16. This puts the focus squarely on whether today’s tanker earnings and margins can support that gap over time.
The mix of existing high-rate time charters, including multi-year contracts around $75,000 to $100,000 per day on vessels like DHT Jaguar and DHT Panther, is building a sizeable backlog that can support visibility on future TCE revenue and EBITDA. This reinforces expectations for strong cash generation that current valuation multiples already capture.
See why 101 investors see DHT Holdings as 3% undervalued.
Result: Fair Value of $24.85 (UNDERVALUED)
Still, DHT Holdings carries real pressure points, including dividends that recently exceeded free cash flow, and insider sales that could quickly challenge today’s upbeat valuation story.
Find out about the key risks to this DHT Holdings narrative.
Another View: DCF Flags DHT Holdings As Overvalued
The fair value story changes once the SWS DCF model is brought in. On this measure, DHT Holdings at $24.16 trades well above an estimated future cash flow value of $17.73. That puts the stock at roughly a 36% premium. Which valuation anchor do you treat as your north star?
For a closer look at how this cash flow view is constructed, Look into how the SWS DCF model arrives at its fair value.
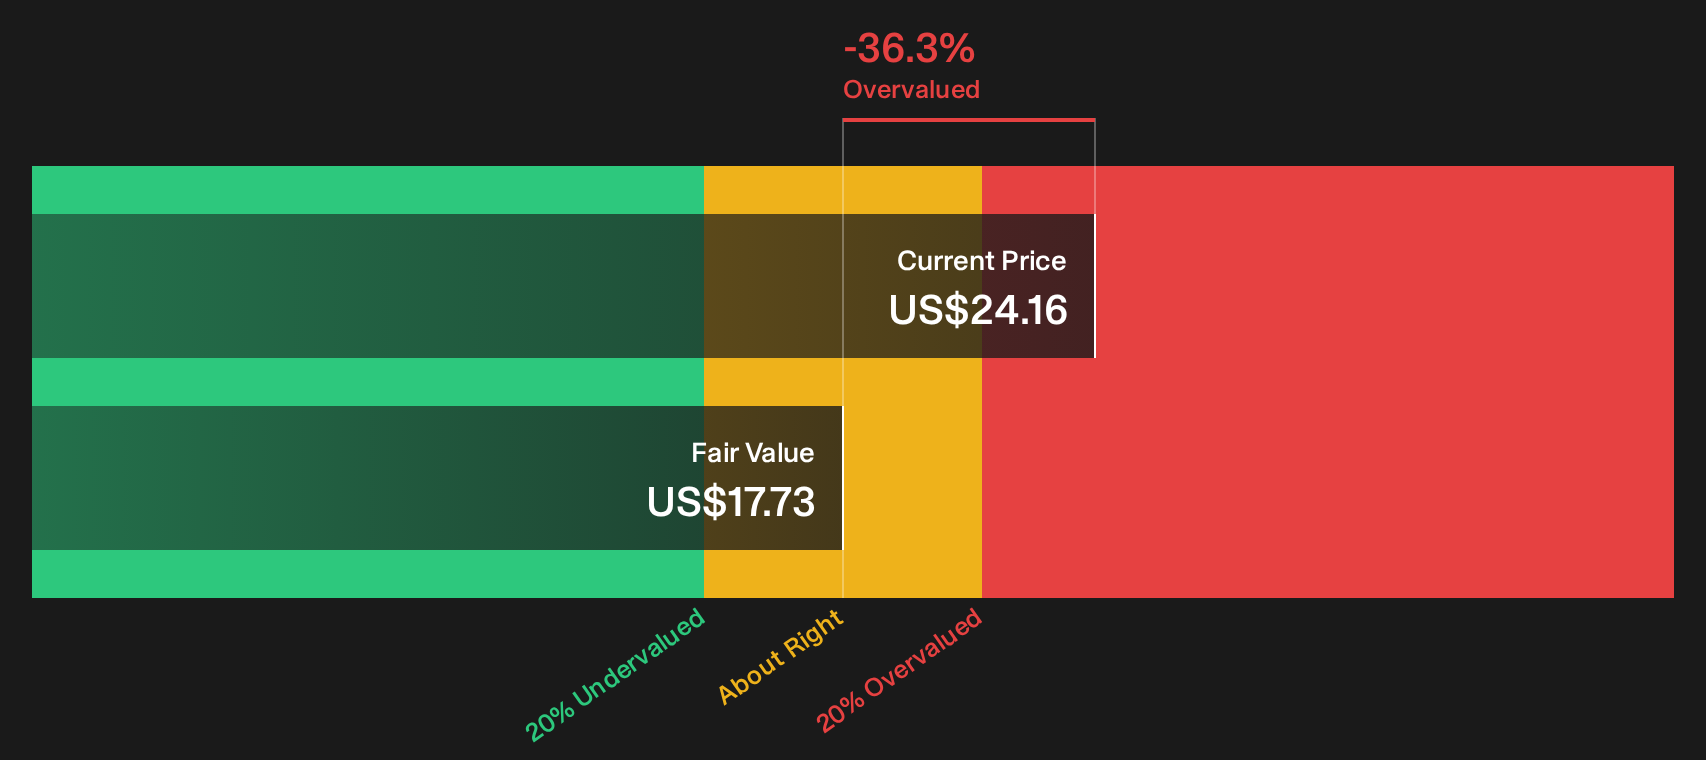
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out DHT Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on DHT Holdings valuation and risk can be hard to parse, so move quickly, review the data yourself, and weigh the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond DHT Holdings?
If DHT Holdings has your attention, do not stop there. Broaden your watchlist now so you are not late to the next opportunity.
- Target resilient cash generators by scanning a 33 high quality undervalued stocks that already pair solid balance sheets with strong underlying fundamentals.
- Strengthen portfolio stability by reviewing a list of solid balance sheet and fundamentals (25 results) that highlights businesses with sturdy financial foundations.
- Spot future winners early by working through a 21 high quality undiscovered gems that surfaces quality companies many investors may still be overlooking.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com