
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Intertek Group (LSE:ITRK) Fully Valued Following Rule 8.3 Offer Interest?
Intertek Group (LSE:ITRK) is back in focus after a cluster of Rule 8.3 disclosures showed hedge funds and banks building positions through ordinary shares and cash-settled derivatives in relation to a potential offer situation.
Intertek Group’s share price at £59.2 has moved steadily higher this year, with a year to date share price return of 30% and a 1 year total shareholder return of 21.73%. The 3 year total shareholder return of 60.77% points to momentum that hedged funds and banks now appear keen to trade around this potential offer situation.
Scan how other potential offer targets are trading by comparing Intertek Group with a curated 6 high quality undervalued stocks that currently pairs stronger balance sheets with prices below intrinsic estimates.
Intertek Group now sits at a crossroads, where a 30% year-to-date rise could signal faith in its quality assurance engine, or simply a rush of offer-driven enthusiasm that pulls the valuation away from fundamentals.
Most Popular Narrative: 1% Overvalued
The most followed narrative now pegs Intertek Group’s fair value at £58.49, which sits just below the latest £59.2 close, so the takeover noise is brushing up against a valuation that already looks quite full on these assumptions.
The global trend toward electrification, decarbonization, and investment in advanced technologies, ranging from battery storage to data centers and renewable energy, directly fuels the demand for Intertek's testing and assurance services in high-growth, high-margin end markets, boosting both revenues and earnings resilience.
See why 40 investors see Intertek Group as 1% overvalued.
Result: Fair Value of £58.49 (OVERVALUED)
Still, analyst concerns around FX headwinds and slower like for like growth in Health and Safety, Industry and Infrastructure, and World of Energy could easily challenge that fair value story.
Find out about the key risks to this Intertek Group narrative.
Another View: Intertek Group Through A Cash Flow Lens
While the analyst narrative places Intertek Group close to fair value at £58.49 based on earnings assumptions, the SWS DCF model presents a different perspective. It values future cash flows at £68.69 per share, which puts the current £59.2 price about 13.8% below that estimate. Which perspective do you think better reflects risk and reward?
Our DCF work is fully laid out, so you can judge the moving parts for yourself, from discount rate to margin path, in the Look into how the SWS DCF model arrives at its fair value.
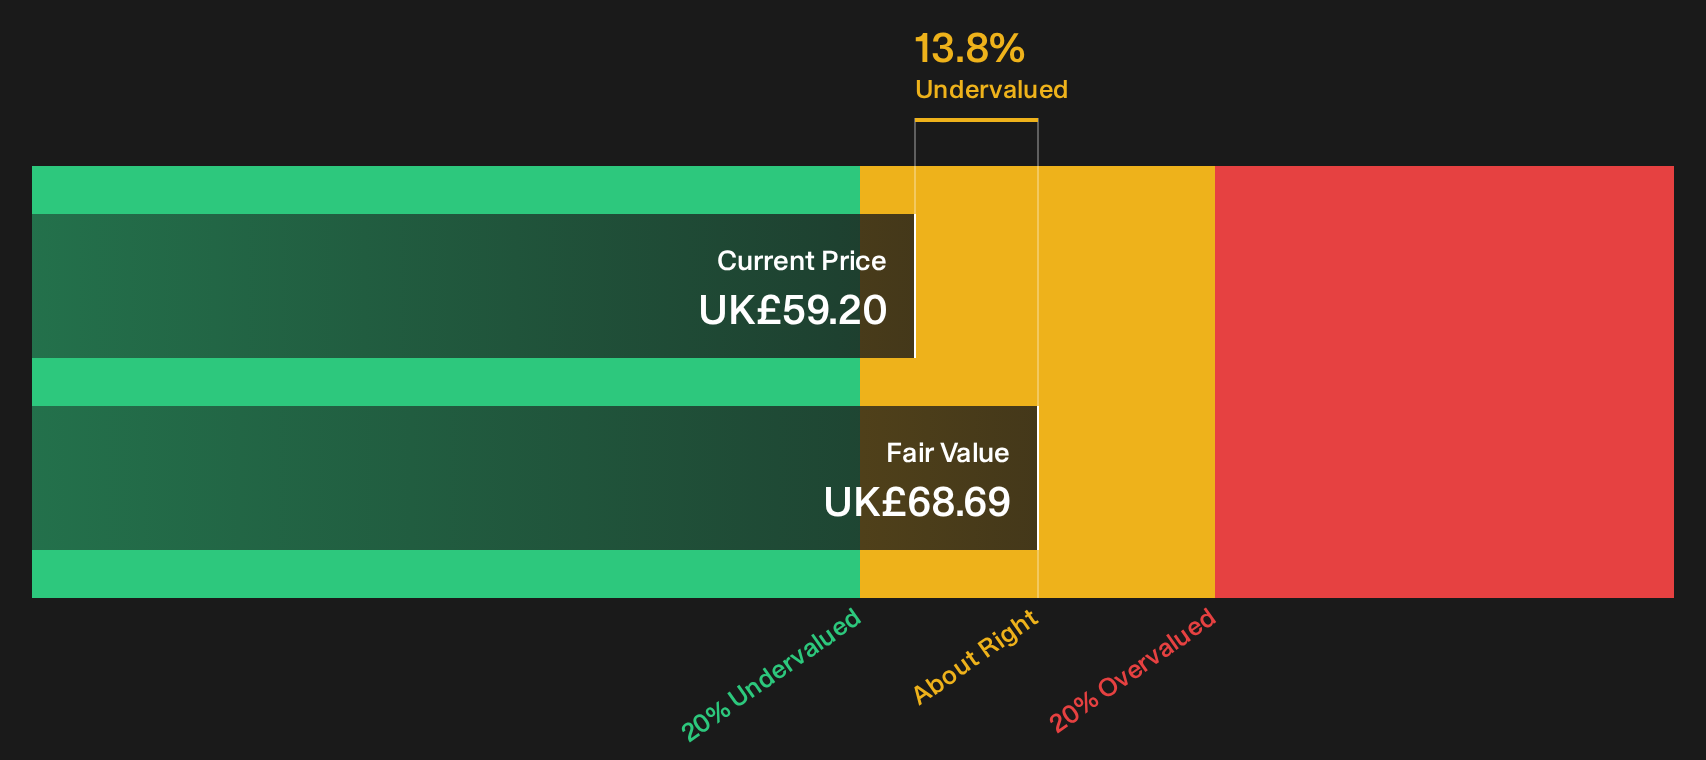
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Intertek Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 6 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Intertek Group so far. If you want a view that is actually your own, explore both the potential upside and the key concerns in the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Intertek Group?
Do not stop with Intertek Group. Fresh ideas often come from comparing opportunities side by side, and the right screener can surface candidates you might otherwise miss.
- Target resilience first and filter for companies with sturdier finances through a list of solid balance sheet and fundamentals (9 results) that keeps weak balance sheets off your list.
- Hunt for mispriced quality by scanning a curated 6 high quality undervalued stocks that focuses on strong fundamentals trading below intrinsic estimates.
- Spot future standouts early and comb through a 5 high quality undiscovered gems before other investors start paying attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com