
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
DocuSign (DOCU) Has Investors Looking Closer, What Is Behind The Attention?
Analyst optimism around DocuSign (DOCU) has intensified after a run of earnings beats, and the mood is being reinforced by fresh product news and deeper integrations with Salesforce and leading AI partners.
Short-term momentum around DocuSign has been strong, with a 30-day share price return of 18.83% and a 90-day gain of 73.21% as investors respond to the Salesforce integration news and the new PDF Editor launch. At a share price of $81.48, that near term surge contrasts with a 1-year total shareholder return of 15.48% and a 5-year total shareholder return that declined 70.69%, giving recent buyers a sharp upswing while longer term holders still sit on heavy drawdowns.
Scan how DocuSign's surge compares with other software and AI agreement platforms by reviewing the curated 21 high quality undiscovered gems that are moving on similar product and partnership catalysts.
Bulls see DocuSign reinventing its agreement platform just as earnings estimates climb, while bears point to past drawdowns and analyst targets below the current price. Which case does the valuation work support next?
Most Popular Narrative: 34% Overvalued
DocuSign's most followed valuation story pins fair value at $60.99, which sits well below the recent $81.48 close. According to rcb9, the gap between those two figures hinges on how investors treat tax-distorted earnings, share-based pay and the newer Intelligent Agreement Management segment.
The accounting gap is where the real cost sits. Q1 delivered GAAP diluted EPS of $0.40 and non-GAAP of $1.09. That $0.69 gap across 196 million shares is roughly $135 million a quarter, about 15% of revenue, predominantly share-based compensation. The non-GAAP operating margin of 30.5% to 31% is real in the sense that the cash exists, but shareholders pay for it in ownership rather than in cash.
See why 6 investors see DocuSign as 34% overvalued.
Result: Fair Value of $60.99 (OVERVALUED)
Still, that 7% growth and 15% margin path leans heavily on IAM hitting its ARR targets and share based compensation declining meaningfully over time.
Find out about the key risks to this DocuSign narrative.
Another View: What P/E Says About DocuSign
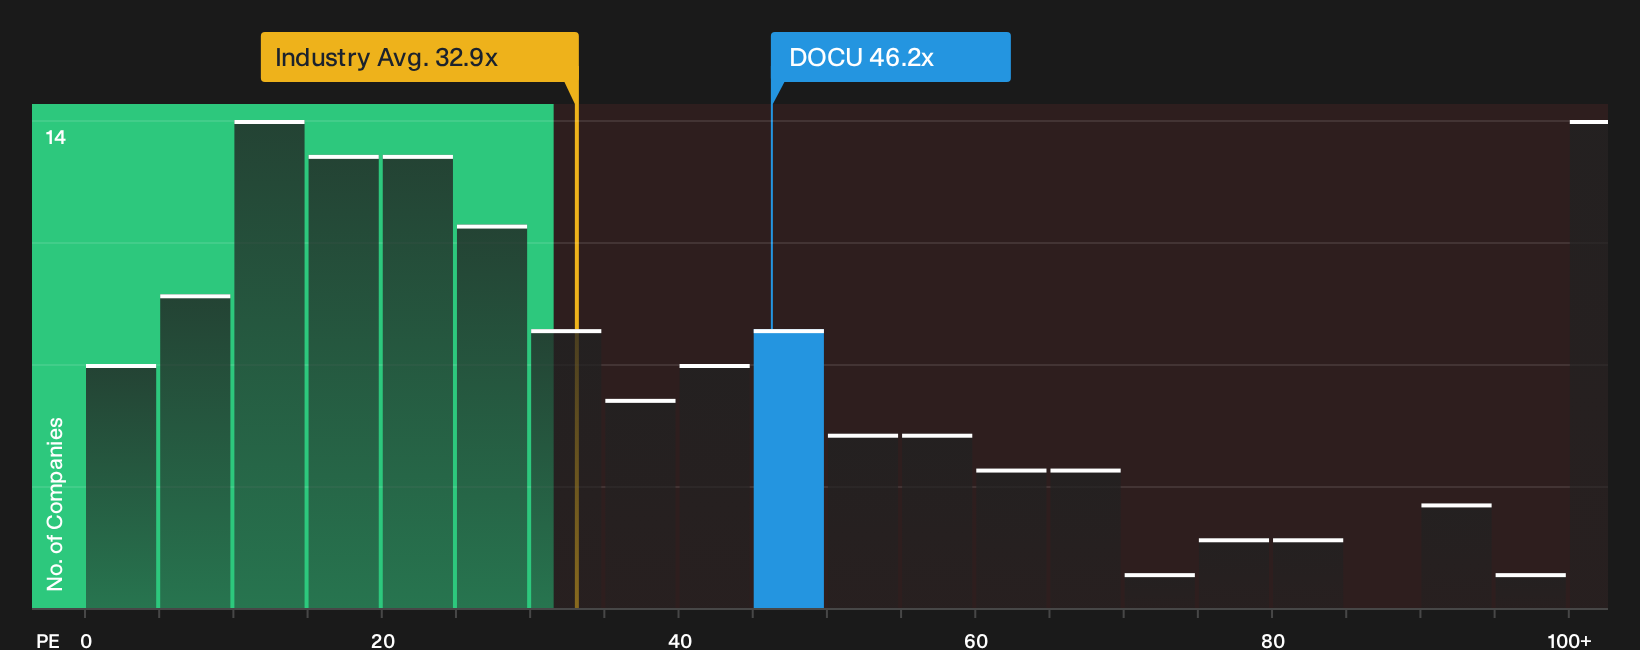
Strip out the narrative work and DocuSign looks expensive on simple P/E math. The stock trades at 46.2x earnings, above the US Software sector on 32.9x, and above its own fair ratio of 34.8x. That gap points to valuation risk if sentiment cools.
For investors who prefer to anchor decisions on earnings multiples rather than detailed forecasts, the key question is how comfortable you are paying a premium today with the expectation that fundamentals could grow into it, or whether you would rather wait for the ratio to move closer to the fair ratio implied by the data.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the split views on DocuSign leave you on the fence, now is the moment to look through the numbers yourself and weigh both the concerns and the upside. To see the balance of potential downsides and bright spots in one place, start with the 3 key rewards and 1 important warning sign.
Ready for more ideas beyond DocuSign?
If DocuSign has sharpened your appetite for opportunity, use the Simply Wall St Screener to quickly surface fresh candidates that fit the way you like to invest.
- Target resilient cash flows by running your eye over a 7 dividend fortresses that aims to pair income with staying power.
- Hunt for quality at a discount by scanning a 33 high quality undervalued stocks built around solid balance sheets and compelling valuations.
- Spot tomorrow's potential early by tracking a curated 10 elite penny stocks with strong financials that already show strong financial foundations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com