
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Alnylam Pharmaceuticals (ALNY) Cuts 2026 Guidance After AMVUTTRA Sales Beat, Is It Fully Valued
Alnylam Pharmaceuticals (ALNY) drew fresh attention after management lowered full-year revenue guidance for 2026, even as AMVUTTRA delivered record sales from its expansion into treating ATTR cardiomyopathy.
Alnylam Pharmaceuticals’ share price, now at US$225.10, has fallen 7.9% over the past month and 16.2% over the past quarter, while the year to date share price return is down 43.8% as investors reassess growth visibility after the guidance cut. That pullback contrasts with a 41.1% three year total shareholder return and 17.8% over five years, suggesting longer term holders have still seen gains even as near term momentum has faded.
Scan beyond Alnylam Pharmaceuticals and see how other biotechs with strong pipelines and clearer entry points compare in our hand-picked 21 high quality undiscovered gems.
Bulls see Alnylam Pharmaceuticals as a newly profitable RNAi platform that has been punished too harshly for tempered guidance. Bears see a slowing flagship and rising competition. Which story does the valuation actually reflect?
Most Popular Narrative: 39% Undervalued
Against the last close at $225.10, the most followed narrative for Alnylam Pharmaceuticals points to a fair value of $371.35, framing a wide gap that hinges on how the RNAi pipeline and TTR franchise play out.
The broad RNAi portfolio at Alnylam Pharmaceuticals, with more than 25 programs across rare, specialty and prevalent conditions and multiple pivotal studies underway, creates repeated opportunities for new approvals that could add incremental revenue streams and help spread fixed R&D and SG&A over a larger sales base, which may support earnings.
The large pool of adults with uncontrolled hypertension and the Phase II profile of twice yearly zilebesiran, including an average placebo adjusted 10 mmHg reduction in systolic blood pressure with year long 24 hour control, set up a potential new product cycle in a very wide cardiovascular market that could influence long term revenue and operating margin mix.
See why 29 investors see Alnylam Pharmaceuticals as 39% undervalued.
Result: Fair Value of $371.35 (UNDERVALUED)
Still, the Alnylam Pharmaceuticals story can change quickly if AMVUTTRA pricing pressure intensifies or high R&D spending outpaces new product uptake.
Find out about the key risks to this Alnylam Pharmaceuticals narrative.
Another View: What The P/E Ratio Says About Alnylam Pharmaceuticals
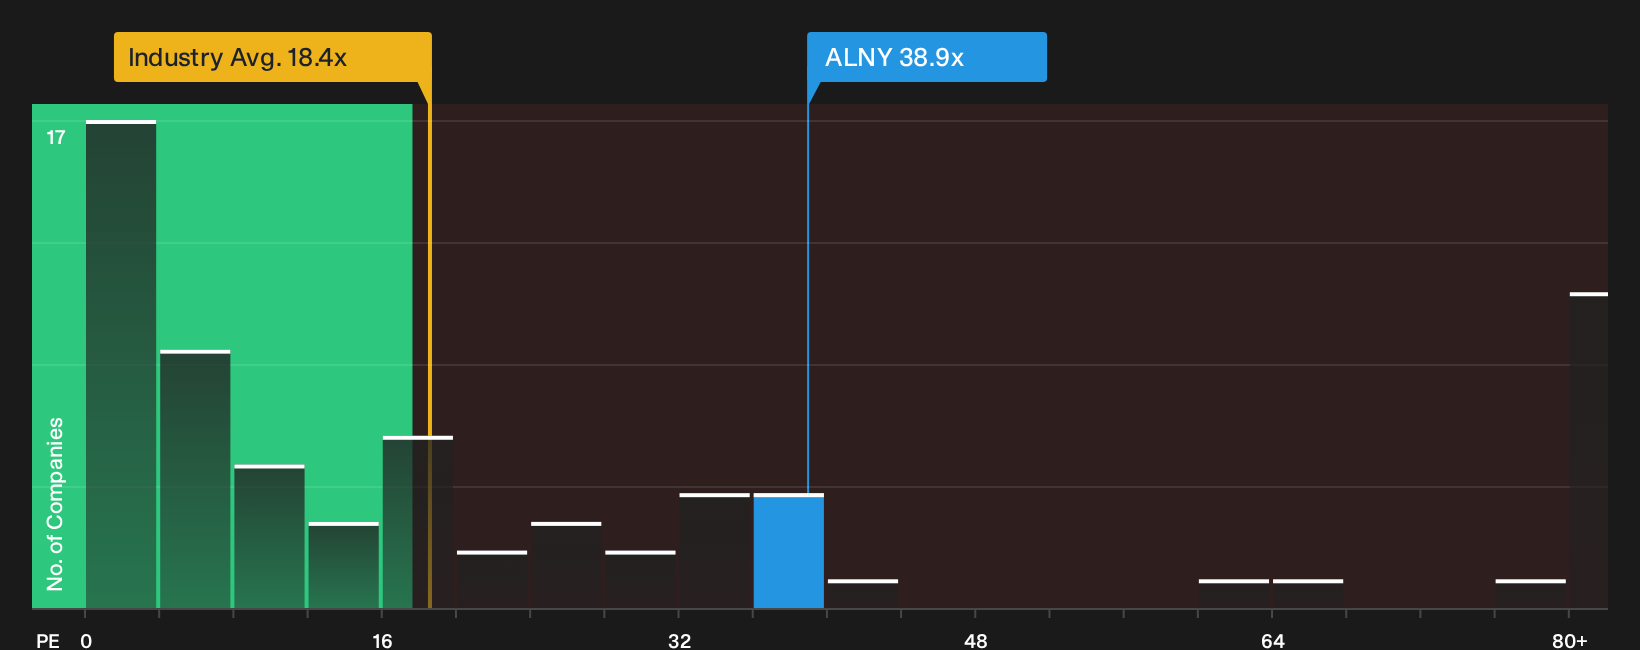
The DCF based narrative presents Alnylam Pharmaceuticals as undervalued, yet the current P/E of 38.9x tells a less forgiving story. That multiple sits above the US Biotechs industry at 18.4x, the peer average at 35.6x, and the fair ratio estimate of 32.1x, which suggests the market could shift toward lower pricing. If the story is about a discounted opportunity, why is the earnings multiple already this high?
To examine how that earnings multiple compares with the fair ratio and sector, and what that might indicate for upside or downside risk in practical terms, take a closer look at our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Alnylam Pharmaceuticals can be useful if you treat them as a prompt rather than an answer. Consider acting while sentiment is still split and weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Alnylam Pharmaceuticals?
If Alnylam Pharmaceuticals has you rethinking your watchlist, do not stop with one ticker. Fresh ideas often come from scanning outside your usual comfort zone.
- Target resilient compounding potential by focusing on companies that screen well for both quality and valuation through our 33 high quality undervalued stocks.
- Strengthen your income stream by zeroing in on businesses with payouts that clear a high bar in our 7 dividend fortresses.
- Dial down portfolio stress by filtering for companies with sturdy finances and clean balance sheets using the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com