
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
CRISPR Therapeutics (CRSP) Stock Looks Pricey After A 46% Five Year Slump
CRISPR Therapeutics has had a mixed run, with the share price falling 45.6% over the past 5 years, which puts fresh focus on whether the current US$50.50 level lines up with what its balance sheet actually supports. With the business pushing ahead on complex gene editing programs, the central question for you is how much of that story is already reflected in the stock relative to its book value.
- The 45.6% share price decline over 5 years has reshaped long term holders' experience and raises the issue of how much downside is already captured in the company's book value.
- Upcoming Phase 1b CTX310 data at the American Heart Association Scientific Sessions in November 2026 may influence expectations for future capital needs and potential returns on past research spending that sit behind the current equity base.
- The analysts covering CRISPR Therapeutics have run their own numbers. See what analysts think CRISPR Therapeutics's shares could be worth.
The issue now is whether CRISPR Therapeutics' present share price can be squared with its book value once you line it up against the industry average.
If you are weighing CRISPR Therapeutics against other book value stories, it can help to line it up beside 33 high quality undervalued stocks.
Has CRISPR Therapeutics Run Too Far on Book Value?
P/B fits CRISPR Therapeutics because investors are paying mainly for its equity base and research pipeline rather than established earnings.
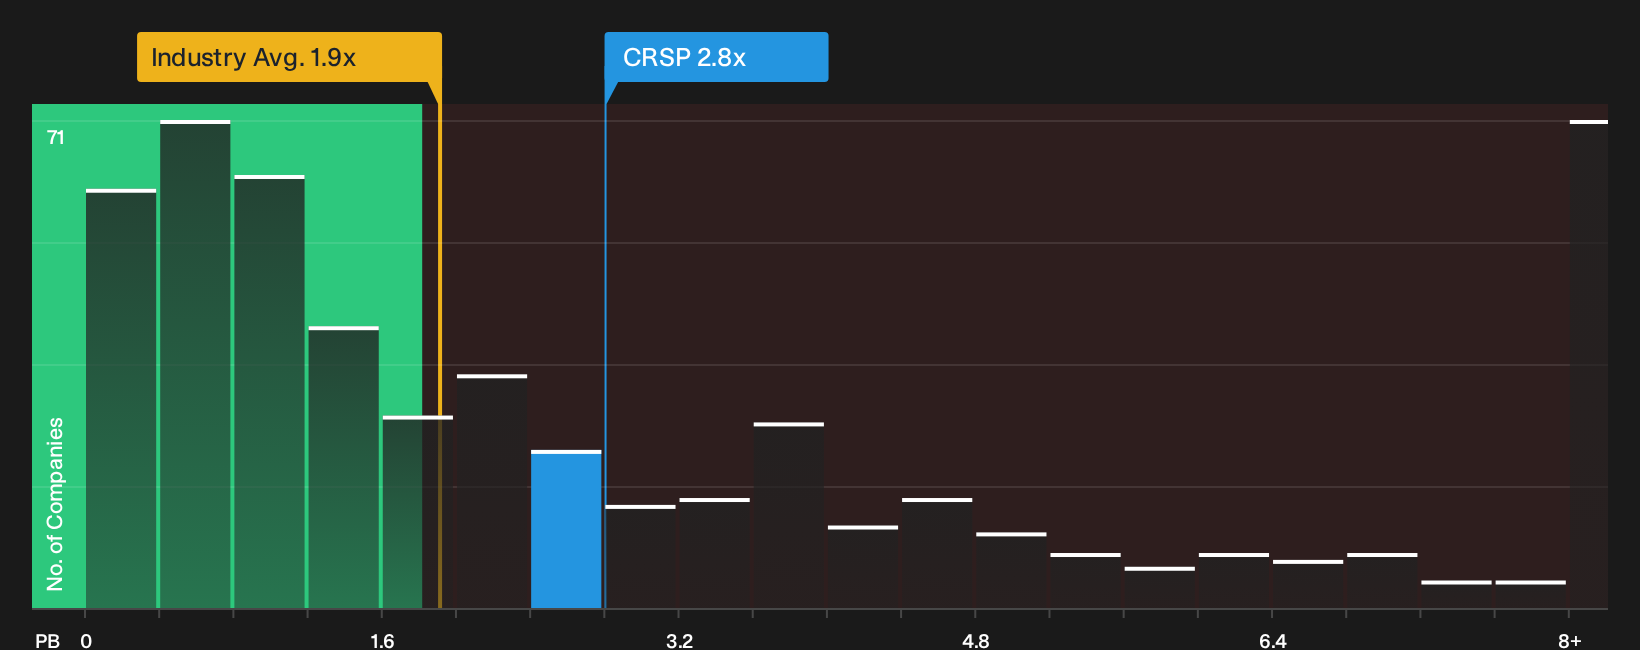
The stock trades on a P/B of 2.8x, which is above the biotech industry average of 1.9x and below the peer group at 10.4x. Despite CTX310 data heading to the American Heart Association meeting in 2026, the current P/B still prices CRISPR Therapeutics at a premium to the sector’s typical balance sheet valuation.
That gap to the industry suggests the market is attaching extra value to the company’s gene editing platform and cash position compared with a standard biotech book value story. For you as a shareholder or potential buyer, the key question is whether that higher multiple is justified by the research portfolio and risk profile that support the current equity base. Explore the numbers behind CRISPR Therapeutics's P/B valuation.
The CRISPR Therapeutics Narrative: What Would Justify Today's Price?
Narratives for CRISPR Therapeutics on Simply Wall St pick up where the P/B discussion leaves off, by spelling out which paths for revenue, profitability and cash flows would need to occur for the shares to trade well above or well below today's price. They use individual storylines that each link a fair value to a specific mix of potential catalysts and risks, so you can watch over time which scenario seems to be matching reality.
Community views on CRISPR Therapeutics now split between a large upside story and a caution that the pipeline still has plenty to prove.
Bull case: 42% undervalued
"Holding about US$2.4b in cash and marketable securities alongside access to a large shelf registration and prior issuance of convertible senior notes gives CRISPR Therapeutics room to fund multiple pivotal programs without relying on near term equity raises..."
Discover why this Narrative puts CRISPR Therapeutics at 42% undervalued.
Bear case: 15% overvalued
"The current valuation, with a market value of roughly US$3.5b compared with about US$2.4b of cash and a Neutral rating from UBS, implies limited upside for the CRISPR Therapeutics share price unless the pipeline delivers clear, near-term proof of value..."
Explore why this Narrative puts CRISPR Therapeutics at 15% overvalued.
One more CRISPR Therapeutics check before you stop at the share price
Numbers only tell part of the story, because the people steering CRISPR Therapeutics and the way their pay packages are structured can tilt long term outcomes in ways the P/B ratio never shows. See who runs CRISPR Therapeutics and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com