
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Undervalued Small Caps With Insider Buying To Watch In October 2026
Over the last 7 days, the United States market has remained flat, yet it is up 13% over the past year with earnings forecasted to grow by 17% annually. In this environment, identifying small-cap stocks that are perceived as undervalued and exhibit insider buying can offer intriguing opportunities for investors seeking potential growth.
Top 10 Undervalued Small Caps With Insider Buying In The United States
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Regional Management | 6.6x | 0.5x | 30.14% | ★★★★★★ |
| Financial Institutions | 9.7x | 3.2x | 24.69% | ★★★★★☆ |
| Bank of the James Financial Group | 11.0x | 2.5x | 25.80% | ★★★★☆☆ |
| Union Bankshares | 9.4x | 2.0x | 45.87% | ★★★★☆☆ |
| German American Bancorp | 13.2x | 4.9x | 25.31% | ★★★☆☆☆ |
| Franklin Financial Services | 11.5x | 3.1x | -43.37% | ★★★☆☆☆ |
| Citizens Community Bancorp | 15.9x | 3.5x | 11.41% | ★★★☆☆☆ |
| Shore Bancshares | 11.5x | 3.3x | 35.72% | ★★★☆☆☆ |
| New Peoples Bankshares | 9.5x | 2.6x | 8.24% | ★★★☆☆☆ |
| Orion Group Holdings | 97.3x | 0.4x | 48.51% | ★★★☆☆☆ |
Let's review some notable picks from our screened stocks.
Lantronix (LTRX)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Lantronix is a technology company focused on the development, marketing, and sale of industrial and enterprise IoT products and services, with a market capitalization of approximately $0.13 billion.
Operations: The company's revenue is primarily derived from the development, marketing, and sale of industrial and enterprise IoT products and services. Over recent periods, the gross profit margin has shown a trend around 43.79%, with fluctuations observed in different quarters. Operating expenses are consistently significant, driven by research and development as well as general administrative costs.
PE: -66.1x
Lantronix, a player in the tech sector, is catching attention with its innovative offerings like the Spotter robotics platform and Open-Q 8550CS System-on-Module. These products cater to drone and unmanned systems markets, securing a spot in the U.S. Department of War's Blue UAS Framework. Despite past shareholder dilution, insider confidence is evident with Saleel Awsare purchasing 15,000 shares for US$77,685 in September 2026. While external borrowing poses funding risks, Lantronix's strategic collaborations and product advancements suggest potential growth opportunities ahead.
- Delve into the full analysis valuation report here for a deeper understanding of Lantronix.
Explore historical data to track Lantronix's performance over time in our Past section.
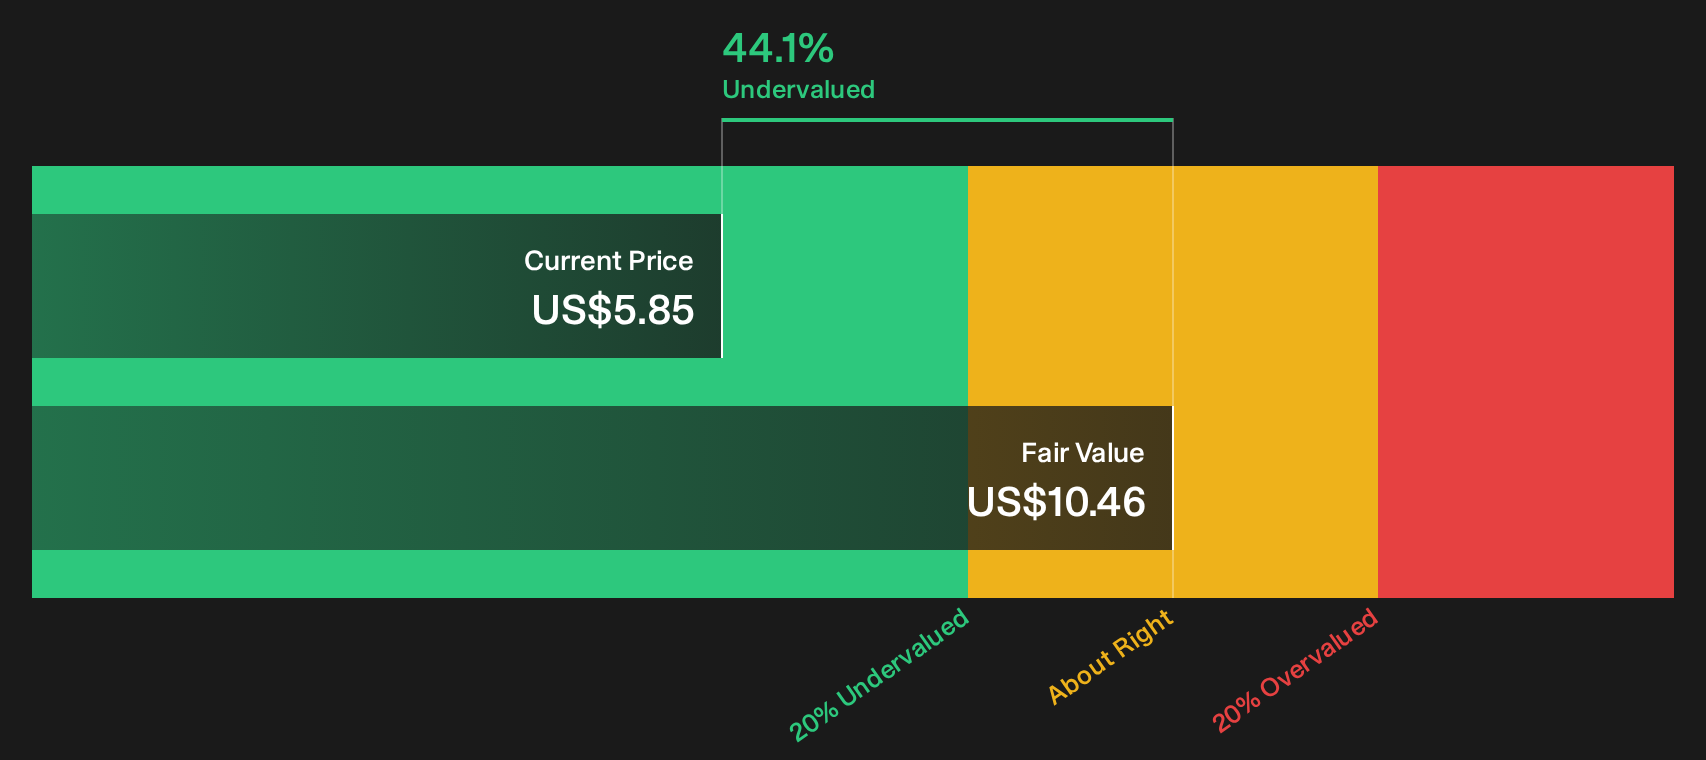
Oak Valley Bancorp (OVLY)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Oak Valley Bancorp is a financial institution primarily engaged in providing banking services, with a market capitalization of approximately $0.22 billion.
Operations: Oak Valley Bancorp generates revenue primarily from its banking operations, with a recent quarterly revenue of $83.07 million. The company's net income margin has shown variability, reaching 40.85% in June 2023 before declining to 28.23% by June 2026. Operating expenses have increased over time, with general and administrative expenses being a significant component, totaling $41.51 million in the latest period reported.
PE: 11.7x
Oak Valley Bancorp, a smaller player in the banking sector, recently reported a slight dip in net income for Q2 2026 at US$5.11 million compared to US$5.59 million the previous year, while net interest income saw an increase to US$18.94 million from US$18.15 million. Insider confidence is evident with Gary Strong's purchase of 2,000 shares valued at US$65,000 this year, reflecting potential belief in future prospects despite current earnings challenges.
- Click to explore a detailed breakdown of our findings in Oak Valley Bancorp's valuation report.
Assess Oak Valley Bancorp's past performance with our detailed historical performance reports.
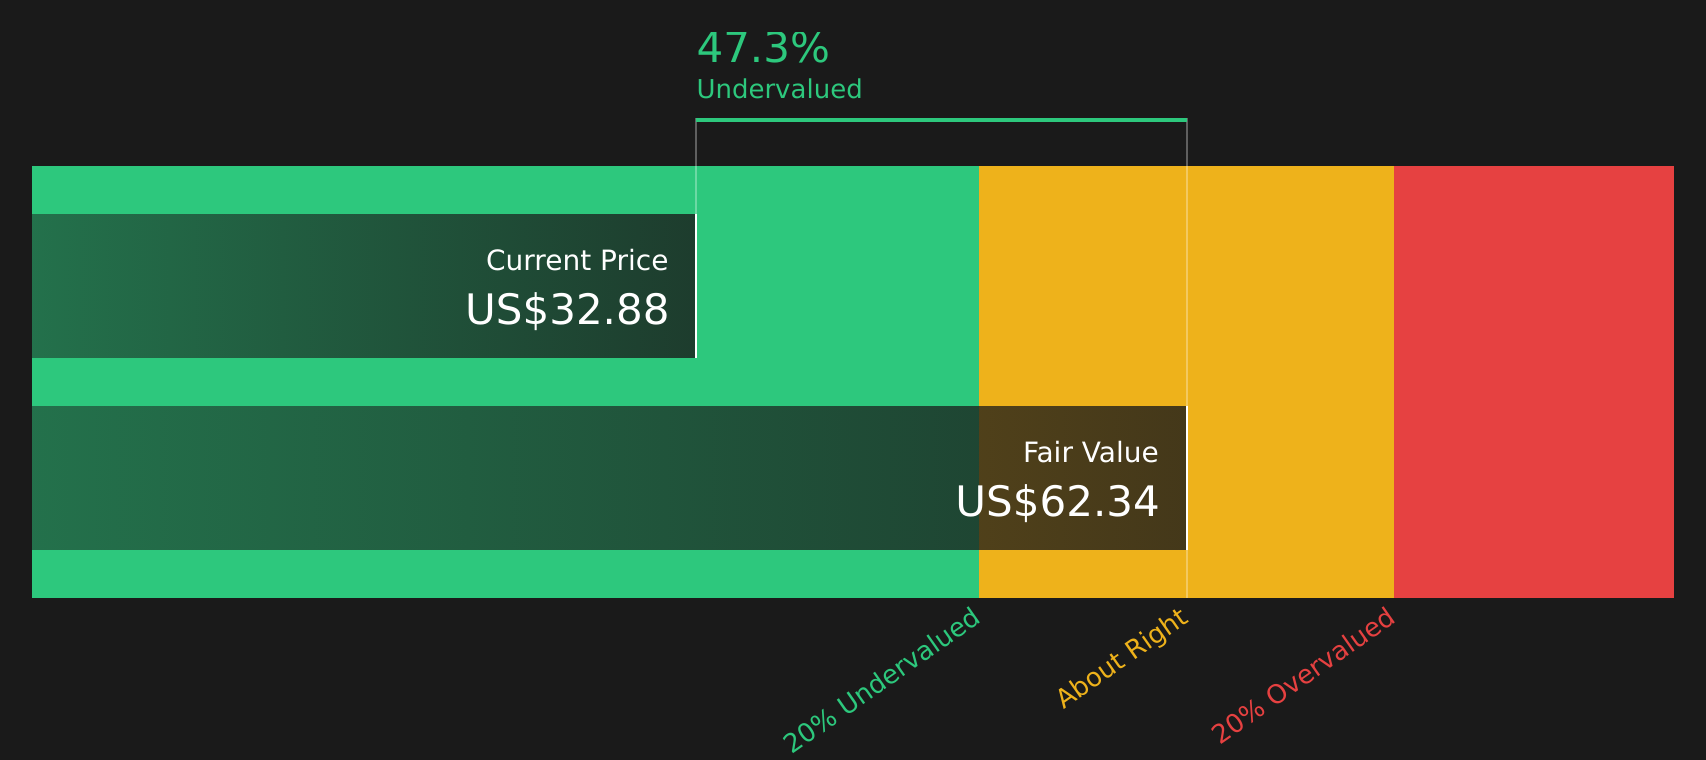
Enovis (ENOV)
Simply Wall St Value Rating: ★★★★★☆
Overview: Enovis operates in the healthcare sector, focusing on reconstructive and prevention and recovery solutions, with a market cap of $2.65 billion.
Operations: The company generates revenue primarily from its Reconstructive and Prevention and Recovery segments, with recent figures at $1.16 billion and $1.13 billion, respectively. Over the observed periods, gross profit margin has shown an upward trend, reaching 61.32% by late 2026. Operating expenses are significant, driven mainly by general and administrative costs alongside R&D expenses.
PE: -1.1x
Enovis, a smaller player in the U.S. market, has shown potential for growth despite facing challenges. Their recent earnings report highlighted a narrowing net loss to US$1.19 million from US$36.74 million year-over-year, with sales rising to US$582.78 million for Q2 2026. Insider confidence is evident as CEO Damien McDonald purchased 13,035 shares valued at approximately US$249,620 in early September 2026, suggesting belief in future prospects amidst ongoing acquisition discussions and confirmed annual revenue guidance of up to US$2.37 billion.
- Get an in-depth perspective on Enovis' performance by reading our valuation report here.
Review our historical performance report to gain insights into Enovis''s past performance.
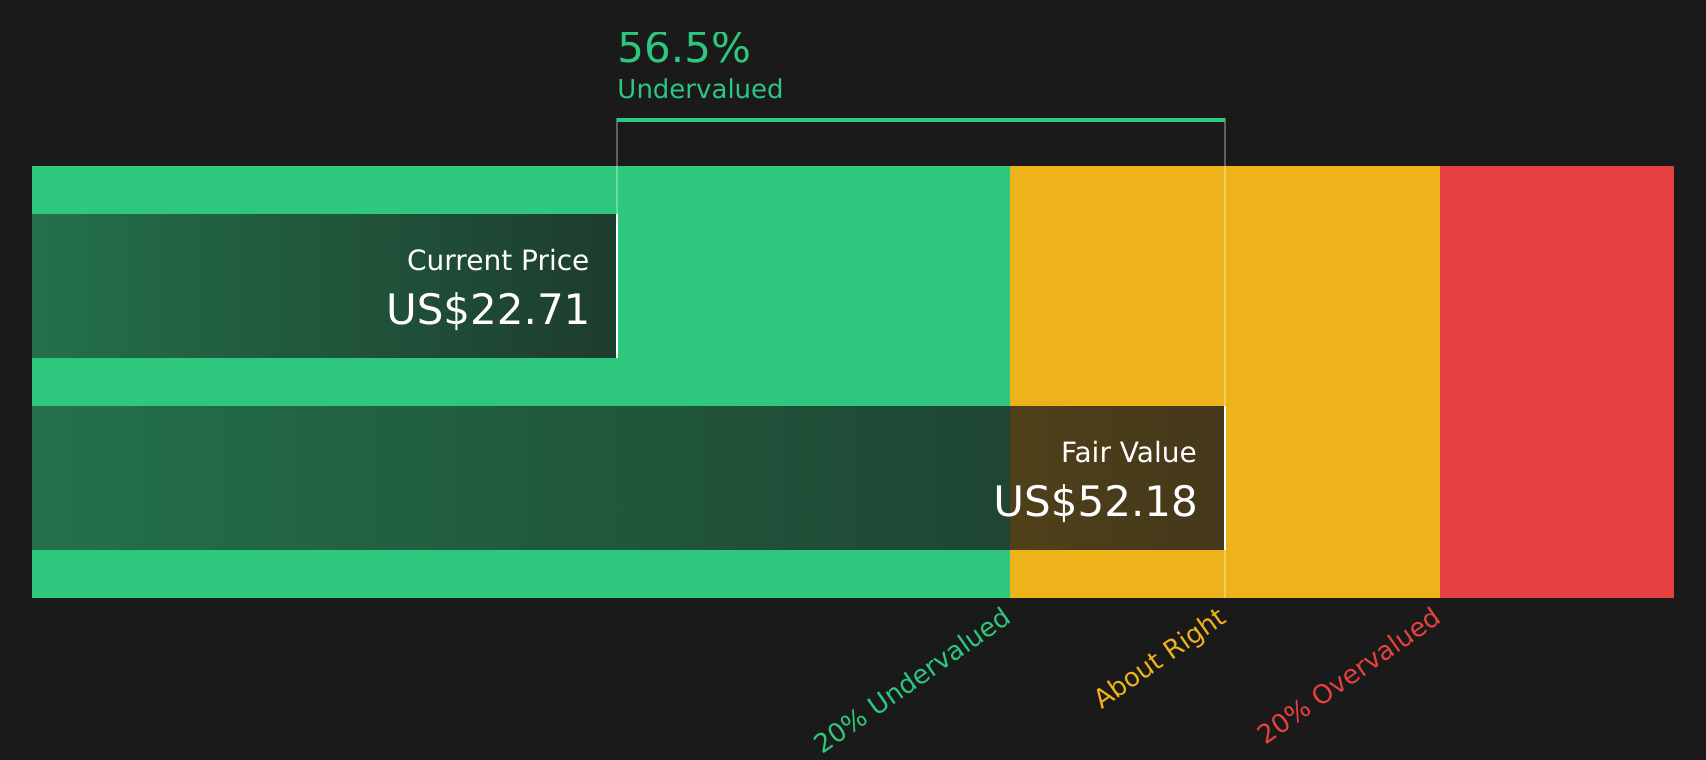
Where To Now?
- Unlock our comprehensive list of 66 Undervalued US Small Caps With Insider Buying by clicking here.
- Are any of these part of your asset mix? Tap into the analytical power of Simply Wall St's portfolio to get a 360-degree view on how they're shaping up.
- Maximize your investment potential with Simply Wall St, the comprehensive app that offers global market insights for free.
Seeking Other Investments?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com