
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
The Bet Allstate Holders Made
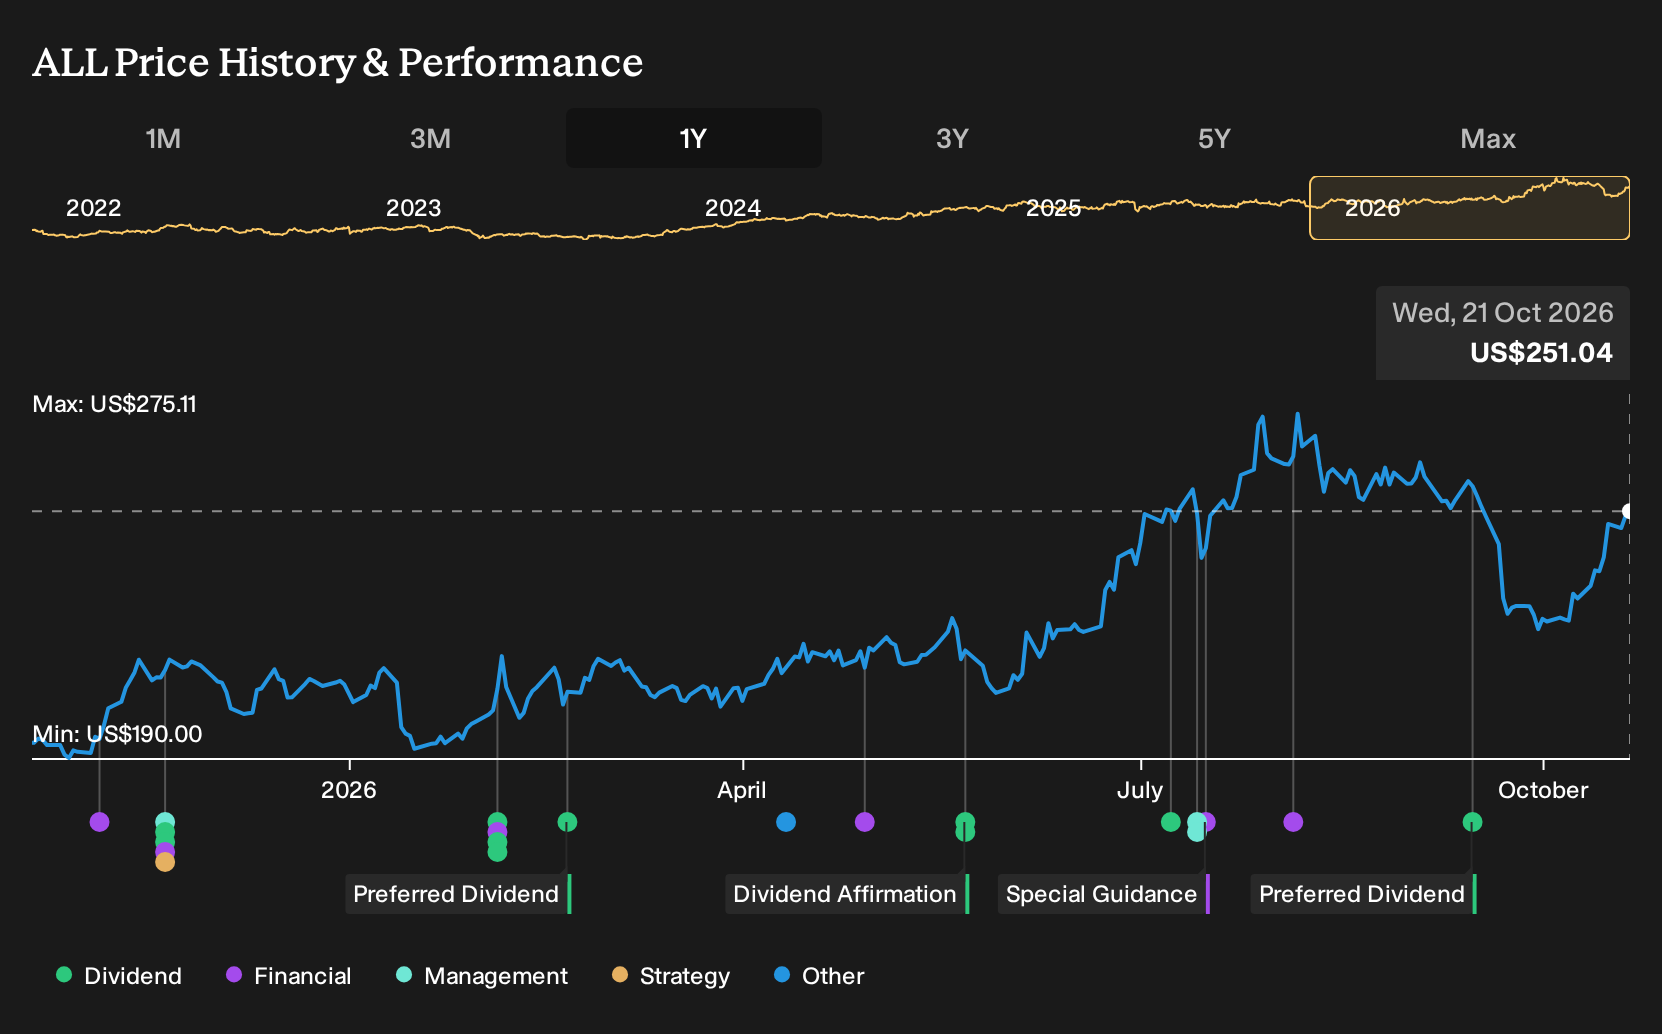
If you had trusted Allstate during a year that mixed record high earnings with eye catching catastrophe losses and insider selling headlines, the result might surprise you. Holding Allstate over the past year would have returned 31.4%, including dividends. That payoff arrived as analysts argued over whether AI powered underwriting would widen margins or whether autonomous cars and climate risk would squeeze them. If you were deciding back on 21 October 2025, what mattered most in that split view?
Allstate has already moved. See which of 33 high quality undervalued stocks still trade below our estimates.
The Two Stories Allstate Investors Had To Weigh
The shares cost US$194 at the start of the period, and Allstate investors were choosing between two very different stories about where the business could reasonably head next.
The bullish narrative put Fair Value at US$275, a price level that only made sense if aggressive technology adoption and embedded insurance expansion supported stronger growth and margins. That view leaned on assumptions such as a 6.9% annual revenue increase and a P/E of 13.7x on earnings of US$6.3b by 2028.
The bearish case argued for a Fair Value of US$150, implying the stock was too expensive if claim costs and climate events kept biting. This scenario rested on ideas such as rising catastrophe losses eroding underwriting profitability and inflation in auto repairs and medical services outpacing Allstate's ability to reprice.
What The Evidence Did To The Allstate Debate
Q2 2026 results gave Allstate bulls fresh support. Revenue was US$18,596m and net income reached US$3,241m, with net margin rising from 12.5% to 17.4% versus Q2 2025. That profitability outcome leaned toward the optimistic case that argued technology and analytics could protect underwriting economics, even as catastrophe losses and insider selling headlines kept the bearish story alive.
The lesson is simple. When a thesis focuses on better margins rather than headline growth, track net income and net margin together against the original assumptions at every earnings report.
What Allstate's 31% Run Already Prices In
Allstate trades around US$251 after a 31.4% gain over the past year. The selected Narrative places its Fair Value below that level and frames today’s quote as already baking in steady capital returns alongside catastrophe and legal risks.
To pay today’s price, you would be assuming that Allstate keeps converting its technology driven model and Protection Services push into durable, profitable policy growth that outweighs pressure from extreme weather and litigation.
"The main thing that has to go right is that Allstate converts its technology driven operating model, underwriting track record and Protection Services expansion into sustained, profitable policy growth that offsets catastrophe exposure and legal scrutiny."
One Narrative disagrees with today's price. → See where this Narrative says Allstate should trade
How Could You Get There Earlier?
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 33% below our estimate - convert shorter brownfield tieback cycles into higher margin subsea work.
- Company 2 - 22% below our estimate - embed AI assistants into cloud, productivity, developer and security tools for enterprises.
- Company 3 - 30% below our estimate - sell full-stack accelerators that power large AI factory buildouts for key customers.
Those are three of them. See the full list of 25 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com