
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Oklo (OKLO) Stock Trades At A Discount On Its 180% Five Year Run
Oklo has gone through sharp swings since its SPAC listing, and after a steep pullback investors are now asking whether the current share price lines up with what its balance sheet actually supports. With a young nuclear developer like Oklo, the gap between story and hard book value can matter a lot.
- Over the past 5 years, the stock has delivered a total return of about 179.8%, which puts a lot of weight on whether the assets on Oklo's books can support the valuation that journey has created.
- Oklo's selection by the U.S. Department of Energy to negotiate use of surplus plutonium and its progress on the Groves-2 Forge isotope facility can shape expectations for future capital needs and asset intensity, both of which link directly to how investors read its book value multiple.
- Your read on Oklo is one view; the desks covering it have another. See what analysts think Oklo's shares could be worth.
The issue now is whether Oklo's current market price is adequately supported by its book value when set against the industry average.
If you are weighing Oklo's swings against what its balance sheet can support, a focused stock screen built around similar criteria such as solid balance sheet and fundamentals stocks screener (25 results) can be a practical next step.
Is Oklo a Bargain on Book Value?
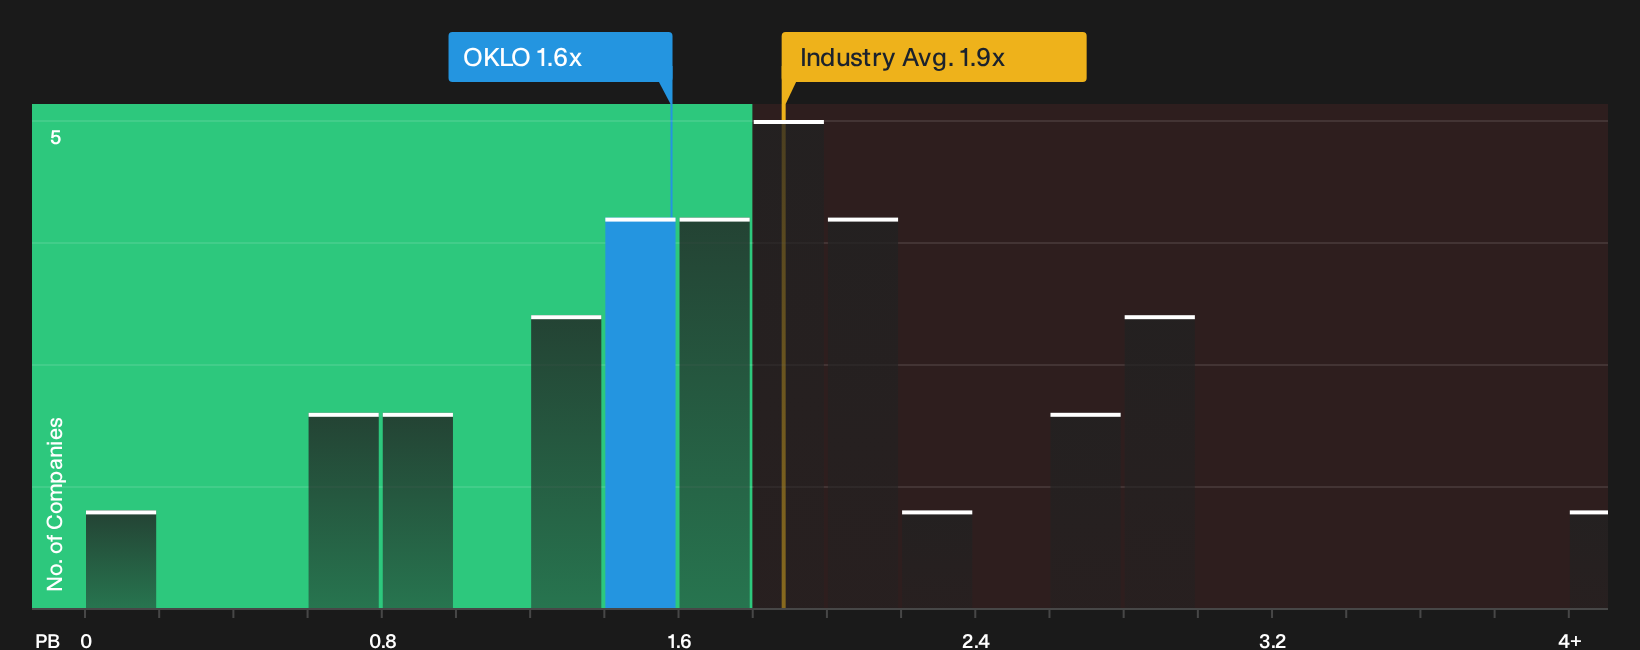
P/B fits Oklo because investors are effectively paying today for a pool of capital that still needs to prove it can earn attractive returns. On this measure, the stock trades at about 1.6x book value, compared with an Electric Utilities industry average of roughly 1.9x and a peer group closer to 1.8x. That places Oklo at a discount to the sector while still valuing each dollar of equity above a simple liquidation level.
Because the at the market equity program and DOE backed projects demand heavy upfront funding, the current 1.6x P/B suggests the market is giving Oklo some credit for its project pipeline but not pricing it as aggressively as many established utilities. Despite the recent equity offering highlighting financing risk, the shares still change hands at a lower P/B than the broader utility group, which indicates a relatively lower valuation on this single ratio. Explore the numbers behind Oklo's P/B valuation.
The Oklo Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Oklo's price to book puzzle leaves off and spell out what kind of future growth, margins and earnings path would need to play out for the shares to look meaningfully mispriced in either direction. Each one turns Oklo's implied fair value into a specific, trackable idea about how the business could develop over time, so you can revisit the same setup as new information comes through.
Oklo splits opinion, with one camp arguing the stock underprices its long term power contracts and another flagging execution and funding hurdles.
Bull case: 66% undervalued
"Oklo has already signed major agreements, for example with Switch for 12 GW through to 2044..."
Discover why this Narrative puts Oklo at 66% undervalued.
Bear case: 35% overvalued
"Oklo is building three interconnected business units (power, fuel and isotopes) at the same time..."
Explore why this Narrative puts Oklo at 35% overvalued.
One more Oklo check that belongs next to the price tag
Before you focus only on Oklo's ratios and scenarios, it pays to look at who is steering the reactor design and how their pay packets line up with your interests. See who runs Oklo and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com