
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Cardinal Health (CAH) Stock Looks Pricey On Its 7x Five Year Run
Cardinal Health has been on a striking multi year run, and the latest share price puts a lot of weight on what its earnings can reasonably support. For anyone looking at the stock today, the key issue is whether that performance is backed up by profit power or by optimism that still needs to be earned.
- Over the past 5 years Cardinal Health has delivered a very large total return of about 7x, which puts considerable pressure on the current valuation to be supported by the underlying earnings profile.
- The business depends heavily on execution in large scale pharmaceutical and medical distribution, so even modest shifts in operating efficiency or pricing power can have an outsized effect on margins and the earnings base investors are capitalizing.
- The analysts covering Cardinal Health have run their own numbers. See what analysts think Cardinal Health's shares could be worth.
For investors, the debate is whether Cardinal Health's current share price is appropriately anchored to the earnings it is generating today and is expected to produce in the future.
If you are questioning whether Cardinal Health's valuation is firmly anchored to its earnings, it can help to compare that same earnings test across 33 high quality undervalued stocks.
Has Cardinal Health Run Too Far on Earnings?
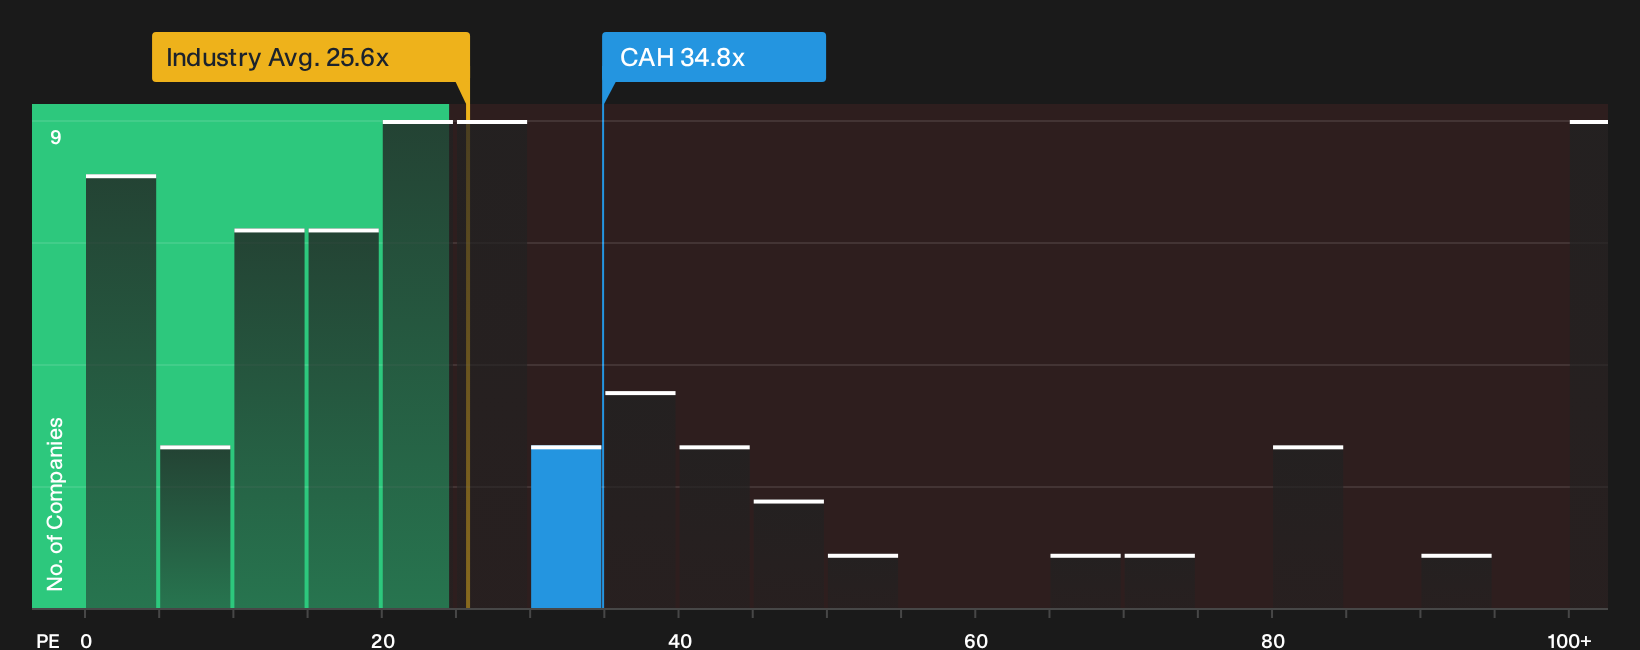
P/E is a useful lens for Cardinal Health because investors are clearly paying for its earnings stream today. The stock trades on about 34.8x current earnings, compared with roughly 28.5x for direct peers and about 25.6x for the wider healthcare group. That puts a clear premium on Cardinal Health relative to much of its sector.
A fair value framework that adjusts for Cardinal Health's own size, margins, business mix and risk profile points to a lower P/E than the one now on the screen, which means the shares screen as overvalued on this metric. For anyone holding or considering the stock, the question is whether Cardinal Health can keep justifying a richer multiple than peer distributors or whether expectations have run ahead of what its earnings base can carry. Explore the numbers behind Cardinal Health's P/E valuation.
The Cardinal Health Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Cardinal Health pick up where the P/E puzzle leaves off and spell out the specific paths for growth, margins and earnings that would need to play out for the stock to be worth materially more or less than it trades for today. Rather than giving a single number from a ratio or model, Narratives describe the future that number quietly assumes so you can track how the real business compares with it over time.
One of the top community narratives on Cardinal Health: roughly fairly valued
"The current earnings power and cash generation implied by guidance and recent results suggest the share price does not fully reflect this mix shift toward specialty, services, and a repaired medical segment..."
Discover why this Narrative puts Cardinal Health at roughly fairly valued.
Cardinal Health: why the share price is only one piece of the decision
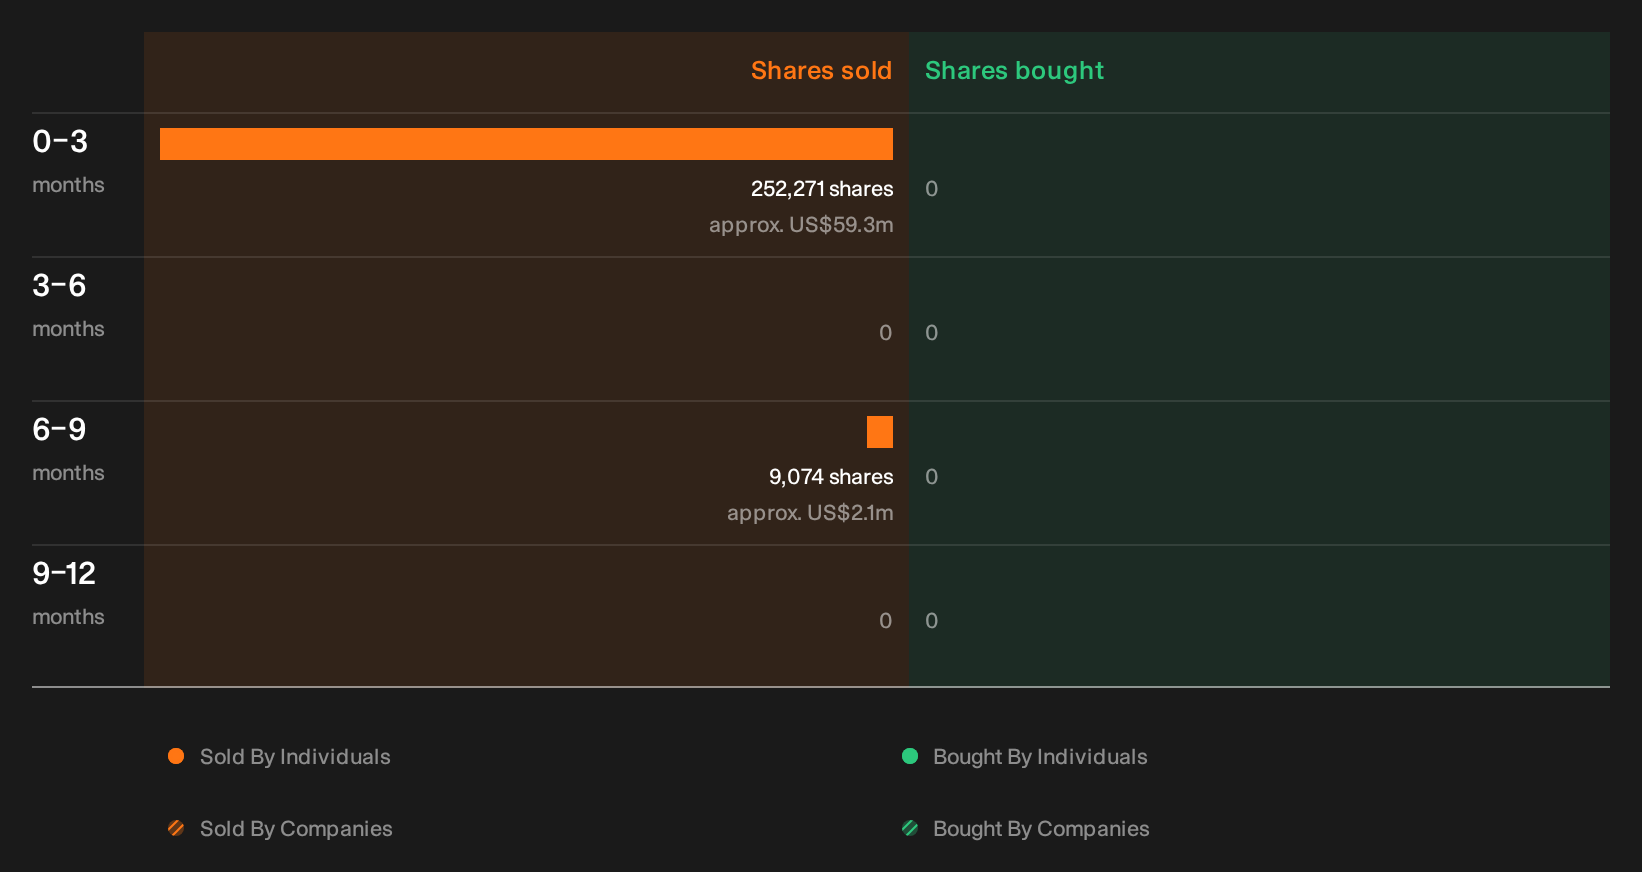
Valuation only tells you what the market is willing to pay today, not what people closest to Cardinal Health are doing with their own holdings, which our checks suggest is worth a closer look. See the recent insider selling flagged for Cardinal Health.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com