
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Top 3 AI Chip Stocks To Watch In October 2026
TSMC’s reported push to reduce reliance on Chinese rare earths highlights how fragile the plumbing of artificial intelligence hardware really is. Every chip depends on a long chain of suppliers, and any weak link can matter. That fragility creates opportunity for investors who focus on the companies providing essential tools and design expertise. This article walks through three stocks from our semiconductor supply chain screen that embody that theme.
The three stocks that follow are just a small sample, and the full semiconductor supply chain screen surfaced 12 more companies with equally compelling stories that are not covered here. If you want to identify your own angles on the AI hardware trade, head straight to the Semiconductor Supply Chain screener to filter and analyze the opportunities that fit your conviction best.
Micron Technology (MU)
Overview: Micron Technology produces DRAM, including high bandwidth memory, and NAND storage that supply the memory capacity AI data centers rely on.
Operations: Micron generates most of its revenue from the Cloud Memory and Core Data Center units, together over US$80b, with meaningful contributions from mobile, client, automotive and embedded segments across the United States and Asia.
Market Cap: US$1,014b
Micron Technology matters here because it sells the memory and storage that help turn AI accelerator hardware into usable, revenue-generating infrastructure.
"The central change is HBM. High bandwidth memory is stacked DRAM designed to feed AI accelerators with enough bandwidth to keep them busy."
What really moves the needle for Micron now is how one evolving supply and pricing balance shapes the durability of those rich margins.
That margin question is exactly what the full narrative for Micron Technology unpacks in detail, revealing how Micron Technology’s AI memory cycle could decouple from old boom and bust patterns.

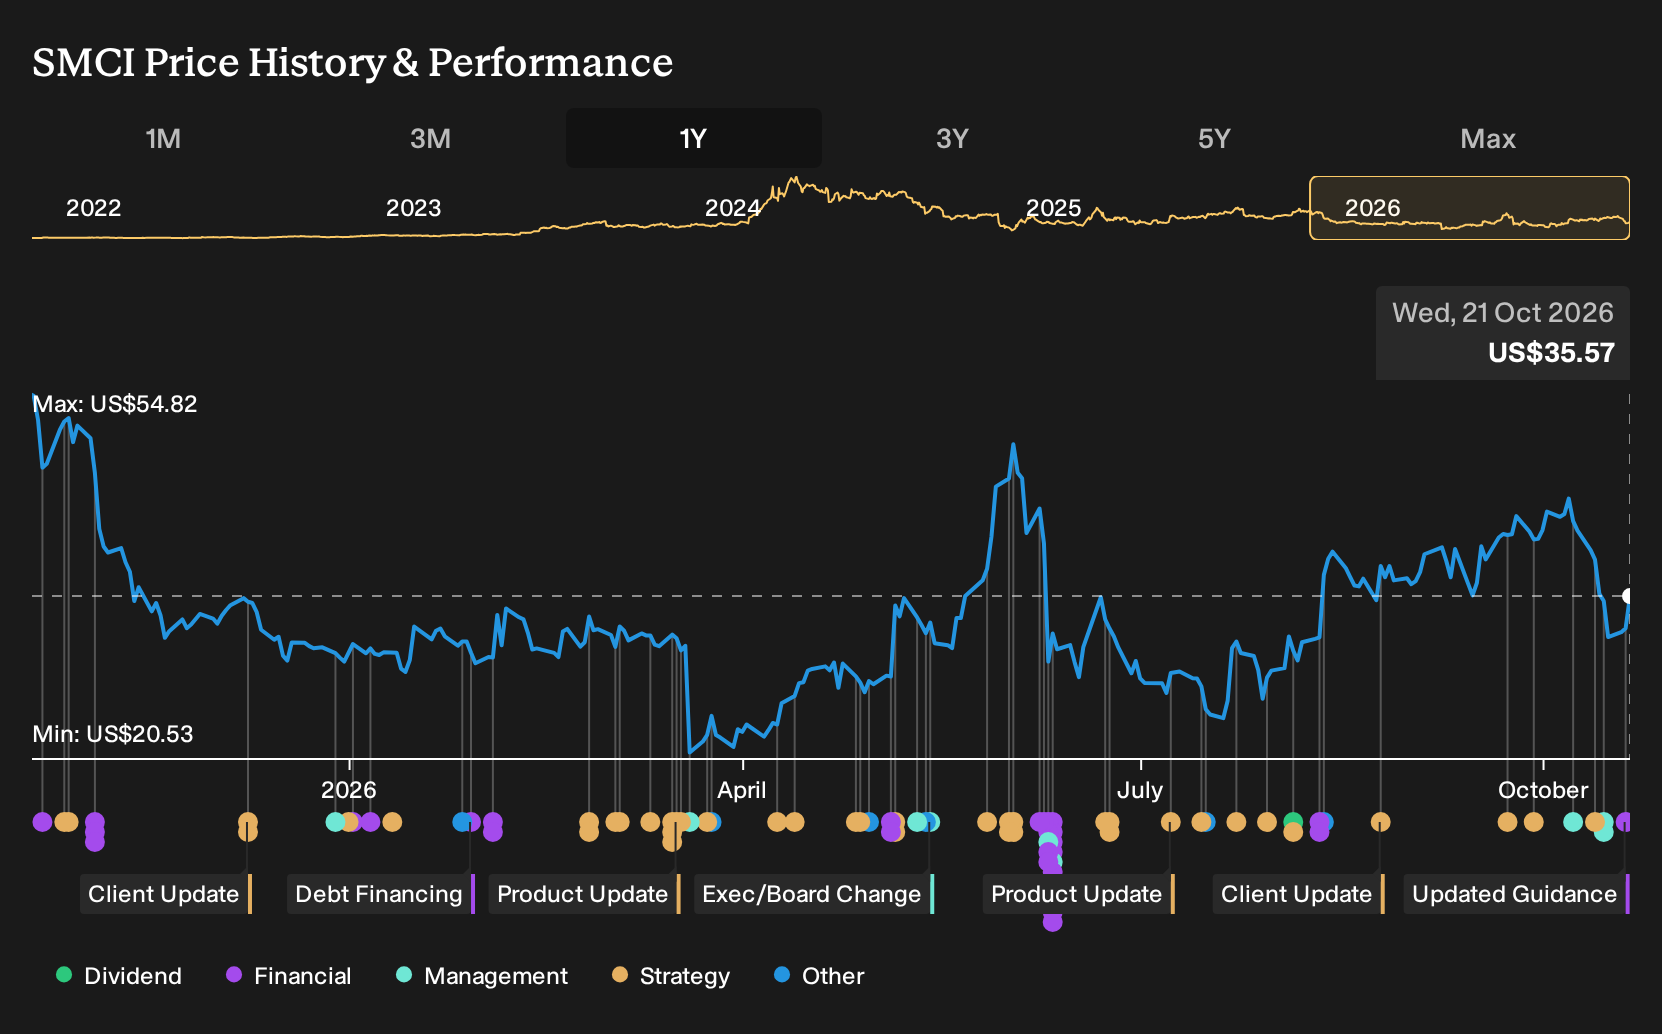
Super Micro Computer (SMCI)
Overview: Super Micro Computer builds high performance, liquid and air cooled AI servers and rack scale systems that let data centers reliably deploy GPU heavy AI workloads.
Operations: Super Micro Computer generates about US$39.1b from high performance server solutions, with roughly US$27.7b earned in the United States and the rest split across Asia, Europe and other regions.
Market Cap: US$21.3b
Super Micro Computer matters for this screener because it sells the AI ready server and rack systems that turn loose chips into working infrastructure for cloud providers and enterprise data centers.
"Customer concentration is extreme. One customer represented roughly 63% of Q2 FY2026 revenue, making the equity highly fragile if that customer slows orders or switches vendors."
The investment story now hinges on whether one quiet shift in future AI system mix and profitability can outweigh that concentration risk.
That concentration question is exactly what the full narrative for Super Micro Computer tackles, showing how Super Micro Computer could turn a fragile customer mix into accelerating leverage if AI system demand broadens.
Penguin Solutions (PENG)
Overview: Penguin Solutions designs and runs AI focused data center infrastructure and supplies SMART Modular memory, storage, and CXL expansion hardware that feeds semiconductor driven AI systems.
Market Cap: US$2.9b
Penguin Solutions plugs directly into the Semiconductor Supply Chain theme because its SMART Modular memory and CXL products help AI chips access the capacity and bandwidth they need inside real world data centers.
"Accelerating adoption of AI and high-performance computing across major enterprise verticals (financial services, energy, biotech, federal, and neo-cloud providers) is driving robust demand for turnkey compute infrastructure, as evidenced by rising customer bookings and a diversified pipeline; this is likely to support sustained growth in revenue."
What ultimately matters for investors is how one unresolved pressure on future margins interacts with that demand to shape long term earnings power.
That margin pressure is exactly what the full narrative for Penguin Solutions breaks open, separating short term cost noise from the areas where Penguin Solutions’ AI earnings potential could realistically accelerate next.

Seeking Fresh Alternatives Before They Fly
Markets move fast and the sharpest opportunities rarely stay under the radar for long. Screen fresh ideas with real momentum before the crowd catches up and act now.
- Target sturdier cash flows and tighter balance sheets by running the list of solid balance sheet and fundamentals (25 results), which highlights financially resilient businesses when conditions get choppy.
- Chase early upside in smaller AI players using the curated 38 profitable AI stocks that aren't just burning cash, built to surface real earnings power instead of hype burners.
- Position ahead of the energy build out by scanning the hand picked 42 power grid technology and infrastructure stocks, focused on companies tied to grid upgrades and electrification demand.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com