
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is CTS (CTS) Undervalued As The EPA Settlement Reshapes Regulatory Risk?
EPA settlement puts CTS stock in focus
The U.S. Environmental Protection Agency proposed a $7.6 million settlement with CTS (CTS) tied to cleanup at the CTS of Asheville Superfund Site, sharpening investor attention on environmental liabilities and regulatory exposure.
CTS shares trade at US$56.23, with recent trading showing short term pressure as the 30 day share price return declined 4.2% and the 90 day move fell 7.7%. However, momentum over the year looks firmer, with a 28.2% year to date share price gain and a 37.6% 1 year total shareholder return, hinting that investors have been reassessing both growth prospects and environmental risk as the EPA case edges toward resolution.
Scan past CTS to compare how other companies handle regulatory and balance sheet risk with our curated 31 resilient stocks with low risk scores list.
CTS trades at US$56.23 while analyst and intrinsic value estimates sit meaningfully higher, and the recent pullback widens that gap. Is the stock still cheap once the EPA settlement is fully priced in?
Most Popular Narrative: 20% Undervalued
On the widely followed CTS narrative, the fair value sits at $70.67 against a last close of $56.23. This puts the EPA settlement into a broader pricing gap that investors now have to judge for themselves.
The company's continued diversification into high growth end markets such as medical, industrial, and aerospace and defense, now reflected in diversified end markets contributing 59% of revenue and growing faster than transportation, supports the case that CTS can keep lifting revenue and sustaining higher gross margins.
Structural increases in automation, device connectivity, and industrial digitalization, evidenced by industrial sales of US$40 million in Q2 2026 with a book to bill of 1.11, position CTS's sensing and control products to capture additional orders that can add to revenue and EBITDA over time.
See why 3 investors see CTS as 20% undervalued.
Result: Fair Value of $70.67 (UNDERVALUED)
Still, the CTS story can be knocked off course if transportation softness lingers or if input cost and tariff pressures squeeze those recently strong margins.
Find out about the key risks to this CTS narrative.
Another View: CTS on earnings multiples
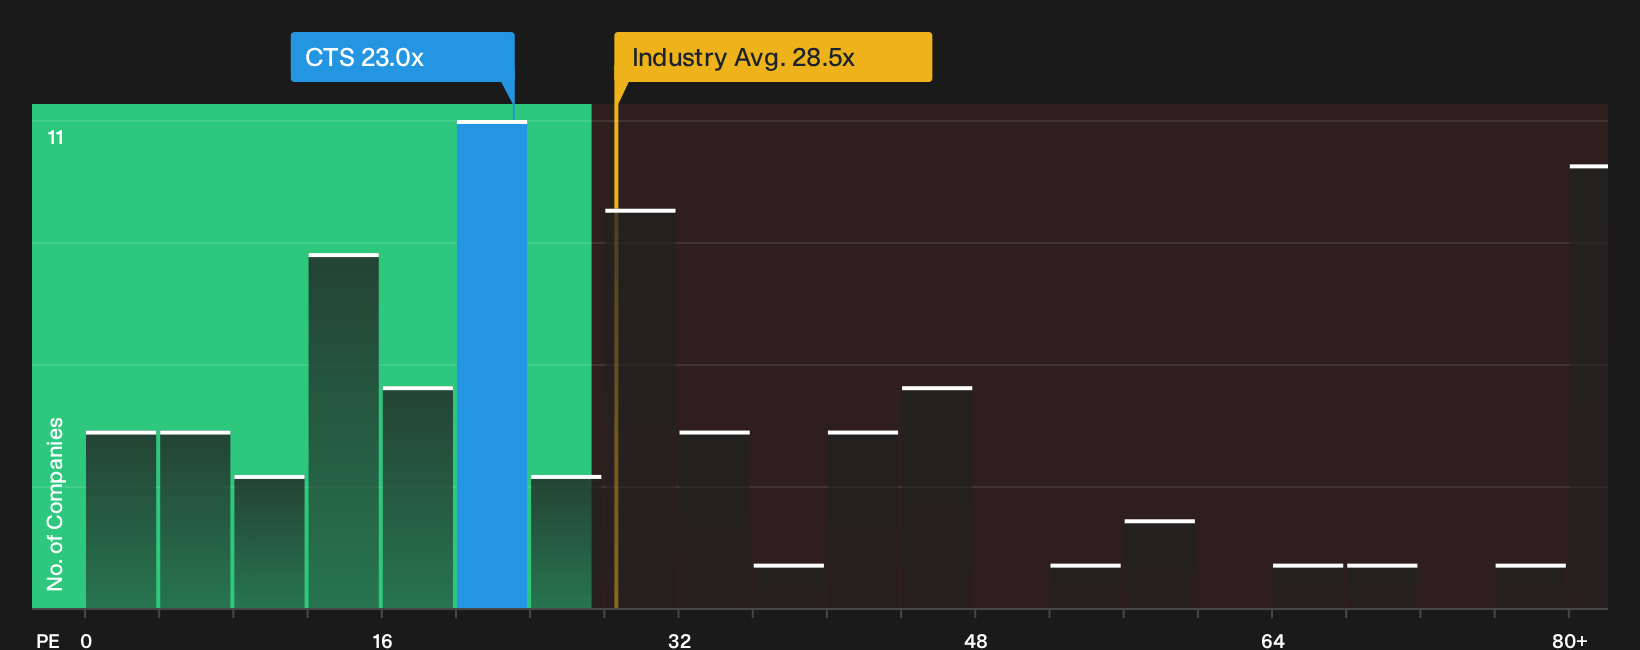
On a different yardstick, CTS trades on a P/E of about 23x compared with a fair ratio of 21.1x and an industry average of 28.6x. That leaves the stock cheaper than sector peers, yet a bit rich versus its own fair ratio, which raises a simple question for investors. Is that extra premium justified by the story you believe most?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views like these only matter if you put CTS in your own framework and act while the information is still fresh. To see what optimism is grounded in and pressure test those potential upsides, start with the 4 key rewards
Looking for more investment ideas beyond CTS?
Do not stop your research with CTS. Fresh opportunities often show up where pricing, balance sheet strength, and income profiles line up more cleanly.
Use the Simply Wall Street Screener to widen your opportunity set without losing discipline.
- Target potential bargains by filtering for companies that combine quality fundamentals with attractive pricing through the 33 high quality undervalued stocks.
- Prioritise resilience by focusing on businesses with stronger financial positions using the list of solid balance sheet and fundamentals (25 results).
- Build a watchlist of potential future income streams by screening for higher yielding payers via the 7 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com