
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Marvell Technology (MRVL) Rides The AI Chip Rally As Valuation Debate Heats Up
Marvell Technology (MRVL) has been caught up in the latest rally in semiconductor stocks, as investors respond to strong demand for AI hardware and upbeat earnings across the chip sector. Fresh enthusiasm reflects confidence in AI-focused infrastructure suppliers.
Over the past year, Marvell Technology has moved from being just another chip stock to a key AI infrastructure play. This shows up clearly in its 173.81% year to date share price return and very large 3 year total shareholder return of 419.07%, as investors weigh rich expectations against occasional pullbacks tied to sector wide AI sentiment and funding worries.
Scan the AI infrastructure space beyond Marvell Technology by jumping straight to our hand-picked 55 AI infrastructure stocks to see which other chip players are benefiting from the same spending trend.
Bulls point to Marvell Technology’s AI contracts, revenue growth and product pipeline, while bears focus on premium multiples and sector swings. The next step is to test which side current valuation and fundamentals lean toward.
Most Popular Narrative: 28% Undervalued
Marvell Technology’s most followed valuation story pegs fair value at $339.36, well above the last close at $244.76, which puts a lot of weight on its AI data infrastructure roadmap and execution.
The main thing that has to go right is that Marvell converts its expanding AI networking, optics and custom XPU pipeline, including large hyperscaler programs and capacity prepayments, into the guided data center and custom revenue growth while sustaining its target non GAAP operating margin range.
The numbers and current valuation together suggest that the share price already reflects a bullish view that Marvell is fairly valued based on expectations of strong long term AI and data infrastructure demand, together with non GAAP operating margins moving into the high end of the 38% to 40% target range.
See why 337 investors see Marvell Technology as 28% undervalued.
Result: Fair Value of $339.36 (UNDERVALUED)
Still, the story can break if AI hardware spending from hyperscalers slows, or if Marvell Technology’s lower margin custom programs drag on profitability.
Find out about the key risks to this Marvell Technology narrative.
Another View: What Multiples Say About Marvell Technology
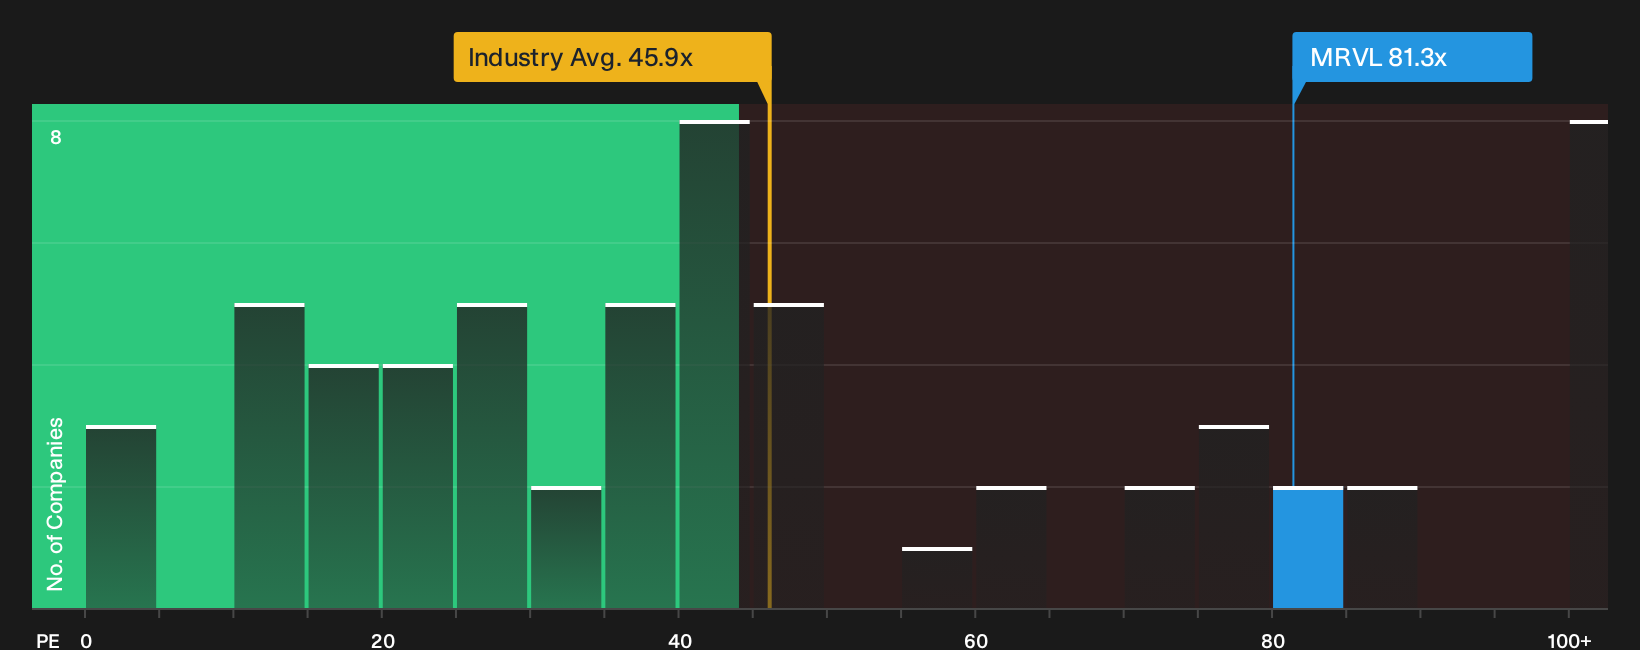
The SWS DCF model points to Marvell Technology trading at a discount to estimated future cash flows, yet the market is still paying a rich P/E of 81.3x versus a fair ratio of 59.7x and a US Semiconductor peer average of 45.9x. That kind of gap can reward patience or punish it if expectations reset, so which outcome feels more realistic to you?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Big swings in sentiment around Marvell Technology only matter if you understand what is driving them. Move quickly, review the full picture of both risks and potential upsides, and weigh the 3 key rewards and 2 important warning signs.
Looking for more ideas beyond Marvell Technology?
Do not stop at Marvell Technology alone. Broaden your watchlist with other clear setups and give yourself more options when sentiment shifts again.
- Target resilient compounding potential by reviewing companies in the 31 resilient stocks with low risk scores that aim to balance upside with reduced downside pressure.
- Hunt for mispriced quality by scanning the 21 high quality undiscovered gems before broader attention chases the same opportunities.
- Anchor your portfolio with sturdier finances by focusing on the list of solid balance sheet and fundamentals (25 results) so short term volatility does not derail your long term plan.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com