
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
USA Rare Earth (USAR) Stock Still Looks Undervalued Following A 58% Slide
USA Rare Earth has been caught in a rare earth sector selloff at the same time as it secures major government backing, which puts a spotlight on a simple question for investors who care about balance sheets. Is the current share price giving you a fair deal relative to the assets on its books?
- The stock has fallen 58.2% over the past year, which puts pressure on the case for what that drawdown implies about the value of USA Rare Earth's underlying net assets.
- Access to up to US$1.6b in public funding, including grants and senior secured loan capacity tied to its Stillwater magnet plant, can reshape how investors think about future capital intensity and the payoff from the company’s asset base.
- The analysts covering USA Rare Earth have run their own numbers. See what analysts think USA Rare Earth's shares could be worth.
The issue now is whether USA Rare Earth's current market value is in line with its book value when compared with the industry average.
If you want to test the same book value question beyond USA Rare Earth, compare it with a wider group of 33 best rare earth metal stocks.
Does USA Rare Earth Look Undervalued on Book Value?
P/B fits USA Rare Earth because the business is still building out its operations and its asset base is front and center in the investment case.
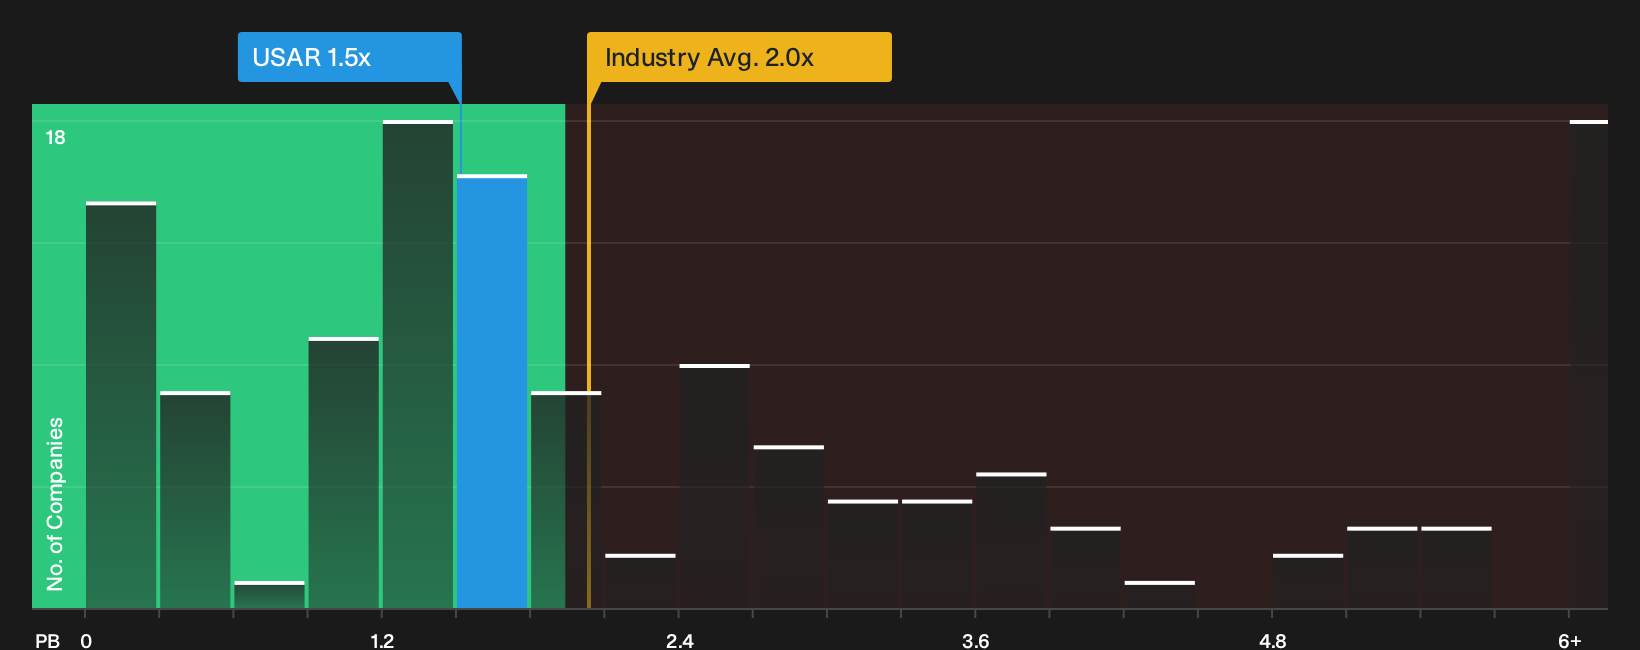
On this yardstick, USA Rare Earth trades at about 1.5x P/B compared with a Metals and Mining sector average of roughly 2.0x and a peer group closer to 4.4x. That gap points to the stock pricing below the value investors are assigning to book equity elsewhere in the industry, which suggests an undervalued reading on this single metric.
Because recent funding agreements have brought up to US$1.6b of public support into focus, the current 1.5x P/B still leaves the shares changing hands at a discount to both the broader sector and rare earth peers. This kind of multiple usually invites investors to weigh how solid the reported assets are and how quickly those assets might convert into productive capacity relative to other producers. Explore the numbers behind USA Rare Earth's P/B valuation.
The USA Rare Earth Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/B debate for USA Rare Earth leaves off and spell out, in plain terms, what growth, margin and earnings paths would need to play out for the shares to look meaningfully cheaper or more expensive than they do today. Instead of stopping at a single ratio output, they unpack the future that number rests on so you can follow whether those conditions actually show up, and they sit on Simply Wall St's Community page.
Community views on USA Rare Earth are divided between investors who see a vertically integrated rare earth chain taking shape and others who focus on early stage execution risk.
Bull case: 71% undervalued
"Bullish analysts highlight USA Rare Earth’s plan for a fully vertically integrated mine to magnet platform. They see this as a key driver for potential value creation…"
Discover why this Narrative puts USA Rare Earth at 71% undervalued.
Bear case: 3000% overvalued
"More cautious analysts focus on execution risk, especially as USA Rare Earth moves from deal completion to integrating Serra Verde and ramping operations…"
Explore why this Narrative puts USA Rare Earth at 3000% overvalued.
USA Rare Earth’s price is only one piece of the puzzle
Balance sheet ratios tell you what USA Rare Earth looks like today, but analyst projections sketch where the business might be in a few years and how that lines up with the current market tag. Explore where analysts expect USA Rare Earth to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com