
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is KLA (KLAC) Stock Too Expensive After AI Spending Fears?
KLA Corporation has been a powerful wealth creator over the past few years, yet the stock has recently come under pressure as investors reassess what its earnings are really worth. With chip equipment names under scrutiny, the key issue is whether the current share price still lines up with what the business earns today.
- Over the past 5 years, KLA has returned about 404%, which puts a lot of expectation on the company to justify that kind of gain through its earnings power.
- Recent coverage has highlighted KLA’s role in zero-tolerance defect environments. This can support arguments for more durable demand and potentially stronger earnings quality than a typical semiconductor equipment supplier.
- There is a second opinion on KLA worth weighing. See what analysts think KLA's shares could be worth.
The issue now is whether KLA's present valuation is adequately supported by its earnings when you compare the stock to the Fair Ratio benchmark.
If you want a wider lens on stocks being assessed through a similar earnings lens, a focused screener of 33 high quality undervalued stocks can be a useful next step in your research.
Is KLA Getting Expensive on Earnings?
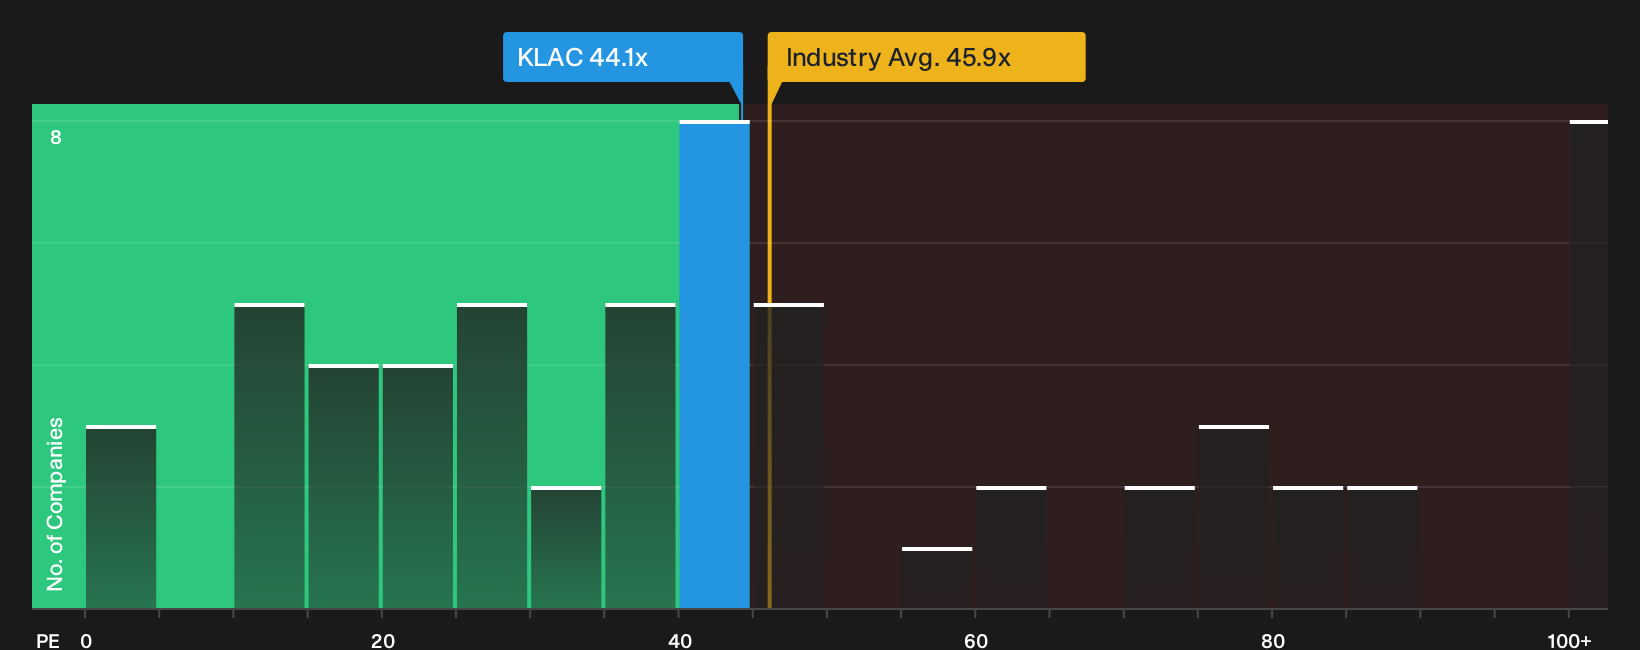
P/E works well for KLA because earnings remain a key yardstick for how investors are valuing its chip inspection franchise today. The stock trades on a P/E of 44.1x, which is slightly above the Semiconductor industry average of 45.9x and also higher than the peer group at 42.5x. On this framework, the Fair Ratio model, which blends factors like profitability, size and risk, suggests a lower multiple would be more in line with the firm’s characteristics, so the current P/E screens as overvalued.
Recent concern about AI equipment spending has pushed chip equipment stocks under pressure. Yet KLA still carries a premium P/E tag relative to peers and the Fair Ratio benchmark. For anyone assessing the shares today, the key question is whether the quality of KLA’s earnings and its role in zero tolerance defect environments justify paying that kind of markup on each dollar of profit. Explore the numbers behind KLA's P/E valuation.
The KLA Narrative: What Would Justify Today's Price?
Narratives for KLA pick up where the valuation puzzle leaves off by spelling out which paths for growth, margins and earnings would need to play out for the stock to be worth meaningfully more or less than today. Instead of a single output from a ratio or model, they describe the future those numbers assume, so you can watch how KLA's actual progress compares with the scenario you are effectively paying for. Narratives sit on Simply Wall St's Community page and give that context in story form rather than as one abstract multiple.
One of the top community narratives on KLA: 30% undervalued
"The main thing that has to go right is that KLA continues to convert its large, long dated backlog and process control share gains…"
Discover why this Narrative puts KLA at 30% undervalued.
An unresolved piece of the KLA puzzle
Valuation only tells you what investors are paying for KLA today, not who is steering the ship or how their pay shapes the decisions that drive those numbers. See who runs KLA and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com