
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
PDD Holdings (PDD) Stock Still Looks Undervalued At Today’s Price
PDD Holdings has seen its share price struggle over the past year, and that slide puts a sharper spotlight on whether the current market value lines up with what the business earns. With fresh scrutiny on Temu and data practices, the key issue for readers is how much of that news is already reflected in the earnings that underpin the stock.
- The share price has fallen 39.5% over the past year, which raises the question of whether recent weakness already reflects the earnings power investors expect from PDD Holdings.
- Regulatory actions tied to Temu's data privacy and product safety, including a Texas settlement and a new lawsuit in Missouri, can influence future compliance costs and ultimately the portion of earnings that flows through to shareholders.
- Your read on PDD Holdings is one view; the desks covering it have another. See what analysts think PDD Holdings's shares could be worth.
The issue now is whether the earnings that support PDD Holdings today are enough to justify the current share price.
If you want to weigh the same earnings question across a wider field than just PDD Holdings, scan through 33 high quality undervalued stocks.
Is PDD Holdings Still Cheap on Earnings?
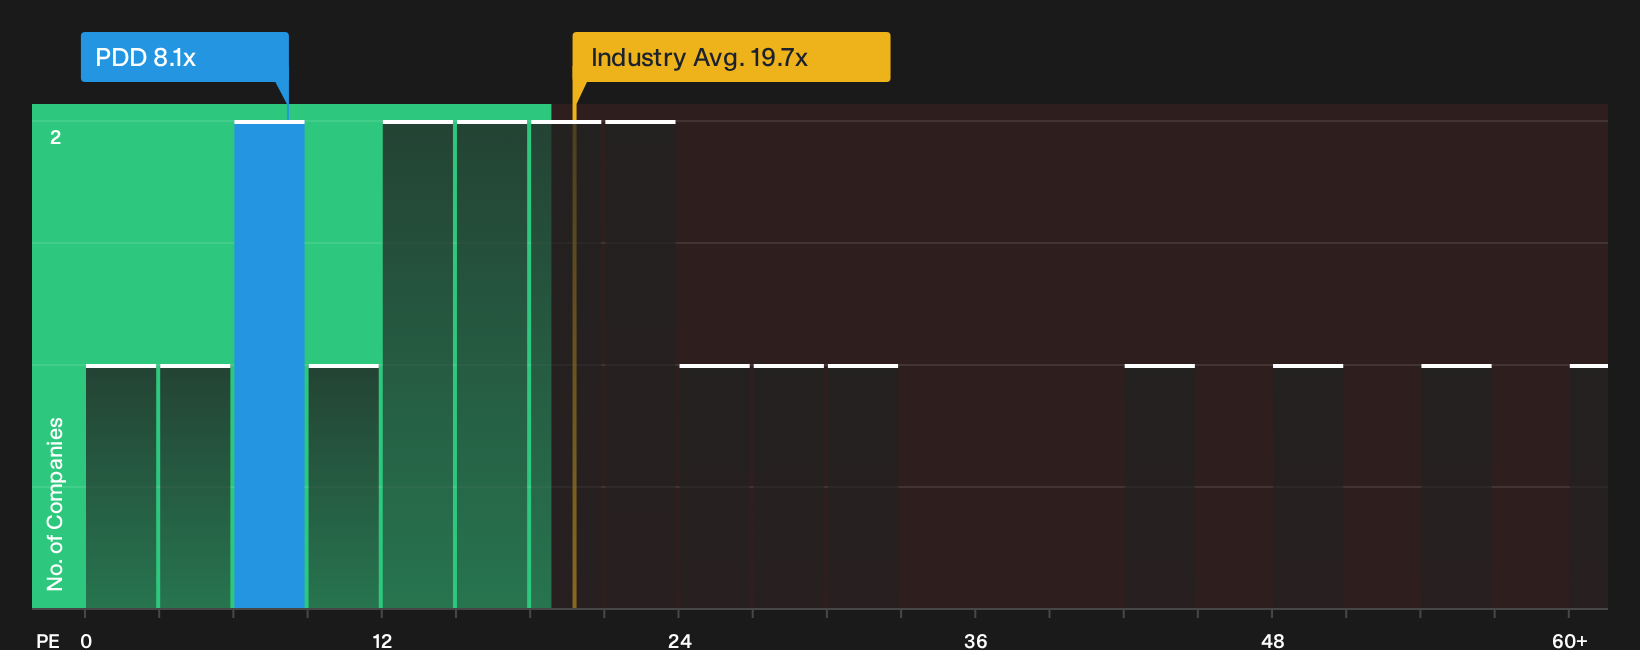
P/E tends to suit PDD Holdings because earnings remain the main reference point investors reach for when they look past short term headlines. The stock trades on a P/E of about 8.1x, which is well below the Multiline Retail industry average of roughly 19.7x and far under the peer group near 32.0x. Given the Fair Ratio here reflects what would usually be expected once growth, margins, scale and risk are all considered together, the current P/E sits on the low side of that yardstick and points to an undervalued earnings tag.
Because the Texas settlement and the fresh Missouri lawsuit keep data privacy and compliance risks front of mind, this discount suggests the market is already assigning a cautious lens to PDD Holdings even before any longer term earnings impact becomes clear. The gap between what the business currently earns and the multiple investors are willing to pay invites a closer look at whether the concerns priced in match your own risk tolerance. Explore the numbers behind PDD Holdings's P/E valuation.
The PDD Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for PDD Holdings leaves off by explaining what kind of future growth, earnings and margins would need to take shape for the stock to appear meaningfully cheaper or more expensive than it does today. Each scenario connects a fair value view to a clear story about PDD Holdings' potential catalysts and key risks, so you can track over time which version of events is closest to reality on the Community page.
One of the top community narratives on PDD Holdings: 31% undervalued
"The main thing that has to go right is that PDD Holdings converts its multi year supply chain, first party brand and rural logistics investments…"
Discover why this Narrative puts PDD Holdings at 31% undervalued.
One more angle on PDD Holdings that could change how you see this valuation
Everything so far has focused on what PDD Holdings earns today, but professional analysts have mapped out where they think this business could be a few years from now. This gives you a separate reference point to compare with today's pricing. Explore where analysts expect PDD Holdings to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com