
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Bank of Hawaii (BOH) Stock Looks Hard To Call On Current Earnings
Bank of Hawaii shares have logged a 65.5% return over the past three years, which naturally puts the spotlight on whether the current price still lines up with what its earnings can support. For anyone looking at regional bank exposure, the question now is how much of the recent share performance already reflects the profits this business is generating.
- The 65.5% gain over three years means existing holders have seen meaningful wealth created, so fresh buyers need to think carefully about what level of earnings power they are effectively paying for today.
- The bank’s model is built on recurring interest income and fee-based activity, which can support relatively steady profit streams if funding costs and credit quality remain under control.
- Your read on Bank of Hawaii is one view; the desks covering it have another. See what analysts think Bank of Hawaii's shares could be worth.
The stock’s next move may depend on whether Bank of Hawaii’s current earnings justify paying around US$68.94 per share today.
If you want context for Bank of Hawaii’s recent 65.5% three year return, it can help to compare its earnings driven story with 33 high quality undervalued stocks
Is Bank of Hawaii Fairly Priced on Earnings?
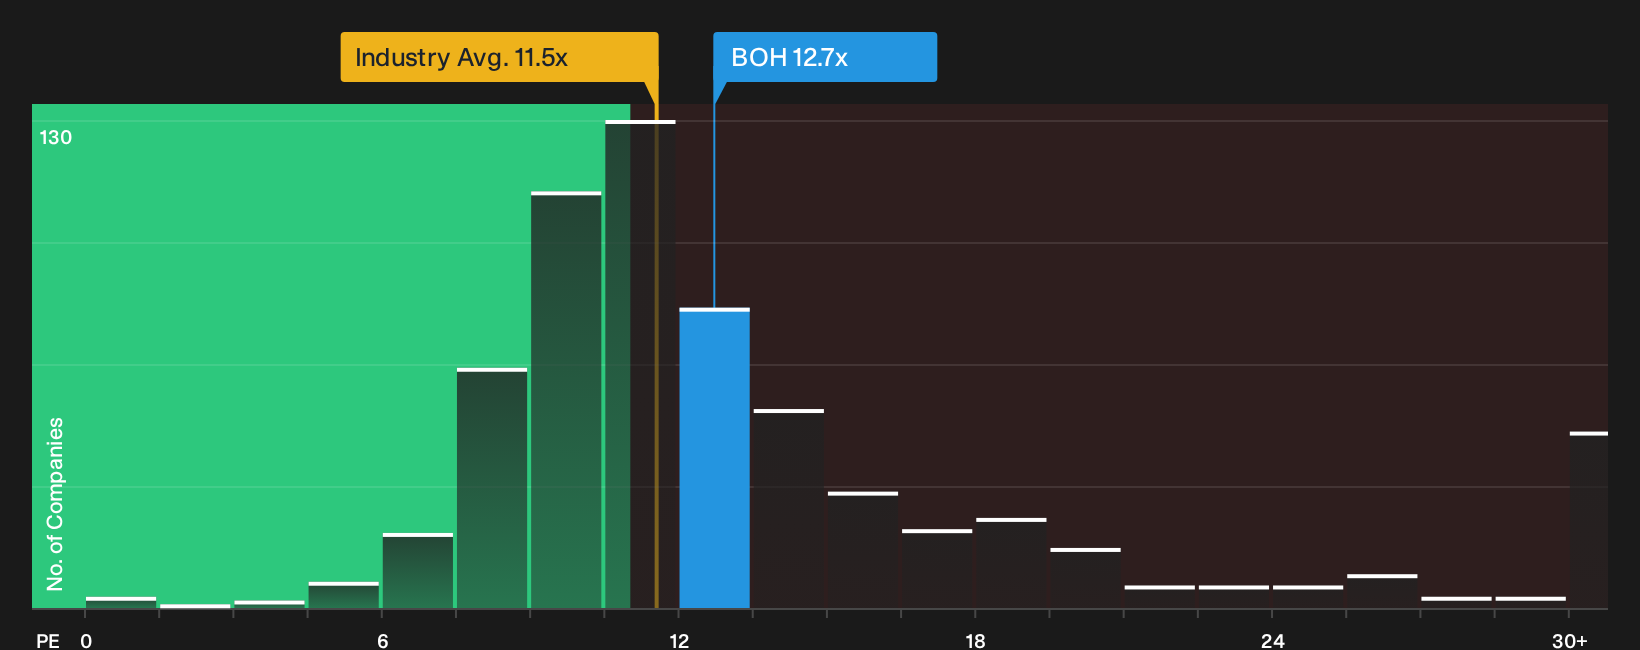
The P/E ratio suits Bank of Hawaii because earnings are the main anchor for how investors usually assess a regional lender. At around 12.7x, the current P/E sits slightly above the wider banks industry average of about 11.5x, yet below the peer group level near 22.1x, which places the stock in the lower half of the broader peer valuation range.
The tailored fair P/E that reflects Bank of Hawaii’s own balance of profitability, growth expectations and risk comes out very close to where the shares trade today, so the current multiple is only marginally above that reference point. That means the price broadly aligns with what this framework suggests the earnings profile can justify, and any decision now hinges more on your view of how stable those profits look from here. Explore the numbers behind Bank of Hawaii's P/E valuation.
The Bank of Hawaii Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Bank of Hawaii valuation puzzle leaves off and explain which future paths for growth, margins and earnings would need to occur for the stock to be worth meaningfully more or less than today’s share price. Instead of stopping at a single output from a ratio or model, they break down the set of business assumptions behind that figure so you can monitor over time whether Bank of Hawaii's actual progress still matches the scenario you are effectively paying for on the Community page.
A clear, number-driven Narrative on Bank of Hawaii gives you a single, written view of what kind of earnings power and risks you think the current P/E is actually pricing in. It forces those assumptions into the open so you can later compare that thesis with how the bank’s growth, margins and execution really unfold.
Share your own Narrative for Bank of Hawaii and set out the assumptions behind your valuation.
The missing piece for Bank of Hawaii is what comes next
Valuation work on Bank of Hawaii shows what the market is paying for its current earnings profile, but brokerage models sketch out a different picture of where profits and balance sheet strength might head from here. Explore where analysts expect Bank of Hawaii to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com