
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
ResMed (RMD) Draws Fresh Focus As New CPAP Mask Launch Tests Its Valuation
New CPAP mask launch puts ResMed in focus
ResMed (RMD) has drawn fresh attention after announcing the U.S. launch of its AirTouch F40 CPAP mask, a fabric based option aimed at improving comfort and long term therapy use.
ResMed’s recent AirTouch F40 launch follows a busy few months in the background, including a US$200 million share repurchase that retired 0.67% of its equity. It comes as the stock shows a 28.3% 90 day share price return, but a 1 year total shareholder return that declined 6.63%, suggesting short term momentum has improved while longer term holders have seen a softer outcome.
See how ResMed compares with other health and medtech players gaining traction by reviewing the hand picked 37 healthcare AI stocks shaping connected care and digital therapy adoption.
The recent rebound and fresh product story put ResMed at about a 3% discount to analyst targets and a far steeper gap to some fair value estimates. Is the market’s caution on this CPAP leader still warranted?
Most Popular Narrative: 41% Overvalued
Against ResMed’s last close at $246.20, the most followed narrative pins fair value at $175, using a 7.51% discount rate and building in FY27 device supply headwinds.
GLP-1 therapies are being framed internally as a once-in-a-generation demand opportunity. However, if broader weight loss adoption or new clinical data leads to fewer patients requiring CPAP, growth in device and mask revenue could fall short of current expectations and pressure earnings.
See why 1 investors see ResMed as 41% overvalued.
Result: Fair Value of $175 (OVERVALUED)
Still, a few things could flip this bearish ResMed narrative, including GLP 1 users sticking with CPAP longer and supply chain productivity protecting margins.
Find out about the key risks to this ResMed narrative.
Another View: ResMed on Earnings Multiples
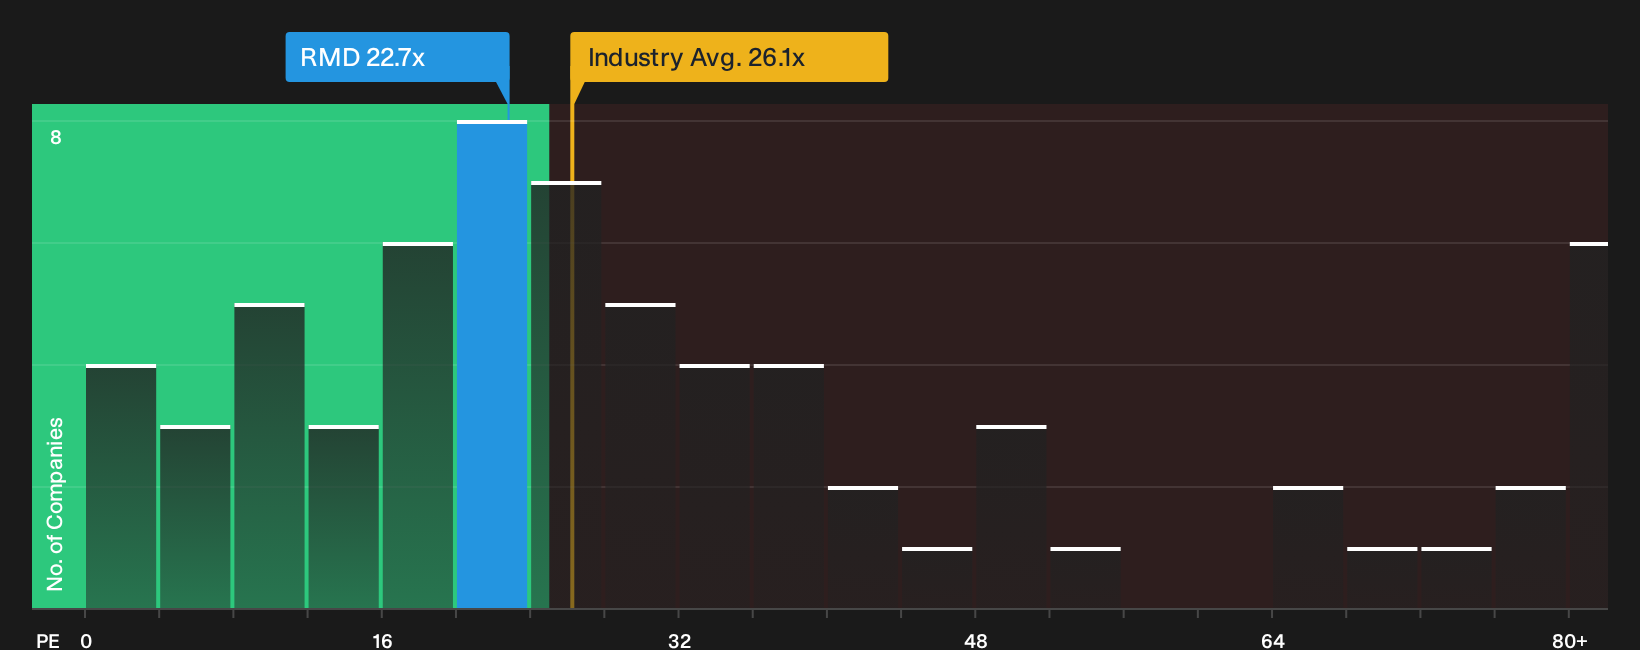
The bearish narrative leans on a lower future P/E of 18x to call ResMed overvalued at $246.20. Current data paints a different picture. The stock trades on a 22.7x P/E compared with a fair ratio of 26.4x, the US Medical Equipment industry at 26.1x, and a peer average of 34.1x.
That gap suggests the market is already pricing in some GLP 1 and FY27 risk, rather than giving ResMed a premium for its 23.1% return on equity and high quality earnings. The real question for investors is whether that discount reflects prudence or an overreaction.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed sentiment on ResMed leaves you unconvinced, move fast and interrogate the numbers yourself before the story shifts again. To see what the market likes about the stock, start by weighing its 4 key rewards
Looking for more investment ideas beyond ResMed?
If ResMed has sharpened your thinking, do not stop here. Broaden your watchlist now and you might catch the next story before the crowd.
- Target potential mispricing by reviewing a curated 33 high quality undervalued stocks that combines solid financial quality with share prices that lag underlying fundamentals.
- Prioritise resilience first and scan a 31 resilient stocks with low risk scores designed to highlight businesses with stronger balance sheets and lower overall risk scores.
- Hunt for tomorrow's standouts by checking a focused 21 high quality undiscovered gems that flags under the radar companies with robust fundamentals already in place.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com