
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Bega Cheese Doubters Missed
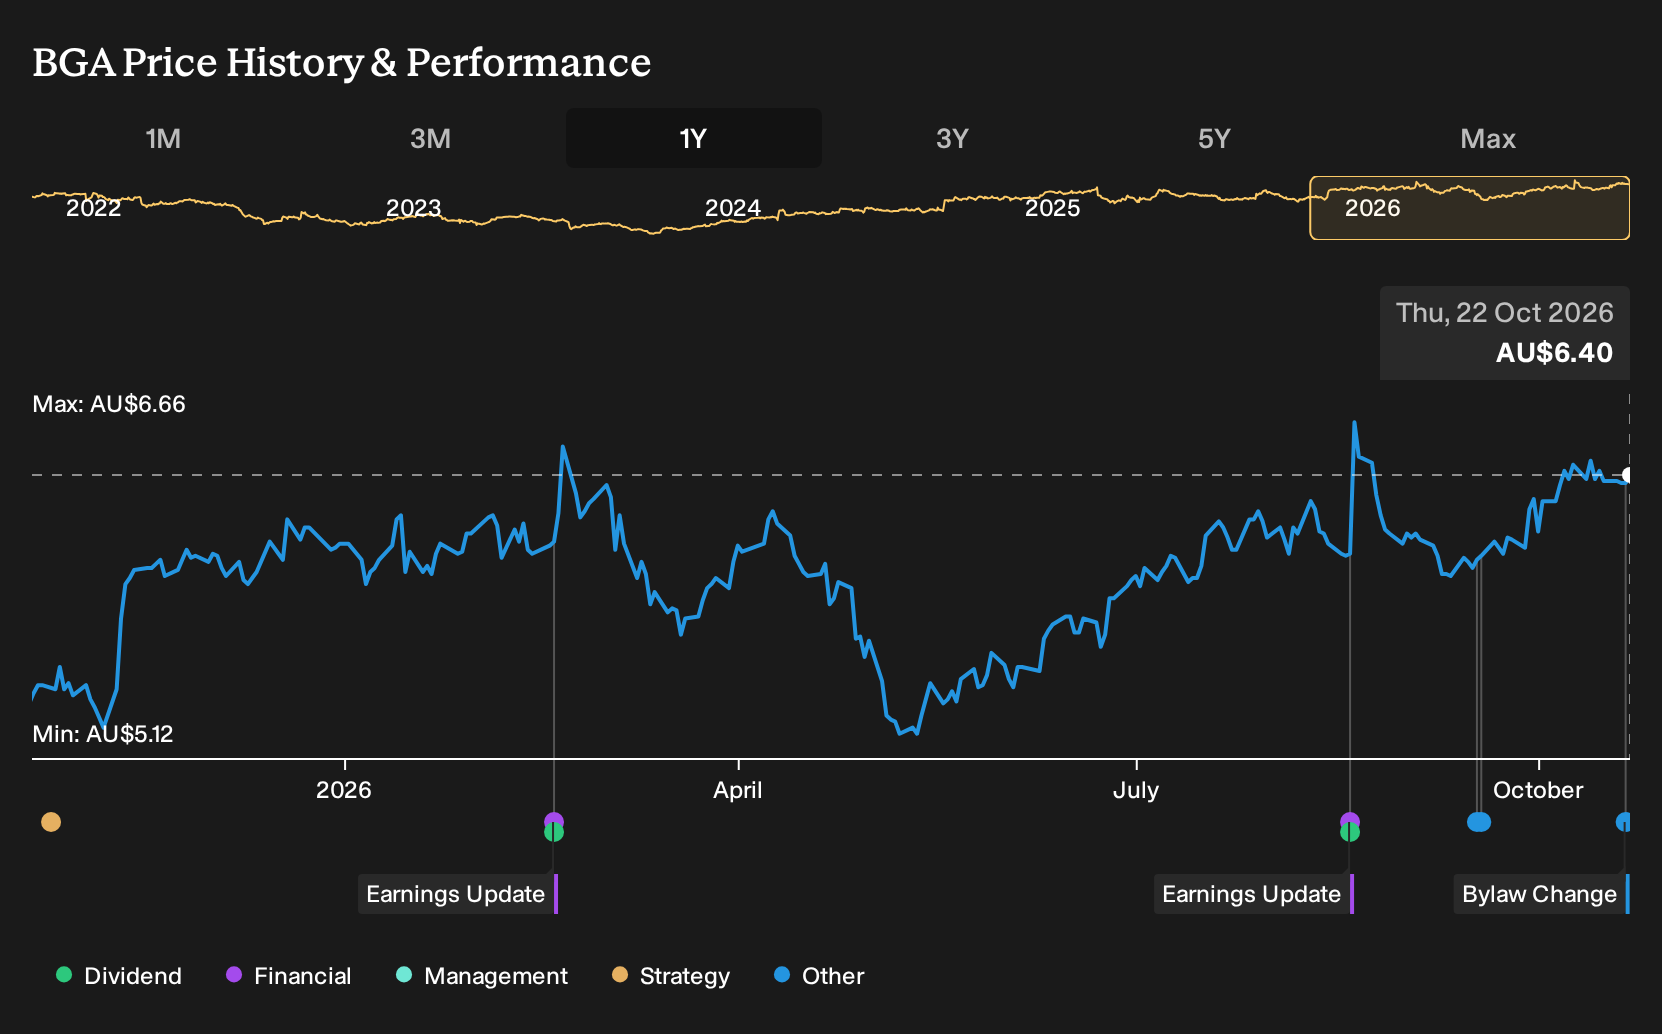
If you had been looking at Bega Cheese on 22 October 2025, you would have seen upbeat targets for higher-margin dairy and Asia-Pacific growth, set against warnings about plant-based competition, retailer power, and restructuring risks. For Bega Cheese shareholders, the return over the past year was 22.2%, including dividends. If you were weighing whether those automation projects and international ambitions were enough to offset dairy headwinds, what exactly were you relying on?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
Bega Cheese has already moved. See which of 4 high quality undervalued stocks still trade below our estimates.
The Two Bega Cheese Stories Investors Had To Weigh
The shares cost A$5.32 at the start of the period, and the live question for anyone looking at Bega Cheese was which story about its future to trust.
The bullish Narrative put Fair Value at A$6.04 and leaned on growth in higher protein and functional dairy products, plus Asia-Pacific expansion that aimed to diversify earnings and lift margins.
The bearish view set Fair Value at A$4.4 and focused on the risk that plant-based adoption, retailer power, and restructuring hurdles would pressure dairy profits and keep returns under strain.
What The Results Changed For The Bega Cheese Thesis
Bega Cheese reported H2 2026 revenue of A$1,903.3m and a return to profit, with net income of A$7.9m after a loss of A$38.7m a year earlier. Net margin moved from a negative 2.2% to a positive 0.4%. That shift supported the optimistic case on margin repair, although profitability remained slim enough that the cautious view on earnings resilience stayed alive.
This episode turned on one assumption: that efficiency moves and product mix would show up in reported earnings. For any other business, track whether margin and profit actually move in the direction the growth story claims rather than relying on revenue or guidance alone.
What Bega Cheese's Price Now Assumes
Bega Cheese now trades at A$6.4 after a 22.2% gain over the past year. The selected Narrative judges its Fair Value to be below that level, with the gap tied less to broad dairy worries and more to how the current expansion and consolidation plan plays out.
On this view, a buyer today is effectively banking on management turning new capacity, cost savings and capital projects into steadier earnings. The question is how the highlighted execution and demand risks affect that payoff.
"The main thing that has to go right is Bega Cheese successfully turning its recent capacity expansions, supply chain consolidation and higher value ingredients focus into sustained, less volatile earnings, despite guidance for lower bulk EBITDA in FY27. The current numbers imply the share price already reflects strong delivery on EBITDA growth, cost savings and balance sheet repair, which leaves limited room if branded growth or international expansion fall short of expectations."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Looking Beyond Bega Cheese
Once you understand Bega Cheese, it helps to look one step sideways.
Your dairy thesis still sits inside a wider packaged food world. Consumers buying cheddar and milk powders also buy snacks and drinks.
The same households want convenience, trusted brands and reliable availability across their baskets.
Another global group has spent years refining that mix, investing heavily in production, marketing and distribution, then sending surplus cash back to shareholders.
The open question is how that scale and brand depth respond if tastes keep drifting toward different ingredients and formats.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 48% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com