
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Winnebago (WGO) Stock Rallies As Q4 Results Meet A Demand Slowdown
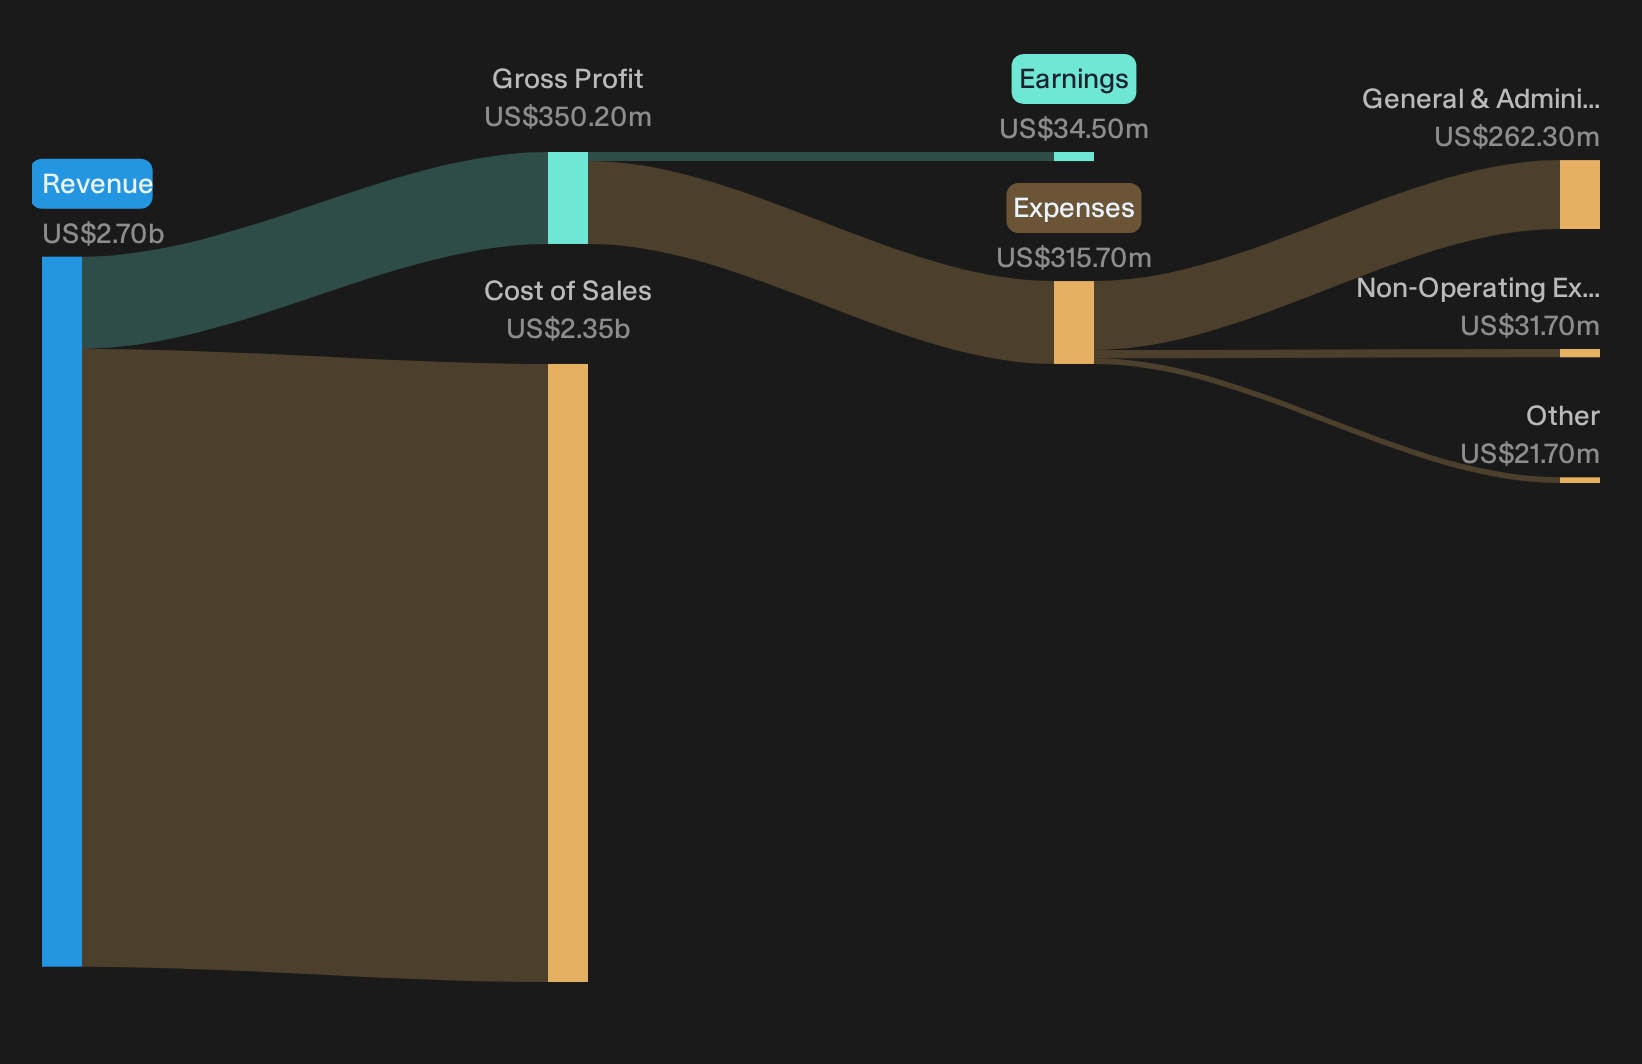
Winnebago Industries just moved sharply higher, with the stock jumping 10.7% after its Q4 2026 report, even though the prior three months had left shares drifting and the 90 day return still down double digits. Traders reacted to a clean headline. Revenue landed at US$645.1 million for the quarter and free cash flow for the full year reached US$144.6 million, while net leverage moved to 2.2x.
Short term chasers see a pop. Long term holders will focus on that mix of cash generation and balance sheet repair against a still premium P/E and a dividend that leans hard on earnings.
Love Winnebago Industries' free cash flow and balance sheet repair but uneasy about paying a still premium P/E for that mix? Screen for companies that combine resilient cash generation with sturdier valuations using our 33 high quality undervalued stocks
Q4 2026 Earnings Summary
- Revenue (Q4 2026 vs. Q4 2025): US$645.1 million vs. US$777.3 million (top line declined 17.0%)
- Net Income (Q4 2026 vs. Q4 2025): US$9.7 million vs. US$13.7 million (profit fell 29.2%)
- Basic EPS (Q4 2026 vs. Q4 2025): US$0.34 per share vs. US$0.49 per share (earnings per share declined 29.9%)
- Net Profit Margin, trailing 12 months (FY 2026 vs. prior year): 1.3% vs. 0.9% (margin widened by 0.4 percentage points)
Ask Charlie what Winnebago’s cost cuts mean for margins next year.
Winnebago margin thesis meets early execution milestones
For bullish investors in Winnebago Industries, the key claim is that mix and cost work can matter more than the RV cycle itself.
"The main thing that has to go right is that Winnebago Industries turns early traction in Grand Design Motorhome, Barletta pontoons, and revitalised Winnebago motorhomes and towables into sustained retail share gains while keeping dealer inventory turns near its 2x goal."
Recent numbers lean in that direction. Enterprise retail unit share is 35.4% with dollar share at 41%, while Grand Design Motorized, Winnebago travel trailers and Barletta all post share gains. Dealer turns have reached 1.8x against the 2x ambition, which shows progress but not completion of the target.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Winnebago bear case: demand drag still bites
The caution around Winnebago Industries hinges on the idea that weak end demand and promotions will blunt all the internal fixes.
"Bearish analysts expect Winnebago Industries to face prolonged RV demand softness and pressured profitability as RV sales trends remain weak and competitive intensity stays elevated."
Fresh numbers largely keep that worry alive. Q4 revenue and adjusted EPS both declined year on year, and FY27 guidance points to mid to high single digit sales declines in Q1 with margins flat to slightly softer. Mix, cost work and lower net leverage to 2.2x are helping, but not yet offsetting volume pressure.
Hunt For Mispriced Cash Generators
Winnebago Industries showed how quickly sentiment can shift when cash flow and expectations meet. The real opportunity is identifying stocks that may be undervalued before expectations change.
- Company 1 - 46% below our estimate - focuses on a large backlog of higher margin mega projects and Indo Pacific military infrastructure work.
- Company 2 - 47% below our estimate - converts a technology heavy project pipeline into data center and modular construction work that keeps capacity tightly utilized.
- Company 3 - 45% below our estimate - scales large format LED display systems as digital signage, transportation projects and youth sports facilities upgrade visual communication.
Those are three of them. See the full list of 33 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com