
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Dycom (DY) Stock May Be Below Fair Value As Earnings Lead The Case
Dycom Industries has given long term holders a powerful ride, yet the recent pullback raises a simple question for you as an investor. Is the current share price still supported by what the business is earning today and what those earnings may reasonably support over time.
- Over the past 5 years the stock has returned roughly 199%, which puts a lot of pressure on the current valuation to be explained by earnings power rather than just price momentum.
- The company’s role as a contractor for telecom and infrastructure buildouts can influence how steadily project work converts into profit, which matters directly for any earnings based yardstick such as the Fair Ratio.
- Your read on Dycom Industries is one view; the desks covering it have another. See what analysts think Dycom Industries's shares could be worth.
For investors, the debate is whether Dycom Industries’ recent share price, after that long run and pullback, lines up with what its earnings suggest you are paying for today.
If you want a clearer yardstick for Dycom Industries’ recent swings, you can compare its earnings-linked profile with a wider set of infrastructure-focused contractors using the 42 power grid technology and infrastructure stocks.
Does Dycom Industries Look Undervalued on Earnings?
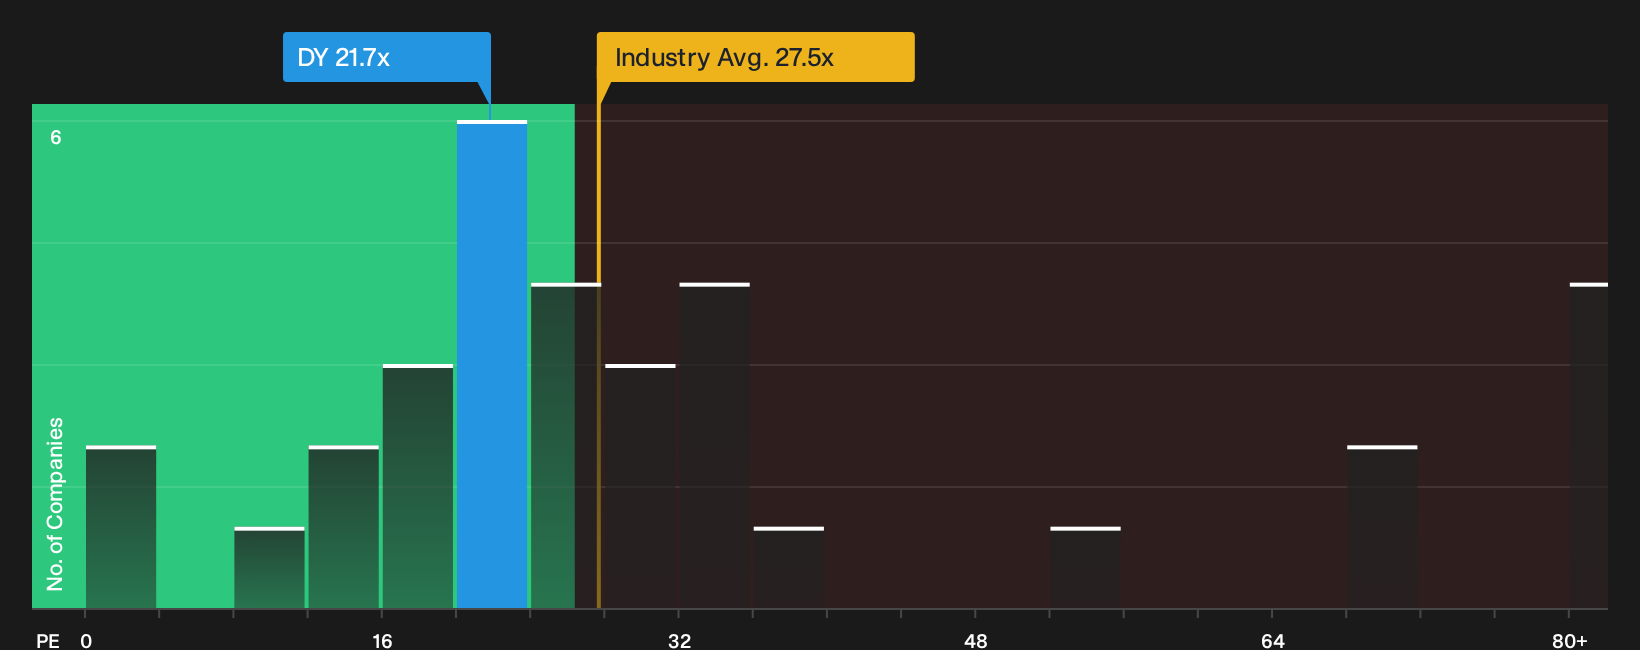
The P/E ratio fits Dycom Industries because earnings are the main lens investors use to judge project contractors that do not pay dividends. On this yardstick, Dycom trades at about 21.7x earnings, which is lower than the Construction industry average of roughly 27.5x and also below the peer group at about 26.0x. For a contractor whose fortunes are tied to telecom and infrastructure rollouts, that gap signals the market is not assigning the same earnings tag as it is to similar businesses.
The Fair Ratio reflects what a more tailored model might expect for Dycom Industries after factoring in its growth outlook, margins, size and risk profile. It sits above the current P/E. That leaves the stock screening as undervalued on this earnings multiple, with the market price implying a lower bar than that reference would suggest. To decide whether that discount is justified, you would still want to test how durable you believe Dycom’s project pipeline and profitability really are. Explore the numbers behind Dycom Industries's P/E valuation.
The Dycom Industries Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Dycom Industries pick up where the valuation puzzle leaves off. They spell out which expectations on growth, margins and earnings would need to hold for the stock to be priced meaningfully higher or lower than it is today, and set out the assumptions behind each fair value view so you can compare them with Dycom Industries' actual results as they appear on the Community page.
One of the top community narratives on Dycom Industries: 62% undervalued
"Rapid growth in fiber to the home activity, including 60% first half revenue growth in that program, suggests Dycom’s national scale…"
Discover why this Narrative puts Dycom Industries at 62% undervalued.
For Dycom Industries, the share price is only half the story
Even for a contractor like Dycom Industries, the people choosing projects, setting priorities and deciding their own rewards can shape how every dollar of earnings is created and shared. See who runs Dycom Industries and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com