
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Helmerich & Payne Buyers Were Betting On
If you had decided on 21 October 2025 to buy Helmerich & Payne after reading that analysts were split between a bullish international automation story and worries about overcapacity and cyclicality, the outcome over the next twelve months would have looked very different from that debate. Holding Helmerich & Payne over the past year would have returned 67.6%, including dividends. If that fork in the road came up again today, which side of the drilling and digitalization argument would deserve more weight?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
Helmerich & Payne has already moved. See which of 33 high quality undervalued stocks still trade below our estimates.
The Argument Helmerich & Payne Investors Were Really Having
The shares cost US$23.32 at the start of the period, and anyone looking at Helmerich & Payne then had to choose between two very different but reasonable stories about where the drilling contractor could go next.
On the bullish side, a Narrative with a Fair Value of US$27 leaned on digital automation and international contracts. It assumed revenue could grow 7.4% a year and that profit margins might move from a loss position to 7.4% by 2028.
The more cautious Narrative put Fair Value at US$21.39. It still saw benefits from digital tools and global expansion, but stressed risks like high exposure to U.S. shale and the chance that overcapacity in rigs could weigh on future margins.
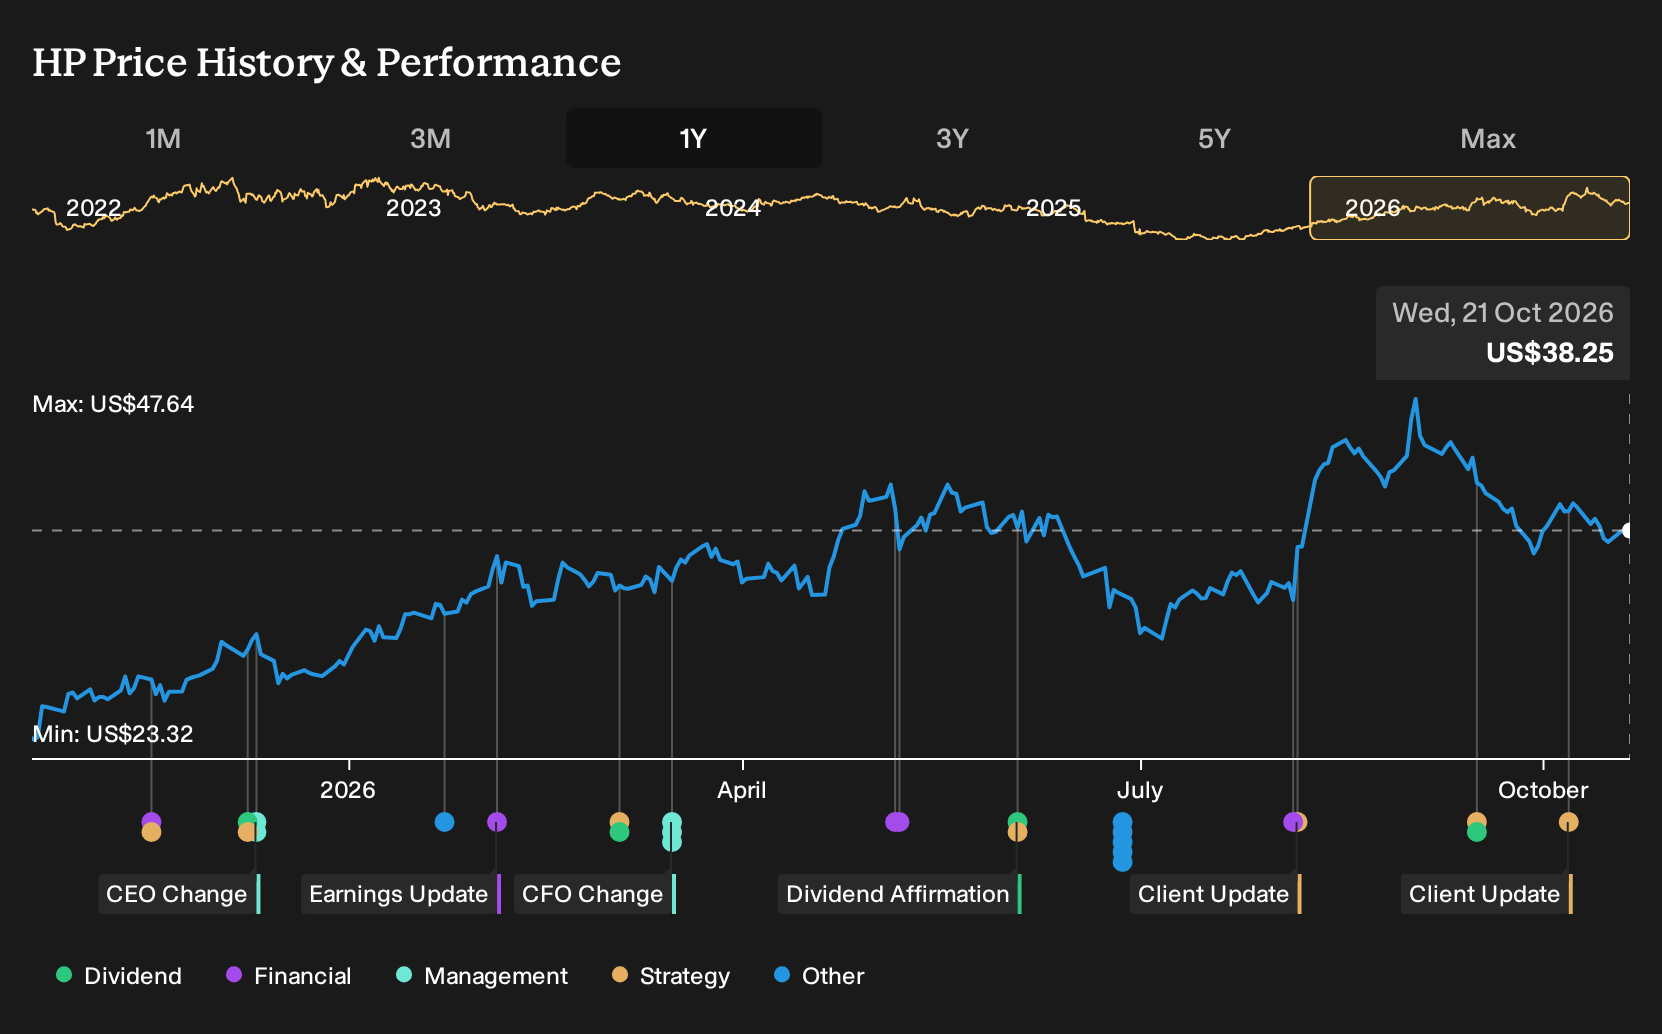
What The Results Changed For Helmerich & Payne
Helmerich & Payne moved from a net loss of US$163.1 million in Q3 2025 to net income of US$74.4 million in Q3 2026, while revenue was slightly lower at US$1.03b. The net margin shift from a decline of 15.7% to a positive 7.2% supported the focus on margin recovery, although softer top line trends kept part of the cautious case alive. Overall, the evidence cut both ways.
The key assumption here was margin power, not just rig count or new regions. When you assess another driller, track whether higher utilization and technology claims actually show up in net margin, even if revenue looks flat.
What Helmerich & Payne's 68% Run Now Asks You To Believe
Helmerich & Payne trades at US$38.25 after a 67.6% gain over the past year, and the selected Narrative now places its Fair Value below that level.
The current Narrative leans on rising cash generation from super spec rigs, offshore backlog and tech driven performance fees, while flagging earnings swings, geopolitical exposure and funding needs. A buyer today effectively assumes those contract wins and tools feed through to steadier margins. The question is how that assumption aligns with the highlighted volatility and tax pressure.
"The current valuation and fairly valued, bullish narrative imply that the share price already reflects a balance between cyclically exposed earnings and the potential rewards from higher rig utilization, multi year offshore and international contracts, and technology driven performance fees. This narrative explores a more pessimistic perspective on Helmerich & Payne compared to the consensus, based on a Fair Value that aligns with the bearish cohort of analysts."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Looking Beyond Helmerich & Payne
Helmerich & Payne pulls your attention toward rigs, contracts and day rates. You could stop there.
Yet the same energy demand also leans on a quieter requirement. Producers still want hydrocarbons, but with lower emissions and tighter methane control.
One global operator is trying to answer that need. It steers money toward lower cost fields, cuts methane leaks and reshapes where low carbon power projects sit.
That mix of traditional output and growing electricity exposure changes the story. You may find the trade off between barrels, electrons and carbon costs worth a closer look.
One Narrative has already put a figure on it. → Uncover the company trading 19% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com