
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Bandwidth (BAND) Stock May Be Pricey After Its 374% Run
Bandwidth has delivered a sharp long term swing in returns, which now raises a straightforward question for you as an investor. Is the current share price properly grounded in what the business generates in sales, or has the stock moved ahead of its own revenue base.
- Over the past 3 years the stock is up about 374%, which puts a lot of weight on whether its sales can shoulder that kind of market enthusiasm.
- Recent share price declines linked to rising yields and a broader tech sell off highlight how quickly investors can reassess what they are willing to pay for each dollar of Bandwidth's revenue when financing conditions tighten.
- There is a second opinion on Bandwidth worth weighing. See what analysts think Bandwidth's shares could be worth.
The issue now is whether Bandwidth's current market value is justified by its sales once you line it up against the Fair Ratio benchmark.
If you want to apply the same valuation question you are asking about Bandwidth to a broader set of companies, take a look at 33 high quality undervalued stocks
Does Bandwidth Look Pricey on Sales?
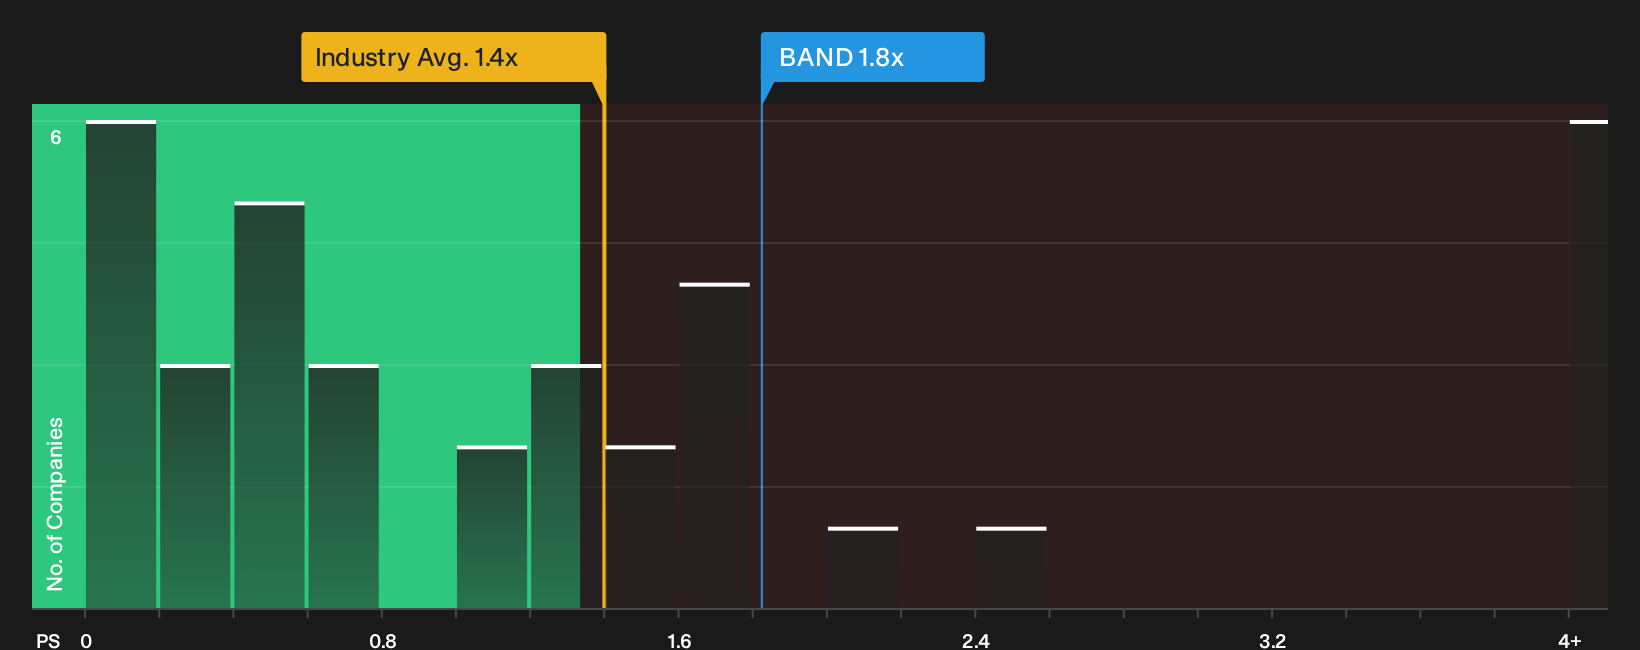
P/S fits Bandwidth because investors are essentially paying for a stream of subscription style communications revenue rather than near term accounting profits. On this metric, the stock trades on a P/S of 1.8x, compared with a Telecom industry average of about 1.4x and a peer group sitting nearer 2.0x. That places Bandwidth at a premium to the wider sector, while still slightly below similar companies that investors track as direct comparables.
Recent share price pressure after the tech sell off has not pulled the valuation down to the level suggested by the Fair Ratio. This implies the current 1.8x still bakes in a richer sales tag than the model would assign given Bandwidth's risk and business profile. For anyone weighing an entry point, the key question is whether the quality and durability of those revenues justify paying above that tailored benchmark and above the broader sector. Explore the numbers behind Bandwidth's P/S valuation.
The Bandwidth Narrative: What Would Justify Today's Price?
For Bandwidth, Simply Wall St Narratives pick up where the valuation puzzle leaves off. They map out what kind of future path for growth, profitability and earnings would need to play out for the share price to sit meaningfully above or below where it trades today. Each narrative links its valuation number to a specific view on how Bandwidth's expansion prospects, margins and risk profile could evolve, giving you something concrete to revisit as fresh information comes through.
One of the top community narratives on Bandwidth: 10% undervalued
"Customer concentration risk remains acute, with Bandwidth heavily reliant on a small set of large clients. Many of these clients may internalize their communications infrastructure…"
Discover why this Narrative puts Bandwidth at 10% undervalued.
One more Bandwidth cross check sits in the forecast column
Price tells you what the market thinks today, while the published projections from covering analysts give you a separate yardstick for where earnings power might be a few years from here. Explore where analysts expect Bandwidth to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com