
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Analog Devices (ADI) Stock Looks Pricey On Digital Power Chip Demand News
Analog Devices has delivered a powerful run in recent years, leaving many holders sitting on sizeable gains. The open question now is whether the current share price is adequately supported by the company’s earnings profile.
- Over the past 3 years, Analog Devices has returned 166.2%, which puts real pressure on the earnings story to keep justifying that kind of share price performance.
- Fresh attention on digital power ICs and demand tied to data centers, 5G networks and electric vehicles can feed expectations for Analog Devices’ profit and cash flow trajectory, which in turn feeds directly into what investors may be willing to pay for its earnings.
- Your read on Analog Devices is one view; the desks covering it have another. See what analysts think Analog Devices's shares could be worth.
The issue now is whether the earnings that Analog Devices generates today, and what investors reasonably expect from them, are enough to support the current valuation.
Alongside checking whether Analog Devices' recent run still lines up with its earnings, you can widen your watchlist with a focused screen of 55 AI infrastructure stocks.
Is Analog Devices Getting Expensive on Earnings?
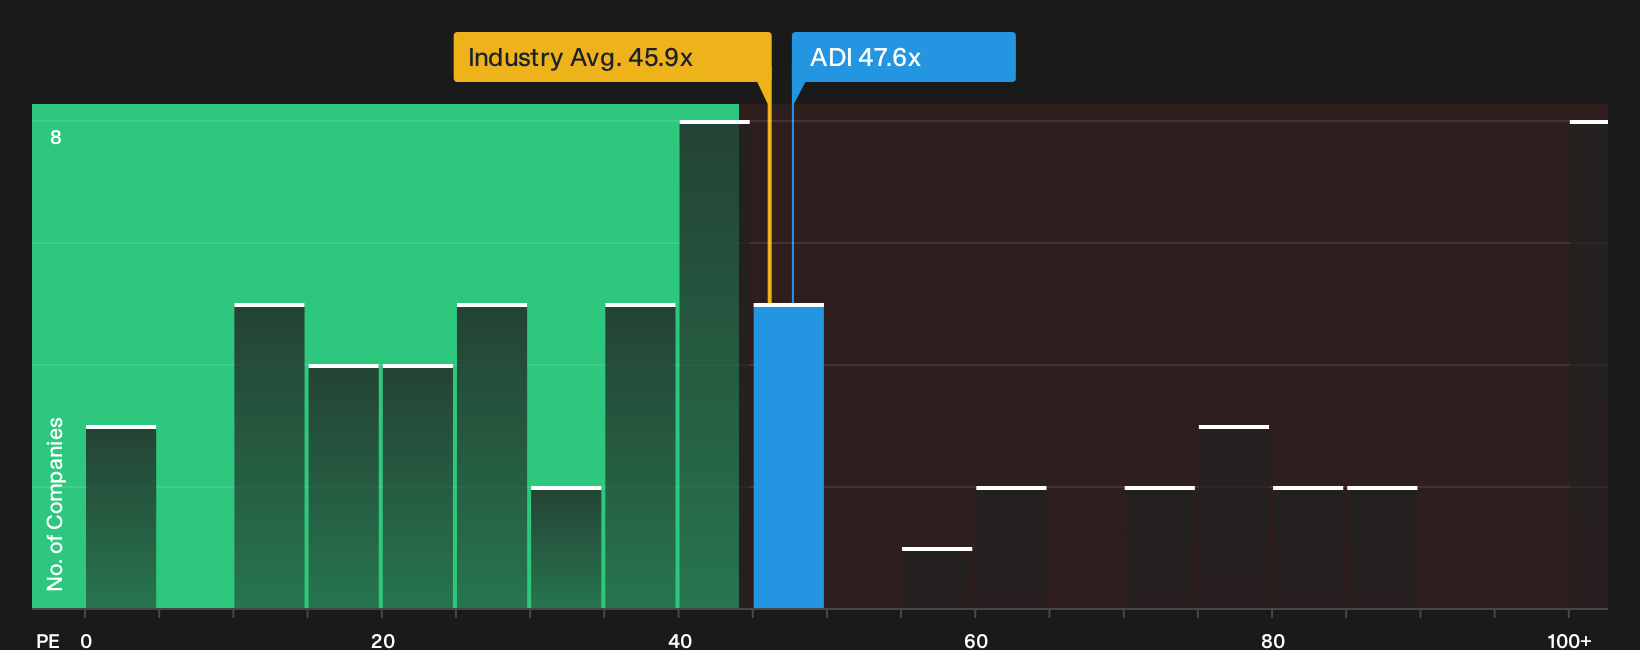
P/E is a useful yardstick for Analog Devices because earnings remain the main anchor for how investors judge mature chip designers. The stock trades on a P/E of 47.6x, which is slightly above the broader semiconductor sector on 45.9x and also above the peer group on 41.4x. Against a tailored fair multiple that adjusts for Analog Devices' size, profitability profile and risk mix, the current P/E screens on the expensive side.
Fresh enthusiasm around digital power IC demand in data centers, 5G and electric vehicles keeps sentiment strong. However, the present P/E already bakes in a generous view of what those themes might mean for earnings. For anyone holding or considering Analog Devices, the key question is whether the current and future profit stream justifies paying a richer multiple than both the sector and a more customised benchmark. Explore the numbers behind Analog Devices's P/E valuation.
The Analog Devices Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Analog Devices pick up where the valuation puzzle leaves off by spelling out what growth, margin and earnings paths would need to hold for the stock to be worth materially more or less than today’s price. Each scenario sets out the assumptions that sit behind its idea of fair value so you can compare those inputs with Analog Devices' actual results as they come through, and they sit on Simply Wall St's Community page.
Community views around Analog Devices split between those who think AI, automotive and industrial demand still leave room in the price and those who see that optimism already reflected in the valuation.
Bull case: 14% undervalued
"Ongoing industrial and mass market recovery, with industrial at 49% of Q3 2026 revenue and up strongly across automation, energy infrastructure, aerospace and defense..."
Discover why this Narrative puts Analog Devices at 14% undervalued.
Bear case: 10% overvalued
"At least one external analysis that values Analog Devices around US$228 per share on a discounted cash flow basis, compared with a market price near US$389..."
Explore why this Narrative puts Analog Devices at 10% overvalued.
One more piece of the Analog Devices puzzle to check
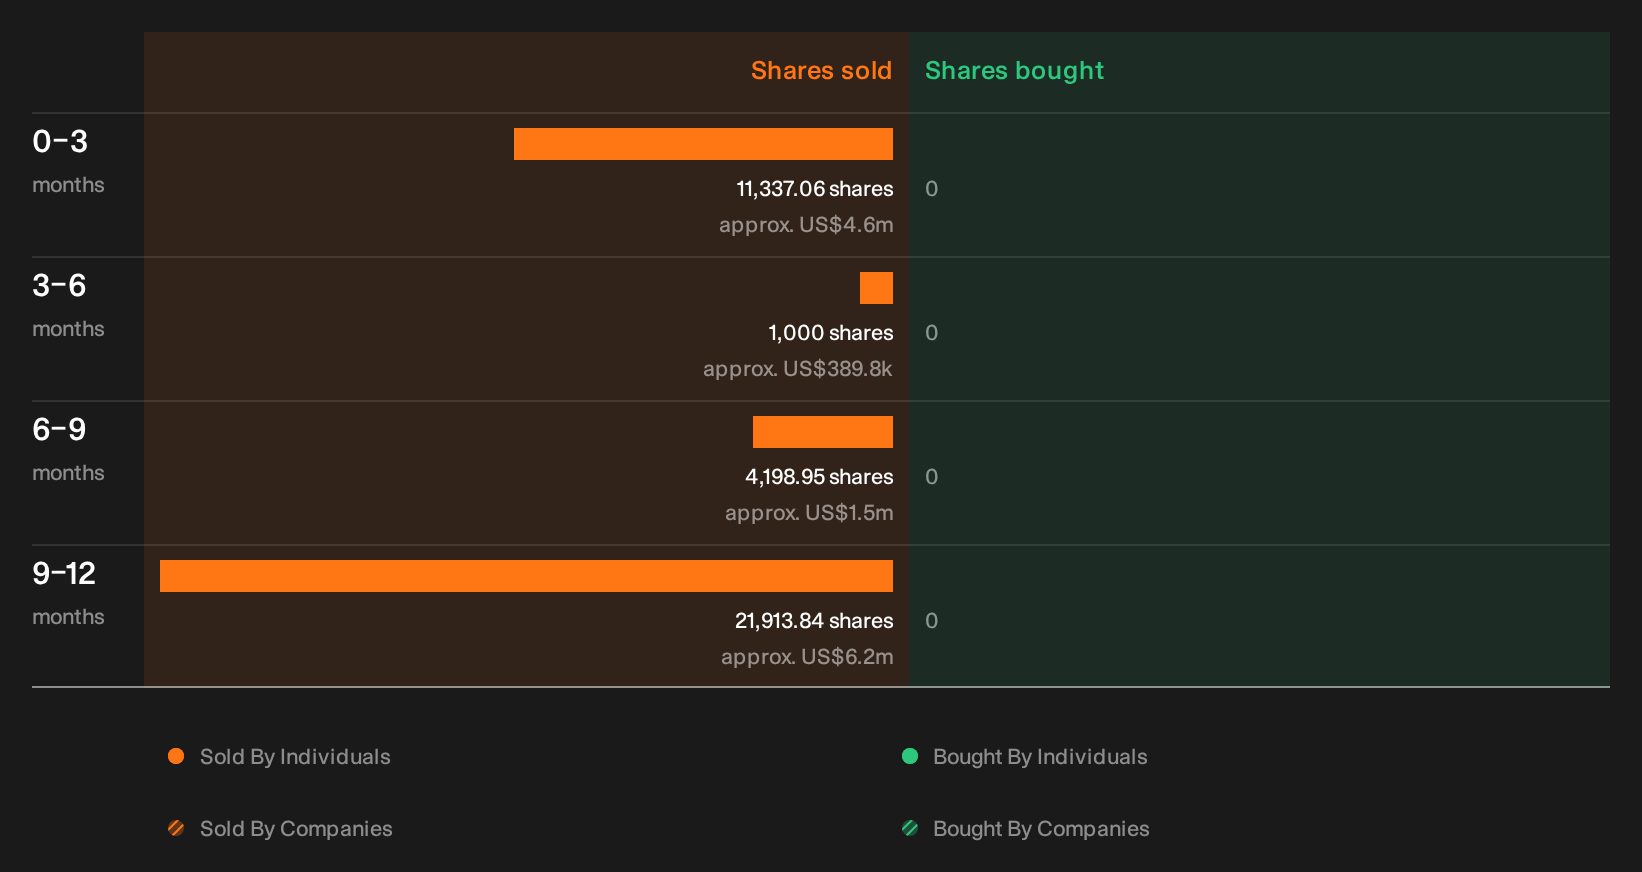
Before you lean too hard on the current Analog Devices valuation story, it is worth seeing which insiders have been selling recently, how much they have parted with and what that might signal. See the recent insider selling flagged for Analog Devices.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com