
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did PFAS Cleanup Approval Just Shift Parsons (PSN) Investment Narrative?
- Parsons Corporation received a Success Memo from the U.S. Department of War’s Environmental Security Technology Certification Program and Defense Innovation Unit for its patented Thermal Conduction Heating technology, confirming federal approval to use the system for on site PFAS contaminated soil remediation across U.S. projects.
- This Success Memo functions similarly to a sole source contract and could streamline how federal buyers award follow on PFAS cleanup work to Parsons without repeated competitive bids, which directly affects project visibility, bidding costs, and future workload planning.
- We will now look at how Parsons' PFAS Success Memo and sole source style access could influence the company’s broader investment narrative.
Scan beyond Parsons and line up other potential PFAS and environmental remediation beneficiaries with the curated list of solid balance sheet and fundamentals (25 results)
Parsons Investment Narrative Recap
To own Parsons, you need to believe the business can keep shifting toward higher margin federal tech, environmental remediation and critical infrastructure work while working through contract clean up and guidance resets. The PFAS Success Memo sits directly in that thesis by giving the firm a clearer path for federal soil remediation projects, which can help operational visibility if the work scales.
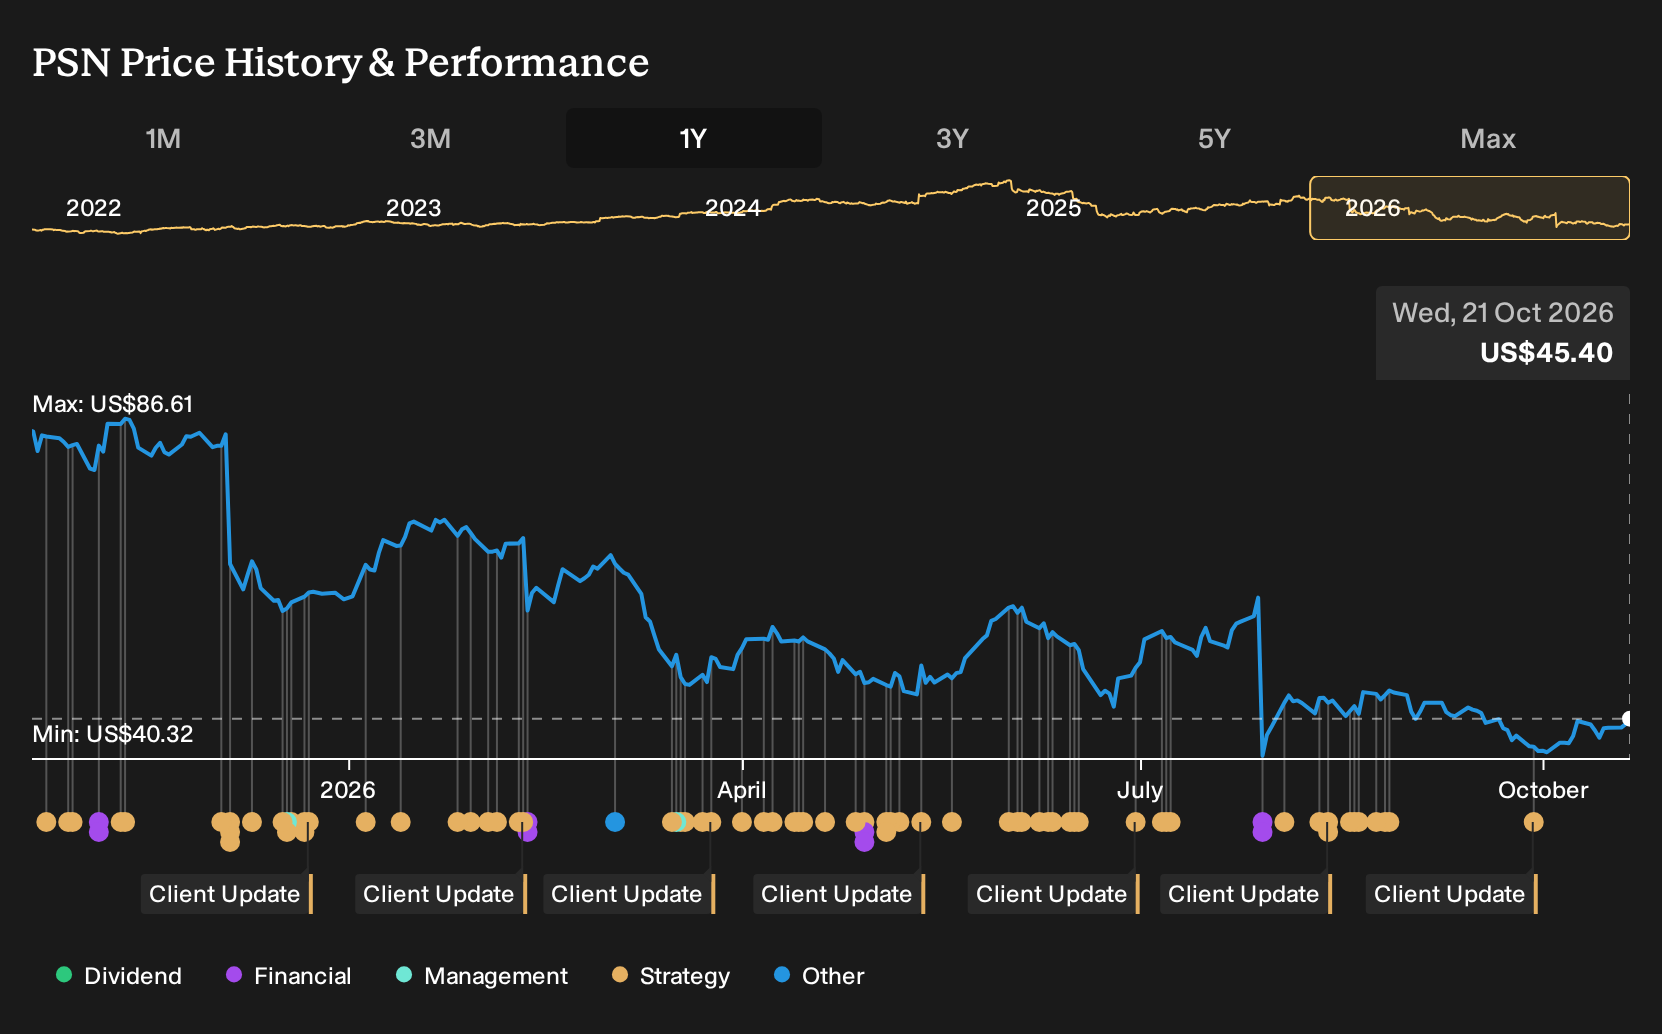
The near term hinge point remains basic execution. Parsons is still digesting contract exits, weather related JV costs and a cut to 2026 revenue guidance to US$6.2b to US$6.5b after timing issues. The biggest risk is more legacy charges or funding shifts that again pressure reported earnings and keep the share price volatile.
The PFAS approval connects most closely to Parsons’ existing push into environmental remediation and product heavy solutions such as its patented Thermal Conduction Heating technology. A Success Memo that lets federal buyers move faster on follow on PFAS work fits the broader aim of growing repeatable, solution based federal revenue instead of single project construction jobs.
For you as an investor, the operational question is whether Parsons can turn this regulatory green light into consistent bookings without taking on the kind of contract structures that previously produced one off losses. Execution quality on these PFAS projects, the mix of remediation work inside Federal Solutions and how that interacts with already high debt levels will likely influence how credible current margin and earnings forecasts look over time.
Parsons' current analyst narrative points to revenues of US$7.2b and earnings of US$407.1m by 2029, based on an assumed 4.6% yearly revenue growth rate and an earnings increase of about US$249.7m from US$157.4m today.
Uncover why Parsons' fair value indicates a 31% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most bearish analysts worry less about Parsons winning PFAS work and more about whether it can turn any of it into clean, predictable cash flow. Before this Success Memo, the lowest forecasts were only looking for about US$6.9b of 2029 revenue and US$328.9m of earnings, so their story is far more cautious. Use that gap in expectations as a prompt to explore several viewpoints and decide which version of Parsons’ future feels more realistic to you now that this PFAS approval is on the table.
Explore 3 other Parsons fair value estimates, including one that suggests it could be worth just $58.36!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Parsons research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Parsons. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Parsons' overall financial health at a glance.
Looking For More Investment Ideas Beyond Parsons?
Once you have formed a view on Parsons, it can help to widen the lens and benchmark it against other listed businesses. The Simply Wall St Screener lets you move from a single stock story to a curated set of companies that share the traits you care about most.
- If you want potential mispricing with quality behind it, start by reviewing a carefully filtered pool of 33 high quality undervalued stocks that pair fundamentals with attractive valuations.
- If capital preservation and smoother swings matter to you, consider screening for 31 resilient stocks with low risk scores that score well on balance sheet strength and risk metrics.
- If you are hunting for less crowded ideas, scan through a focused group of 21 high quality undiscovered gems that combine solid financial profiles with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com