
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should New U.S. Leadership Require Action From BMO Stock Investors?
- Bank of Montreal has appointed Tim Cox as U.S. Country Head and CEO of its U.S. subsidiaries, following the retirement of Darrel Hackett into an Executive Vice-Chair and Senior Advisor role, in a move focused on its large U.S. division.
- The leadership handover in BMO’s U.S. arm affects a business that contributes a substantial share of group earnings. As a result, how Cox executes on lending, risk and costs in that market will matter directly for the bank’s broader performance goals.
- The next area of focus will be how Bank of Montreal’s investment narrative could shift as Tim Cox takes charge of the U.S. business.
See how Bank of Montreal compares with other banks facing similar leadership and profitability questions by reviewing our curated list of 8 resilient stocks with low risk scores.
Bank of Montreal Investment Narrative Recap
To own Bank of Montreal, you need to believe the North American banking engine keeps doing its job. That means steady loan demand in Canada and the U.S., credit losses that stay within current expectations, and management delivering on efficiency work, including AI programs that target a $1b PPPT benefit by 2030.
The most important near-term swing factor is execution in U.S. Banking, where returns have lagged ambitions. Tim Cox stepping in as U.S. Country Head makes that execution risk more visible, but does not yet change it. Key downside risk remains a weaker Canadian economy combined with rising credit costs and tech spending that outruns revenue.
The fresh appointment of Cox as U.S. Country Head is the announcement that most clearly links to this leadership shift. He comes out of legal and regulatory roles, which puts a different skill set in charge of a unit that already delivers record PPPT but still chases a 12% ROE ambition and tighter operating leverage.
For you as a shareholder, the question is simple. Does a new U.S. leader improve the odds that loan growth, risk appetite and cost control line up with BMO’s capital recycling moves, including recent non-core U.S. sales, or does the transition slow progress? Until there is hard data, the change is more of a watchpoint than a thesis breaker.
What The Current Forecasts Assume For Bank of Montreal
Analysts present a clear mathematical outlook for Bank of Montreal. Current projections indicate CA$43.3b of revenue and CA$11.6b of earnings by 2029, supported by a 6.7% annual revenue growth rate and an earnings increase of about CA$2.9b from CA$8.7b today.
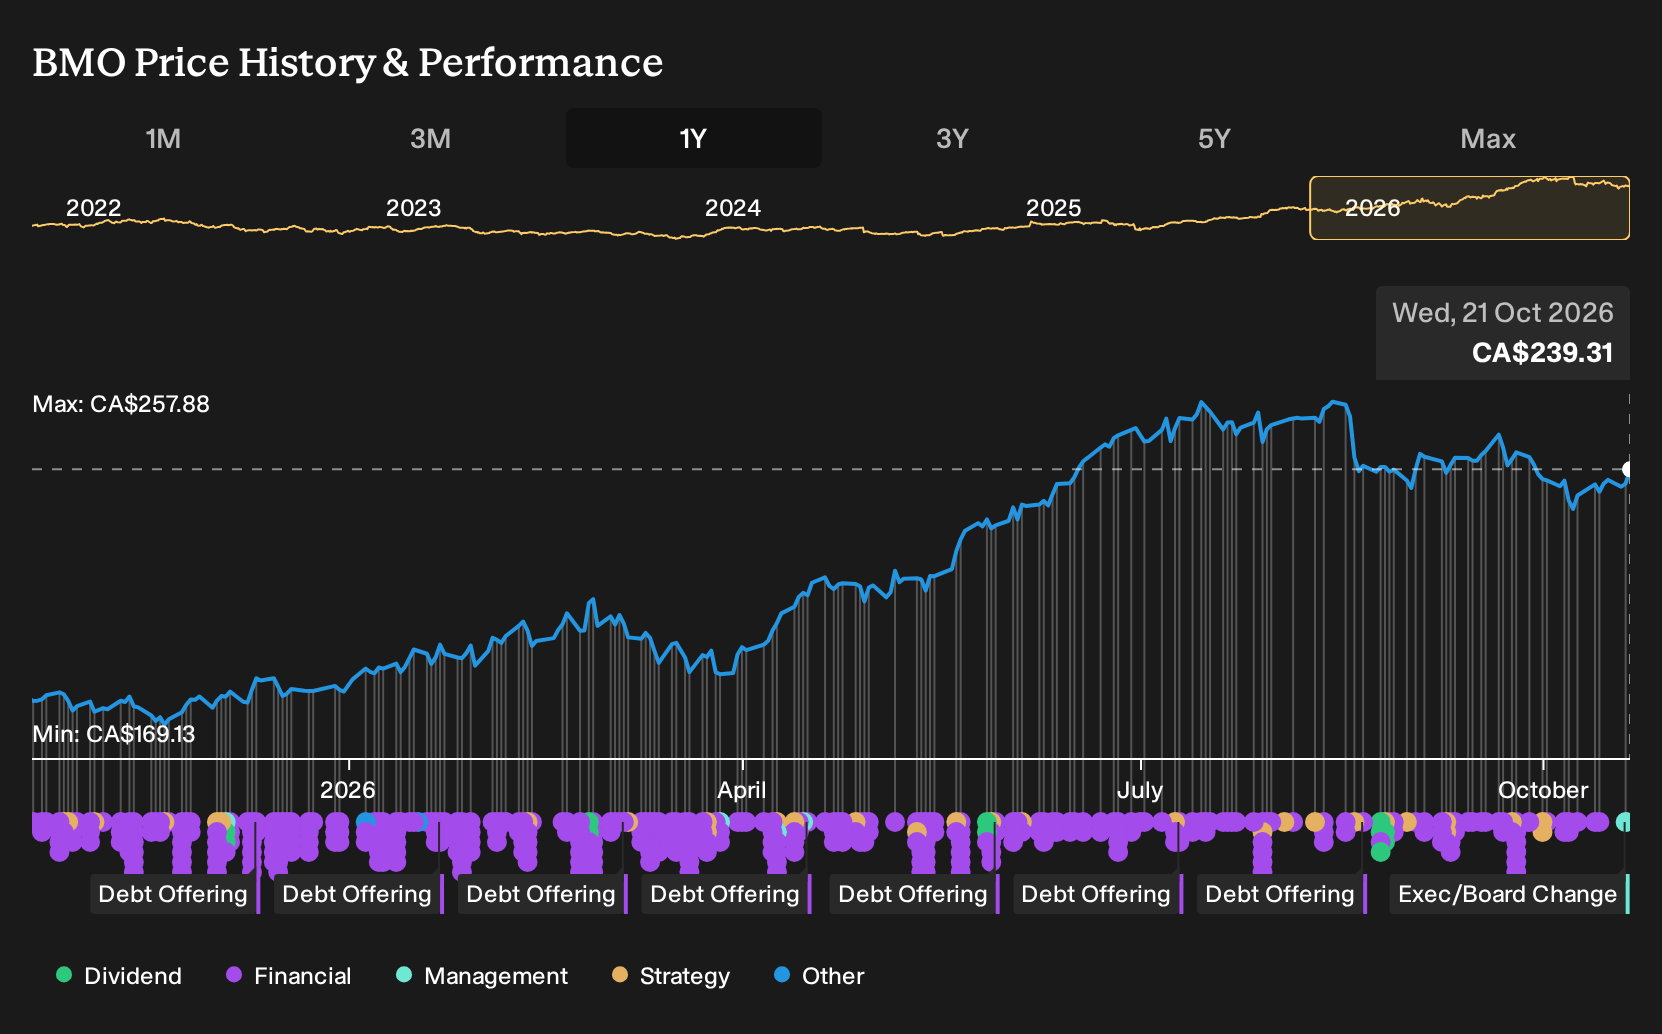
Uncover why Bank of Montreal's fair value indicates a 7% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Simply Wall St Community members have posted three fair value estimates for Bank of Montreal that range from about CA$255 to CA$301 per share, a wide gap for the same stock. Those views do not yet factor in Tim Cox’s appointment or recent 6% funding deals, so you are seeing raw conviction. Use that spread as a prompt to test several alternative viewpoints, including how leadership turnover, defence financing ambitions and tech spending plans could all reshape future performance.
Explore 2 other Bank of Montreal fair value estimates, including one that suggests it could be worth just CA$255.07.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Bank of Montreal research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Bank of Montreal. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bank of Montreal's overall financial health at a glance.
Looking for more investment ideas beyond Bank of Montreal?
If you want to stress test your view on Bank of Montreal, it helps to line it up against other businesses with different balance sheet strength, income profiles and risk levels. The Simply Wall St Screener gives you a way to do that side by side, using focused sets of stocks built around clear financial traits rather than headlines.
- For investors who care most about durable income, review a set of companies we flag as potential income anchors through the 3 dividend fortresses.
- If capital preservation is top of mind, compare Bank of Montreal with a 8 resilient stocks with low risk scores that may better fit a cautious approach.
- To broaden your watchlist with businesses that have strong fundamentals but limited attention, scan a group of 10 high quality undiscovered gems that might merit a closer look alongside BMO.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com