
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Learn Why The Bull Case For ARMOUR Residential REIT Stock Could Change Following Quarterly Losses
- ARMOUR Residential REIT reported a net loss of US$323.75 million for the fourth quarter and US$263.78 million for the nine months ended September 30, 2026, with basic and diluted loss per share from continuing operations turning negative compared with earnings a year earlier.
- The real estate investment trust kept paying monthly common dividends of US$0.24 per share while recording these losses, which raises pointed questions about how ARMOUR Residential REIT balances income distribution with capital preservation in a tougher earnings stretch.
- This article reviews how ARMOUR Residential REIT's investment narrative is tested by quarterly losses that replaced last year's positive earnings.
Scan how ARMOUR Residential REIT's sharp swing into quarterly losses compares with peers by reviewing the hand-picked 7 dividend fortresses that aim to balance income with financial resilience.
ARMOUR Residential REIT Investment Narrative Recap
To own ARMOUR Residential REIT, an investor needs to be comfortable with an Agency MBS vehicle that uses leverage and derivatives to turn a spread between mortgage yields and repo funding into distributable income. The sharp swing to a US$323.75 million quarterly loss and US$263.78 million loss for the nine months puts earnings power and book value resilience under more scrutiny.
The most important near term catalyst is how quickly core earnings and net interest margins stabilize as funding costs, prepayments and MBS spreads move around. The biggest current risk is that rate volatility or wider spreads keep pressuring book value while the company continues to pay monthly dividends that are not well covered by free cash flow.
The November 2026 dividend affirmation of US$0.24 per common share lands right in the middle of this earnings story. ARMOUR Residential REIT is still distributing cash monthly despite sizeable recent losses and existing concerns that the dividend is not covered by free cash generation, so income investors need to track this closely.
That payout decision directly touches both catalyst and risk. On one side, a steady dividend can support interest from yield focused holders as management works its Agency MBS and hedge book. On the other side, maintaining that level of cash return while reporting large losses raises the bar on execution around funding, leverage and any future capital raising.
ARMOUR Residential REIT's current earnings of US$52.5 million are set against analyst expectations for revenue growth of 91.9% per year and forecast earnings of US$1.4b by 2028. This implies an increase in earnings of about 26x and projected revenues of US$825.8 million in the same forecast year.
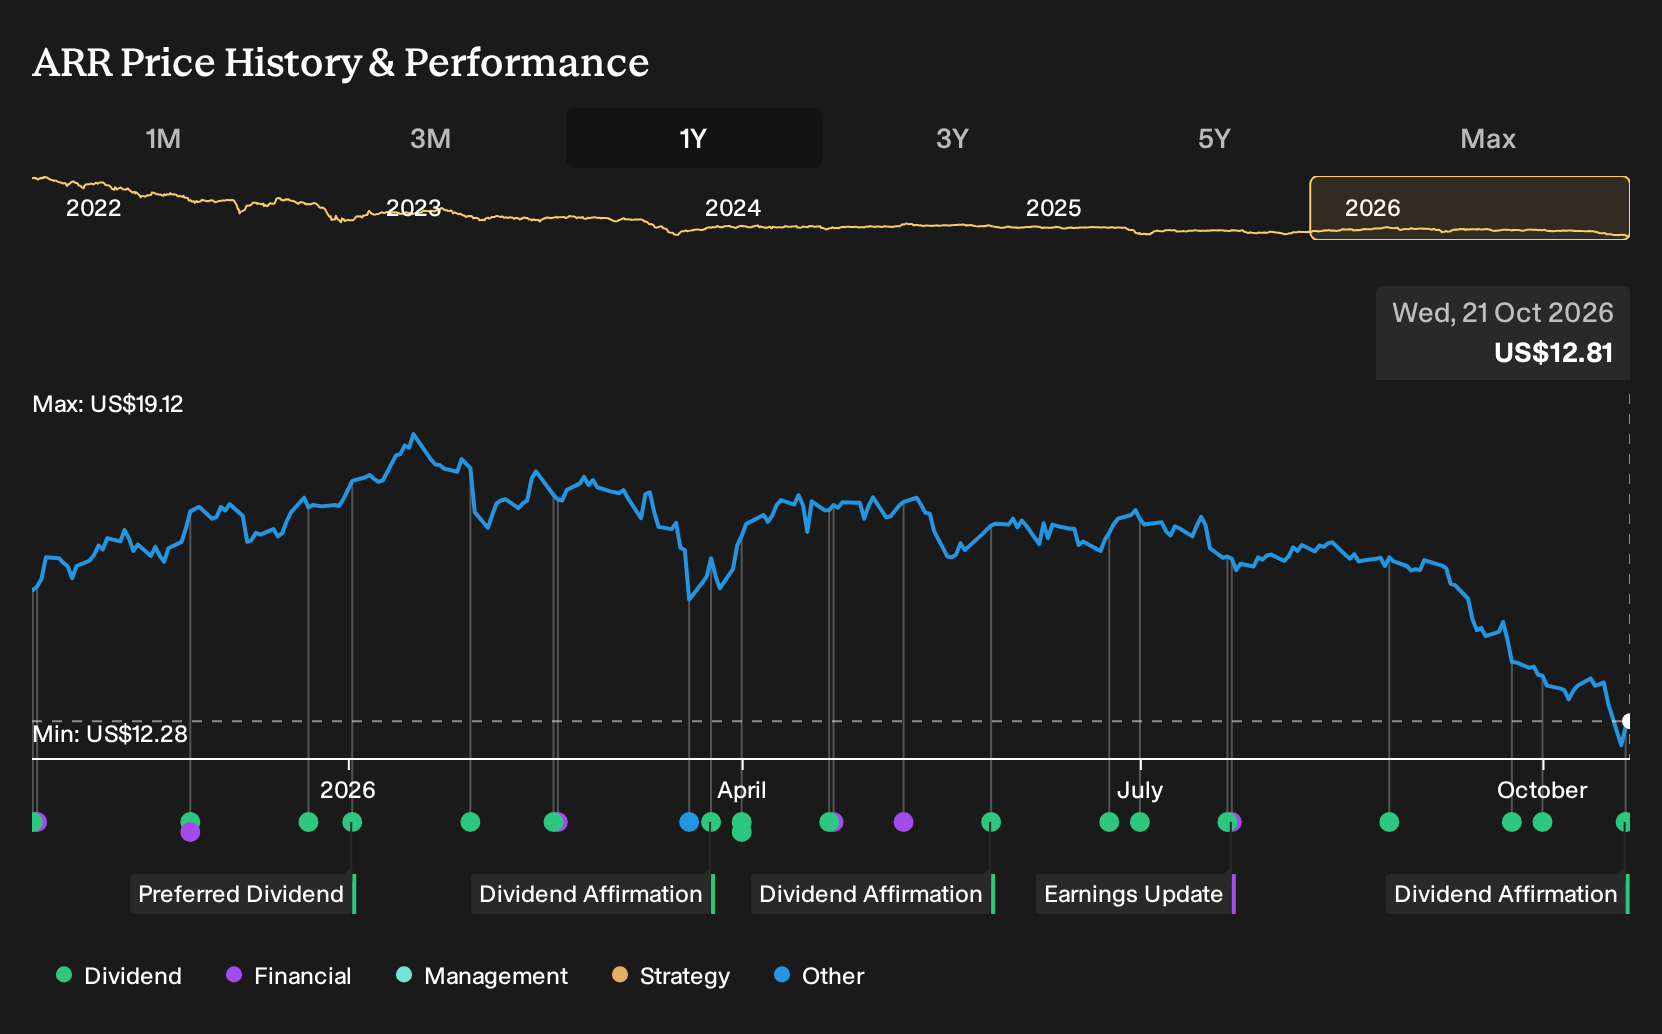
Uncover why ARMOUR Residential REIT's fair value indicates a 33% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
ARMOUR Residential REIT currently attracts only 2 fair value estimates from the Simply Wall St Community, clustering in a narrow US$17 to US$18.38 band. That tight range sits alongside fresh information on large quarterly losses, dividend affirmations and Fed rate risk. Consider these contrasting threads and explore multiple viewpoints before setting expectations.
Explore another ARMOUR Residential REIT fair value estimate, including one that suggests as much as 43% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your ARMOUR Residential REIT research is our analysis highlighting 4 key rewards and 5 important warning signs that could impact your investment decision.
- See our latest analysis for ARMOUR Residential REIT. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ARMOUR Residential REIT's overall financial health at a glance.
Looking For More Investment Ideas Beyond ARMOUR Residential REIT?
If the ARMOUR Residential REIT story has you reassessing income, risk and valuation, it can help to line it up against other opportunities that share some of those traits but come with different balance sheets, payout policies or return profiles. The Simply Wall St Screener lets you filter for exactly that mix so you can build a watchlist that reflects your own preferences rather than inheriting someone else's.
- For investors who put stability first, start with a 31 resilient stocks with low risk scores that screens for businesses where risk scores sit on the lower side of the spectrum.
- If capital preservation and financial strength matter most, focus on a list of solid balance sheet and fundamentals (25 results) to see companies with cleaner leverage profiles and sturdier fundamentals.
- Readers hunting for mispriced quality can review a 21 high quality undiscovered gems and see which stocks combine strong underlying metrics with relatively little market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com