
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Dime Commercial Bancshares (DCOM) Stock Looks Fully Priced Following Its $57.9 Million Deal
Dime Commercial Bancshares has ridden a powerful multi year share price run, and the question now is whether the current valuation can be explained by the earnings that support it. With the stock resetting after shorter term ups and downs, the focus has shifted to what the profit stream really justifies today.
- Over the past 3 years, Dime Commercial Bancshares has returned about 153%, which puts real pressure on the earnings profile to carry that kind of rerating.
- The agreed US$57.9m purchase of ES Bancshares, partly funded with new Dime stock, may support future earnings if integration goes to plan and the enlarged deposit base is put to work efficiently.
- There is a second opinion on Dime Commercial Bancshares worth weighing. See what analysts think Dime Commercial Bancshares's shares could be worth.
The issue now is whether Dime Commercial Bancshares' current share price is properly aligned with what its earnings justify today.
If you want to test the same earnings based valuation question driving Dime Commercial Bancshares across a wider field, run the numbers against 33 high quality undervalued stocks.
Where Does Dime Commercial Bancshares Sit on Earnings?
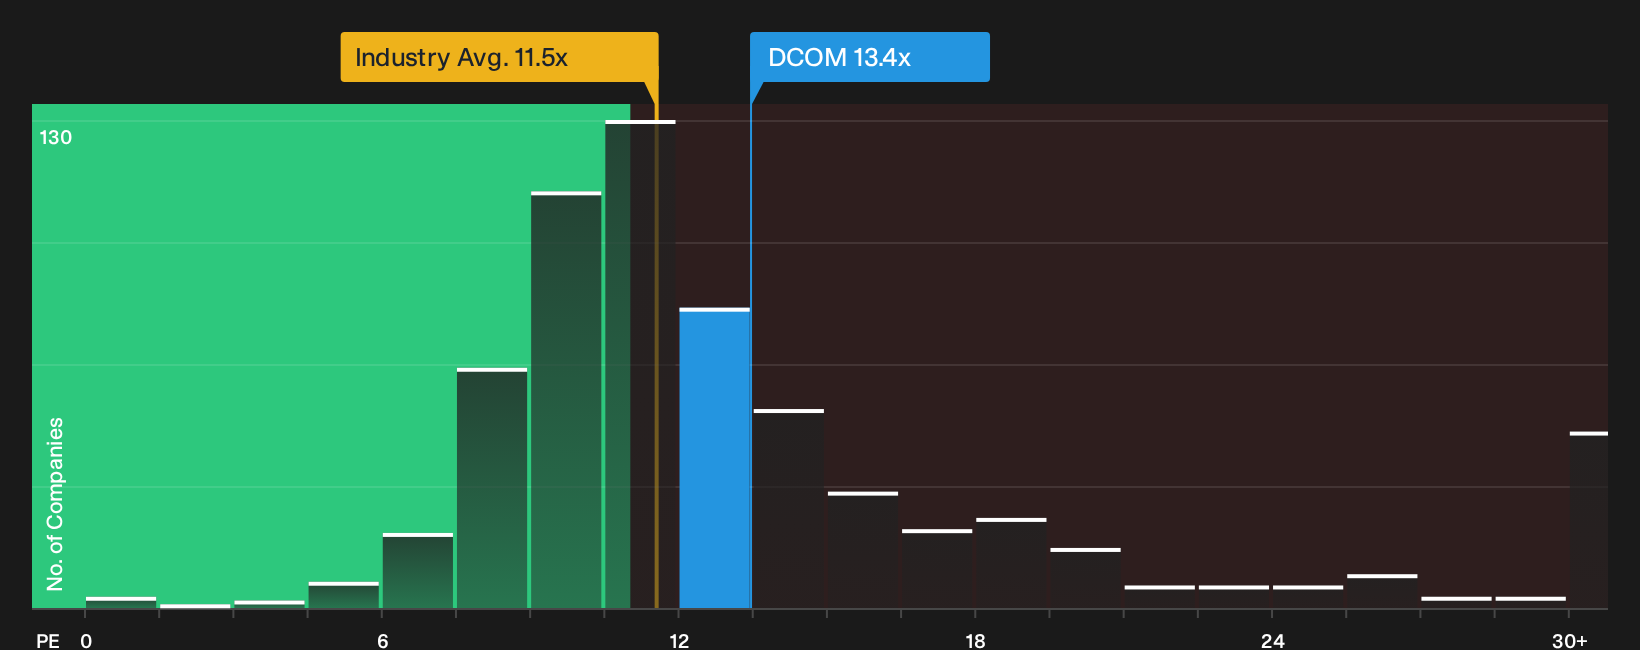
The P/E ratio works well for Dime Commercial Bancshares because earnings are a key anchor for bank valuations. On that lens, the shares trade on about 13.4x trailing earnings, which is higher than the Banks industry average of roughly 11.5x but below a peer group closer to 19.9x. The sector context matters because it shows the stock priced above the wider banking pack yet not at the richer levels seen across more expensive peers.
The fair value framework points to a P/E that would be slightly higher than where Dime Commercial Bancshares trades today, so the current 13.4x sits a little under what that model would imply for its profitability, growth profile and risk. Because the ES Bancshares deal is expected to expand the deposit base and franchise reach, the market already assigns a valuation that reflects those prospects without pushing the P/E to peer-like levels. To see how much of a gap the model still flags and where that leaves upside or downside on this metric, you can run the detailed comparison through. Explore the numbers behind Dime Commercial Bancshares's P/E valuation.
The Dime Commercial Bancshares Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Dime Commercial Bancshares pick up where the P/E puzzle leaves off. They spell out which paths for future growth, profitability and earnings would need to play out for the stock to look meaningfully cheaper or more expensive than today's quote, and they sit on Simply Wall St's Community page. Rather than leaning on a single multiple or model line, each one lays out the assumptions behind its view of fair value so you can compare those inputs with the actual results as they arrive.
One of the top community narratives on Dime Commercial Bancshares: 11% undervalued
"The main factor that has to go right is that Dime Commercial Bancshares converts its low cost commercial deposits, loan repricing pipeline, and controlled CRE exposure into sustained margin improvement..."
Discover why this Narrative puts Dime Commercial Bancshares at 11% undervalued.
One more Dime Commercial Bancshares check that belongs beside the earnings math
The last missing piece is who actually runs Dime Commercial Bancshares and how their incentives line up with your interests, because the pay structure behind the decisions steering the bank can matter as much as any ratio. See who runs Dime Commercial Bancshares and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com