
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Investors Got Wrong About Iluka Resources Before The Drop
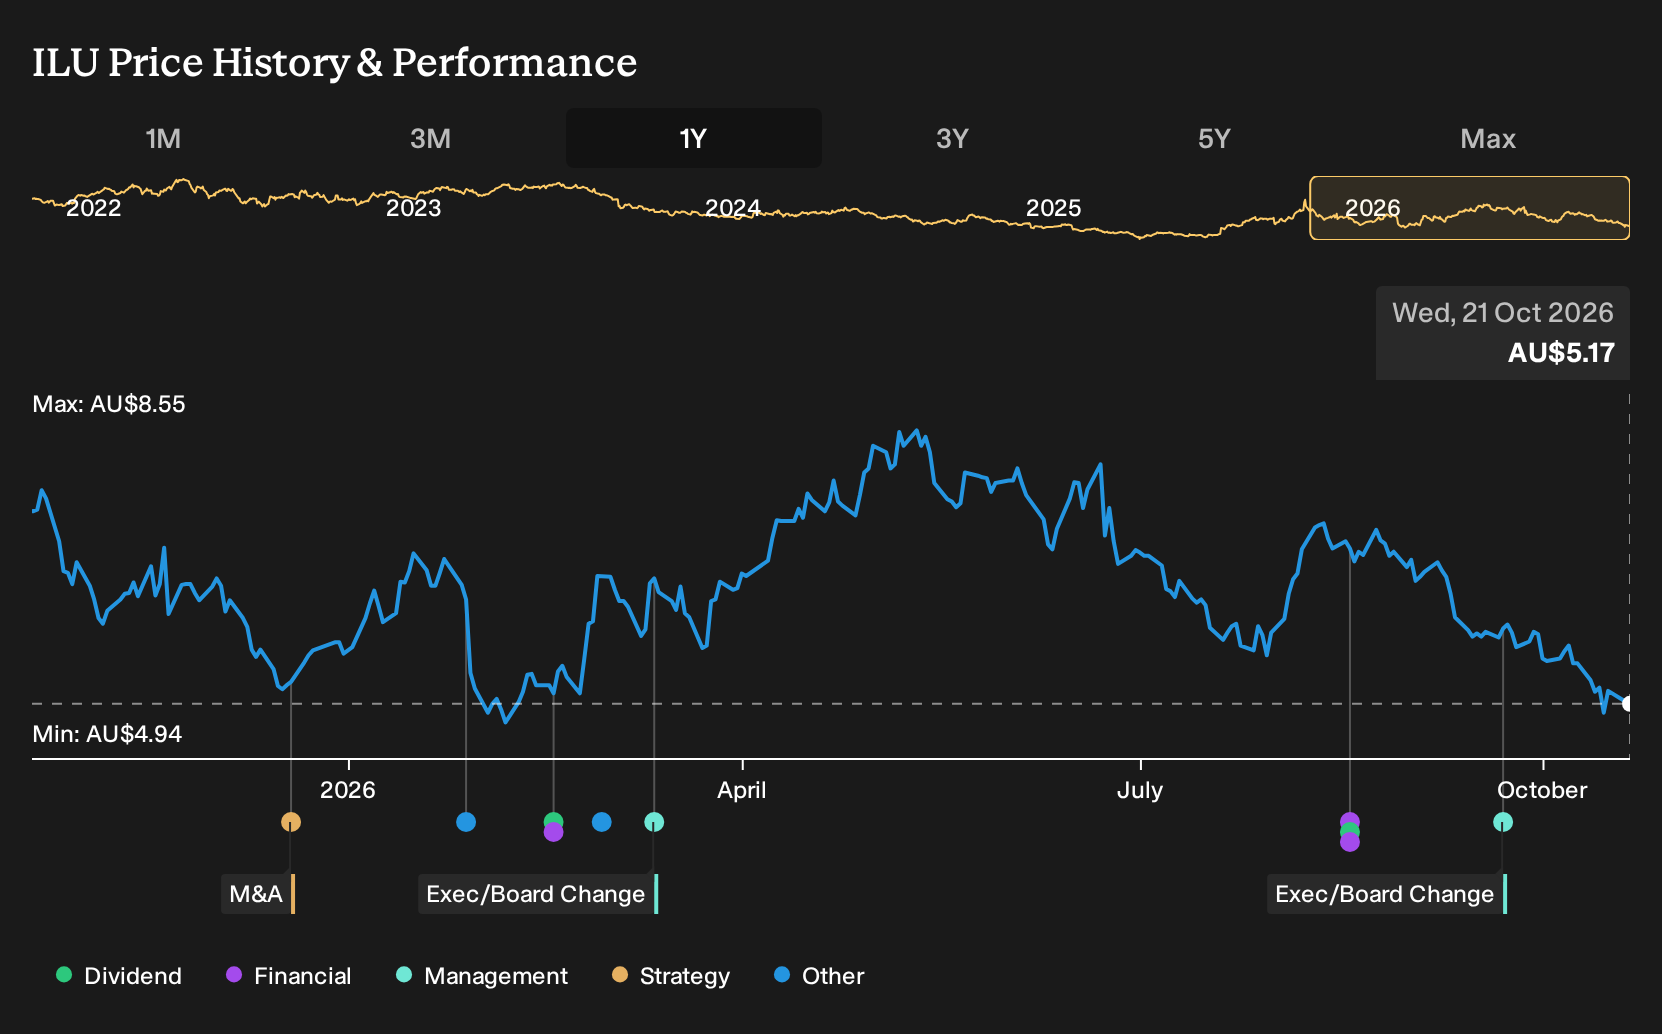
Iluka Resources has just locked in its first rare earths offtake with a global carmaker and an A$1.65b government loan for the Eneabba refinery, yet the share price dropped on the news. Investors who held Iluka Resources over the past year are down 31.1%, including dividends. If you had bought on the upbeat 2025 rare earths story, how should this mix of contracts, losses and cost pressure reshape what you expect from Eneabba and Balranald now?
The move put Iluka Resources in the middle of this trade. Scan 33 best rare earth metal stocks for other companies exposed to it.
The Two Iluka Resources Stories Investors Were Weighing
The shares cost A$7.55 at the start of the period, and anyone looking at Iluka Resources then had to choose between two very different stories about Eneabba and Balranald.
The bull case framed A$8.47 as a fair value. This was a price implied by assumptions that Eneabba could anchor Western rare earth pricing and support revenue growth of 16.3% a year with profit margins near 16.2%.
The bear view pointed to A$6.40 as its implied value. It focused on risks that rising Australian costs and capital intensity at the refinery could squeeze margins toward 8.7%, while using similar revenue growth assumptions.
What The Evidence Did To The Iluka Resources Story
Iluka Resources secured a four year take or pay rare earths offtake with a global carmaker and an A$1.65b non recourse government loan for Eneabba, which supported the bullish idea of bankable contracts and funding. The later H1 2026 result pulled the other way. Revenue fell from A$577.8m to A$455.9m and a A$92m profit turned into a A$23.9m loss, with net margin dropping from 15.9% to 5.2%. Overall, the evidence cut both ways.
The useful test here is simple. When a story hinges on new projects, check that signed volumes and funding line up with later income statements, especially revenue trend and net margin, before treating the original case as proven.
What Iluka Resources' Lower Price Now Asks You To Believe
Today Iluka Resources trades at A$5.17, with the selected Narrative arguing that its Fair Value sits above that level. The thesis leans on Iluka supplying critical minerals for electrification, with Eneabba rare earths and Balranald mineral sands reshaping the mix over time.
For that higher figure to be reached, a buyer now would be assuming Eneabba is completed and ramped successfully, while demand for Iluka’s key products supports sustainable returns on that heavy investment.
"Over the longer term, however, Iluka is a more compelling proposition. The company operates in strategically important minerals, benefits from meaningful government backing, and the national importance of the Eneabba refinery makes it likely that the project will be supported through to completion."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Find Your Own Contrarian Opportunity
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 39% below our estimate - targets higher throughput from funded mill expansions and staged mine development projects.
- Company 2 - 28% below our estimate - leans into service contracts that rebalance revenue toward more recurring earnings streams.
- Company 3 - 31% below our estimate - expands multi affiliate funds under management while routing additional fee income through infrastructure.
Three companies from the same screener. Open every one of the 4 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com