
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Aritzia And 2 Other Top Canadian Quality Stocks
Australian investors have fresh reason to care about strong balance sheets. A class action against Meta in Australia shows how fast legal and regulatory shocks can hit large platforms and rattle sentiment. When headlines turn messy, financially resilient businesses with high returns on equity and solid past track records often hold more appeal. This article highlights three Canadian stocks that combine robust finances with quality fundamentals.
The three stocks below are a sample, and the full screen surfaces 4 more businesses with similar balance sheet strength and return profiles that are not covered in this article.
If you want to identify and analyze those extra opportunities with the same filters used here, head straight to the Solid Balance Sheet and Fundamentals screener.
Aritzia (TSX:ATZ)
Aritzia is a vertically integrated womenswear retailer that designs and sells its own labels through boutiques and online, a model that aligns cleanly with the Solid Balance Sheet and Fundamentals theme because brand control supports margins and consistent returns. The apparel segment generates about CA$4.3b in revenue, and the stock carries a market value near CA$17.3b.
Aritzia’s owned-brand approach, tight product control and capital-light digital reach sit neatly with the screener’s focus on strong returns and solid funding. Those ingredients matter even more as the business leans harder into its next phase of U.S. expansion.
"Aritzia's ongoing U.S. boutique rollout, with new locations reportedly paying back in under one year and management indicating room to expand from roughly 76 to 82 to at least 180 to 200 boutiques, points to a continued store-led uplift to net revenue."
What ultimately happens to earnings power now depends on how one less visible pressure shapes future margins and cash generation.
That pressure point is exactly where the story gets interesting, and the full narrative for Aritzia explores whether Aritzia’s U.S. expansion is accelerating value or quietly masking fragility.

Sprott (TSX:SII)
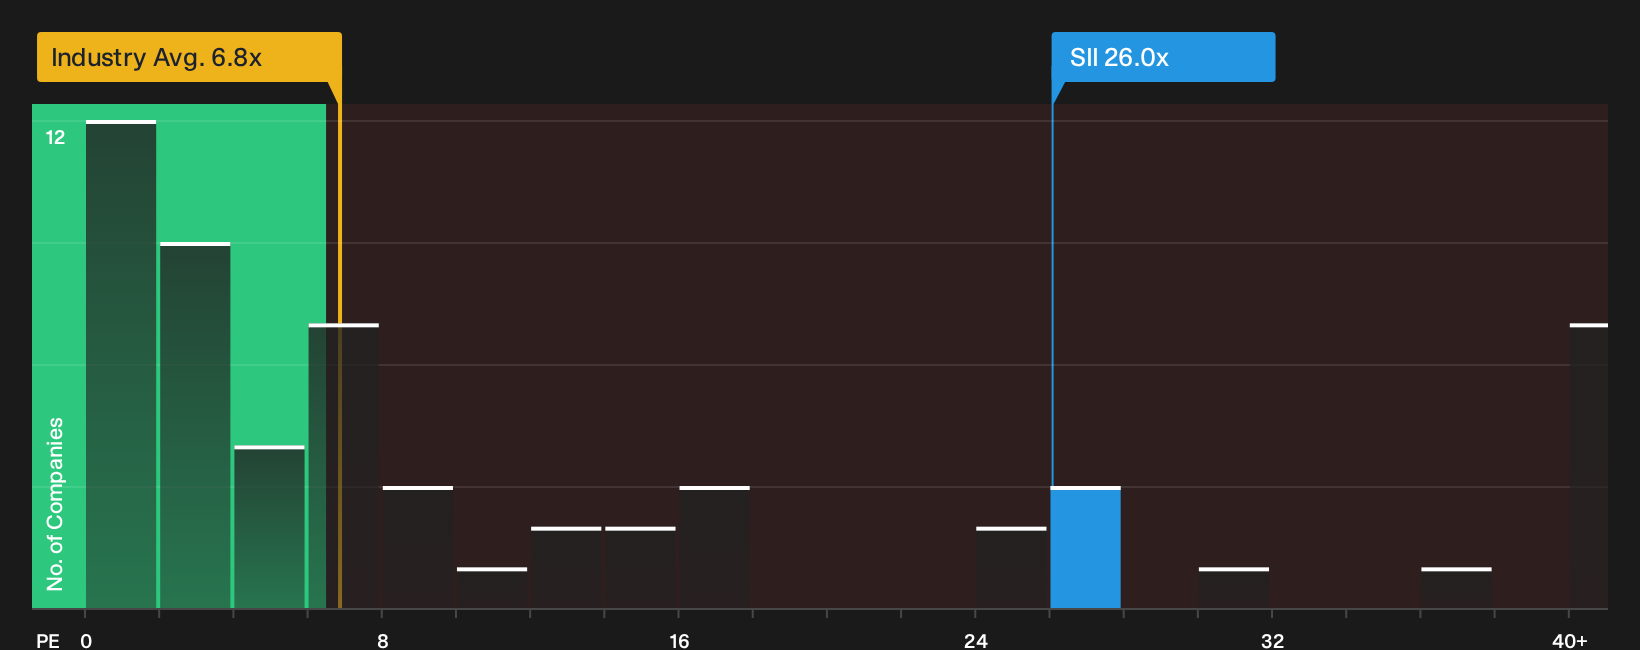
Sprott is a Toronto-based asset manager focused on precious metals and natural resources funds that generate recurring fees, which aligns neatly with a “Solid Balance Sheet and Fundamentals” theme. Most revenue comes from Exchange Listed Products at about $224 million, Managed Equities at about $95 million and Private Strategies at about $80 million. The stock has a market value near $3.8b.
Sprott ties balance-sheet strength to real cash flow. Management fees from precious metals and resource funds have helped push net profit margins to 26.4% and supported strong recent earnings growth, even as the stock trades on a premium 26.1x P/E. Future ROE now depends heavily on how fee growth interacts with any slowdown in assets raised into those specialist strategies.
That fee and asset growth mix is exactly where the Sprott story could surprise next, so tap into the analyst forecasts for Sprott to see how sentiment and earnings expectations line up.
Celestica (TSX:CLS)
Celestica runs a global electronics manufacturing and supply chain services operation for original equipment makers, hyperscalers and cloud providers, with hardware platform solutions for AI racks tying it closely to the Solid Balance Sheet and Fundamentals theme. It generates about $3.3b from Advanced Technology Solutions and $12.3b from Connectivity & Cloud Solutions, and the stock is valued around $48.5b.
Celestica pairs a strong balance sheet with high forecast earnings growth of 31.32% a year and improving profitability, with net margins at 7.2% and return on equity expected near 34.6%. That combination of AI infrastructure contracts, recurring cash flow and premium P/E near 31.4x only holds together if one unseen pressure on earnings quality behaves itself.
If you want to see how that pressure on earnings quality shows up in the numbers, walk through the analysis report for Celestica and judge whether Celestica’s momentum really holds.

Seeking Alternatives Before The Crowd?
Fresh ideas move first. Breakout stories, dropping laggards and under the radar for now opportunities can get caught quickly. Scan what others miss while it matters, act now.
- Hunt for resilient income machines before yields get compressed by latecomers through the 3 dividend fortresses, which focuses on cash-heavy businesses built to keep paying.
- Track where AI momentum is quietly flying under investor radars with the curated 38 profitable AI stocks that aren't just burning cash, which filters for real earnings, not just hype.
- Catch early movers linked to a potential nuclear build out using the focused 16 nuclear energy infrastructure stocks, which highlights infrastructure players tied to long-cycle energy demand.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com