
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
SEGRO (LSE:SGRO) Draws Bid Interest, Is It Fully Priced?
SEGRO (LSE:SGRO) has been back on investor watch after fresh Rule 8.3 disclosures showed Natixis SA and Millennium International Management LP opening positions linked to an offer involving Prologis, Inc.
Those Rule 8.3 filings land at a time when SEGRO’s share price has eased in the short term but still carries strong recent gains, with a 7-day share price return of 3.77% and a 30-day move of 3.62% both sitting against a 27.65% year to date share price return and a 31.70% 1-year total shareholder return. Together, these figures indicate momentum that has cooled lately after a much stronger run.
Scan how SEGRO compares with other real estate and infrastructure plays by reviewing our hand-picked 4 resilient stocks with low risk scores that have been holding up on quality and balance sheet strength.
SEGRO has cooled after a strong year, and takeover-related interest has stirred the pot just as the price momentum has eased. Is this a fair entry now, or does it still pay to wait?
Most Popular Narrative: 3% Undervalued
SEGRO closed at £9.10, while the most widely followed narrative on the stock puts fair value at £9.39, a small gap that still matters when you remember this is a large, income-focused REIT.
The "190 MVA" (Mega Volt Ampere) power reserve, frequently highlighted in reports, is a hidden treasure on SEGRO''s balance sheet. Considering the cost and time involved in acquiring a new connection to the London grid, the value of this reserve is far more than just a "permit."
See why 13 investors see SEGRO as 3% undervalued.
Result: Fair Value of £9.39 (UNDERVALUED)
Still, SEGRO’s reliance on successful data centre execution and the pending regulatory clearance of the Prologis deal could both disrupt this undervalued thesis.
Find out about the key risks to this SEGRO narrative.
Another View: SEGRO Looks Expensive On Earnings
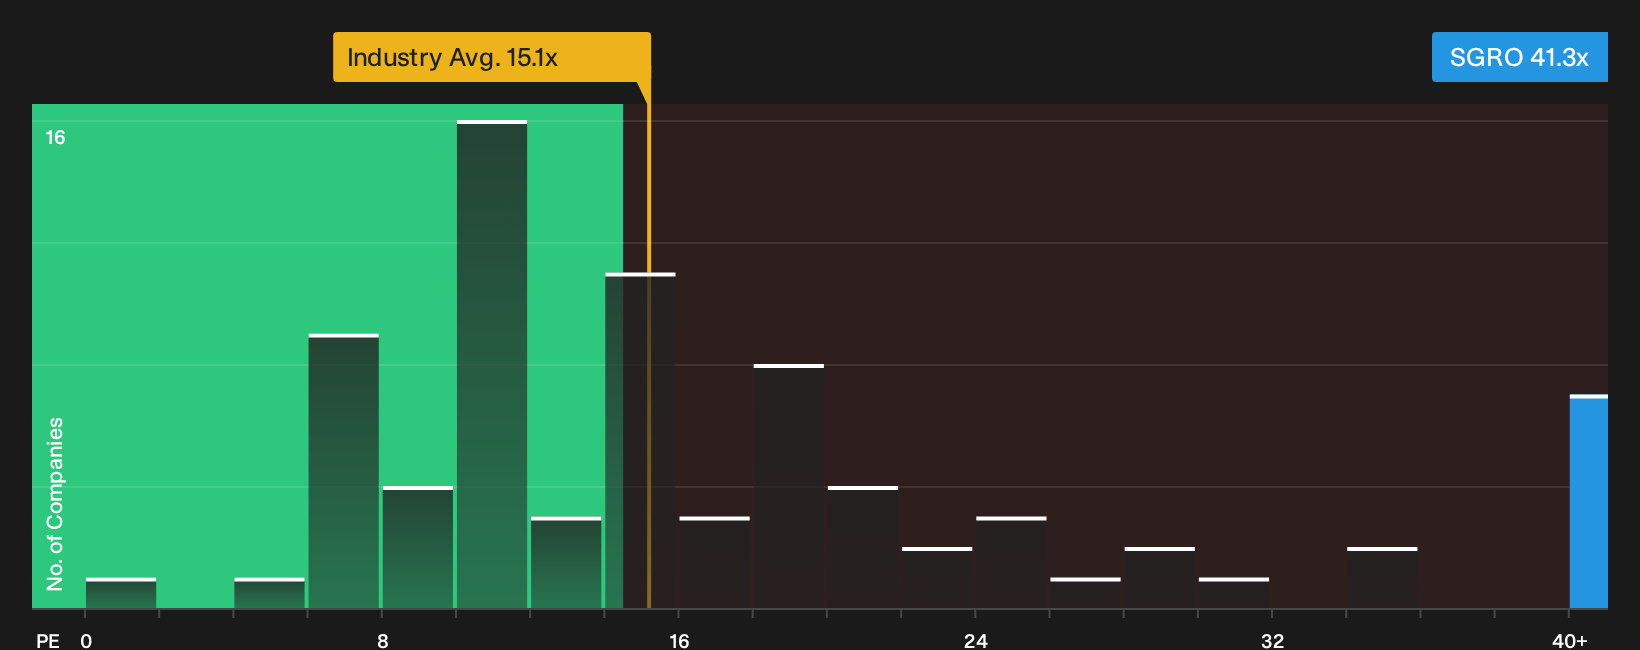
That 3% undervaluation narrative sits awkwardly next to SEGRO’s P/E of 41.3x, which is roughly triple the UK industrial REITs average of 13.8x and well above the estimated fair ratio of 18x. If the market leans back toward that fair ratio, are new buyers taking valuation risk rather than spotting a bargain?
To see how those earnings multiples stack up in more detail, run through the valuation breakdown and what the gap to the fair ratio might mean for future pricing using See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this mix of enthusiasm and caution around SEGRO feels familiar, act while the data is fresh and weigh both sides using the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond SEGRO?
SEGRO gives you one angle, but your portfolio deserves a wider bench of opportunities sourced from different sectors, risk levels, and income profiles.
- Target fresh upside potential by scanning a curated set of promising opportunities with the 5 high quality undiscovered gems.
- Fortify your income stream by focusing on companies that pair higher yields with resilience through the 4 dividend fortresses.
- Anchor your watchlist with financially robust candidates screened for balance sheet strength using the list of solid balance sheet and fundamentals (9 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com