
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Can Microsoft (MSFT) Still Justify Its Price On Future Cash Flow?
Microsoft has become one of the clearest AI infrastructure stories in the market, and after a 71.8% gain over the past 5 years the question is whether today’s share price is still aligned with the cash the business can generate over time.
- A 71.8% total return over 5 years puts a lot of future cash flow expectations into Microsoft, so the key issue is how much is already reflected in the valuation.
- The new Maia 300 AI chip program and heavy data center and power commitments can reshape Microsoft’s long term cash flows by affecting both the level of AI related revenue and the capital outlay needed to support it.
- If you'd rather focus on earnings, this one's for you. See what Microsoft's 29.6x P/E says about the price.
For investors, the debate is whether Microsoft’s current market value is adequately supported by the cash flows implied by a Discounted Cash Flow (DCF) view of the business.
If you want to test the same cash flow question that hangs over Microsoft against a broader set of AI infrastructure plays, start with 55 AI infrastructure stocks.
Is Microsoft Still Cheap on Cash Flow?
The Discounted Cash Flow model here projects Microsoft’s future cash generation and then discounts it back to today’s dollars. On the cash side, the latest twelve month free cash flow sits at about $96.0b, and the forecasts assume this pool of cash is growing rather than shrinking over the next decade as AI infrastructure and software demand build into the numbers.
Those rising free cash flow expectations are being weighed against a traded share price of $532.95, and on this framework the projections put Microsoft's estimated intrinsic value meaningfully above the current share price. The Maia 300 AI chip rollout and multi decade power and data center commitments help explain why the model leans on sizeable long term cash generation, even as the market is already assigning a premium tag to the stock. Find out what Microsoft could be worth using our Discounted Cash Flow (DCF) estimate.
The Microsoft Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the cash flow puzzle for Microsoft leaves off by laying out which paths for growth, margins and earnings would need to play out for the stock to end up meaningfully above or below today's market value on the Community page. Rather than giving just a single output from a ratio or model, they spell out the future that figure rests on so you can watch how closely reality matches those assumptions over time.
Community views on Microsoft are split between AI buildout as an underpriced opportunity and AI spending plus obligations as a valuation ceiling.
Bull case: 11% undervalued
"The rapid buildout of AI infrastructure, including plans for roughly US$175b to US$190b of calendar 2026 capital expenditures and deployment of first party Maia and Cobalt chips, is intended to address capacity constraints where AI demand currently exceeds supply..."
Discover why this Narrative puts Microsoft at 11% undervalued.
Bear case: 34% overvalued
"Total contractual obligations now stand at $743.8 billion, and the debt line barely moved, so finance leases did all of it..."
Explore why this Narrative puts Microsoft at 34% overvalued.
One more Microsoft signal that deserves a closer look
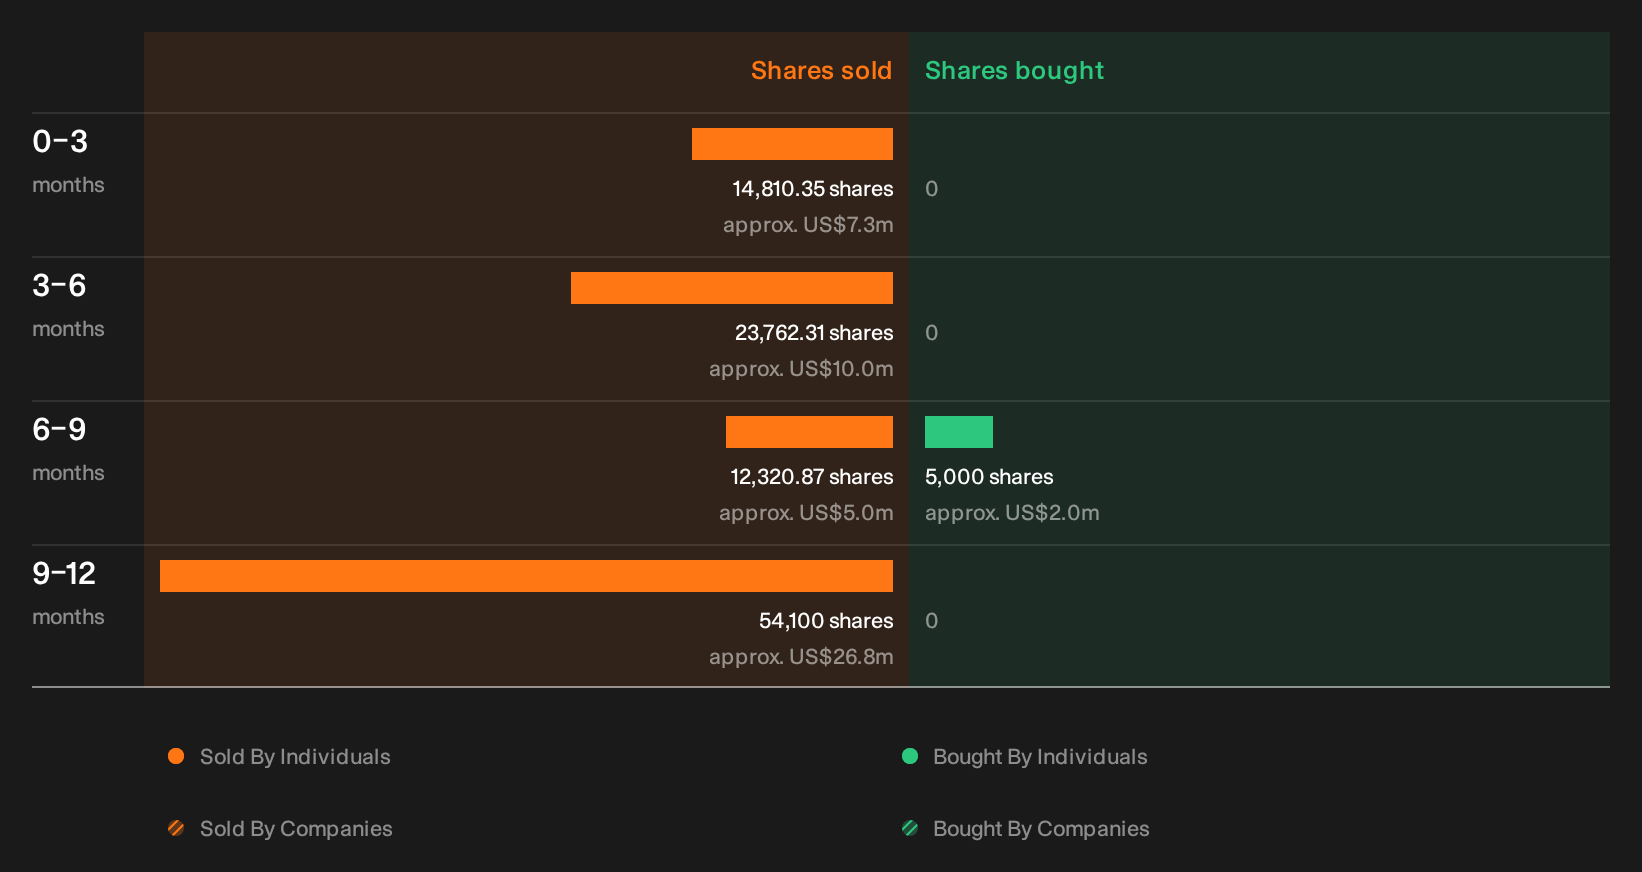
There is one other angle on Microsoft that the valuation work does not touch yet. It is the recent trading activity by its own executives and directors, including who sold, how much, and what that might mean for you to interpret. See the recent insider selling flagged for Microsoft.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com