
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Coherent (COHR) Q4 Results Put Its AI Valuation Narrative Back In Focus
Coherent (COHR) just paired fresh numbers with fresh expectations, reporting fiscal Q4 revenue of US$2.05b and guiding fiscal Q1 2027 sales to the US$2.2b to US$2.4b range on AI-linked and sector upcycle demand.
Coherent’s recent guidance lands after a choppy stretch for the stock, with a 1-month share price return down 26.12% and a 90-day move lower by 24.17%, even as the year-to-date share price return is up 22.23% and the 1-year total shareholder return is 105.89%, pointing to strong longer term momentum. The 1-day share price gain of 2.47% comes on the heels of Susquehanna trimming its price target while keeping a positive stance, which suggests investors are weighing near term volatility against a multi year total shareholder return that is more than 7x over three years.
Scan the AI hardware story beyond Coherent by reviewing a curated set of 55 AI infrastructure stocks that could also benefit from the same demand tailwinds.
Bulls see Coherent as an AI infrastructure lever on sale after a sharp pullback. Bears point to cyclicality and recent volatility. The valuation section now tests which story the current pricing leans toward.
Most Popular Narrative: 41% Undervalued
Coherent’s most followed valuation narrative pegs fair value at $405.22 per share, well above the last close at $237.53. This frames the recent selloff as a debate about timing rather than direction.
The ongoing expansion of AI datacenter infrastructure and high-performance computing is associated with structural growth in demand for advanced optical transceivers (800G, 1.6T, and beyond), optical circuit switches, and related photonics components. This is described as fueling robust sequential order growth and sustained revenue momentum in Coherent's datacom and communications business.
See why 124 investors see Coherent as 41% undervalued.
Result: Fair Value of $405.22 (UNDERVALUED)
Still, heavy capital spending needs and concentrated exposure to large hyperscalers and Apple could quickly pressure Coherent’s cash flow and reset the current upside narrative.
Find out about the key risks to this Coherent narrative.
Another View: Coherent Through The Earnings Multiple Lens
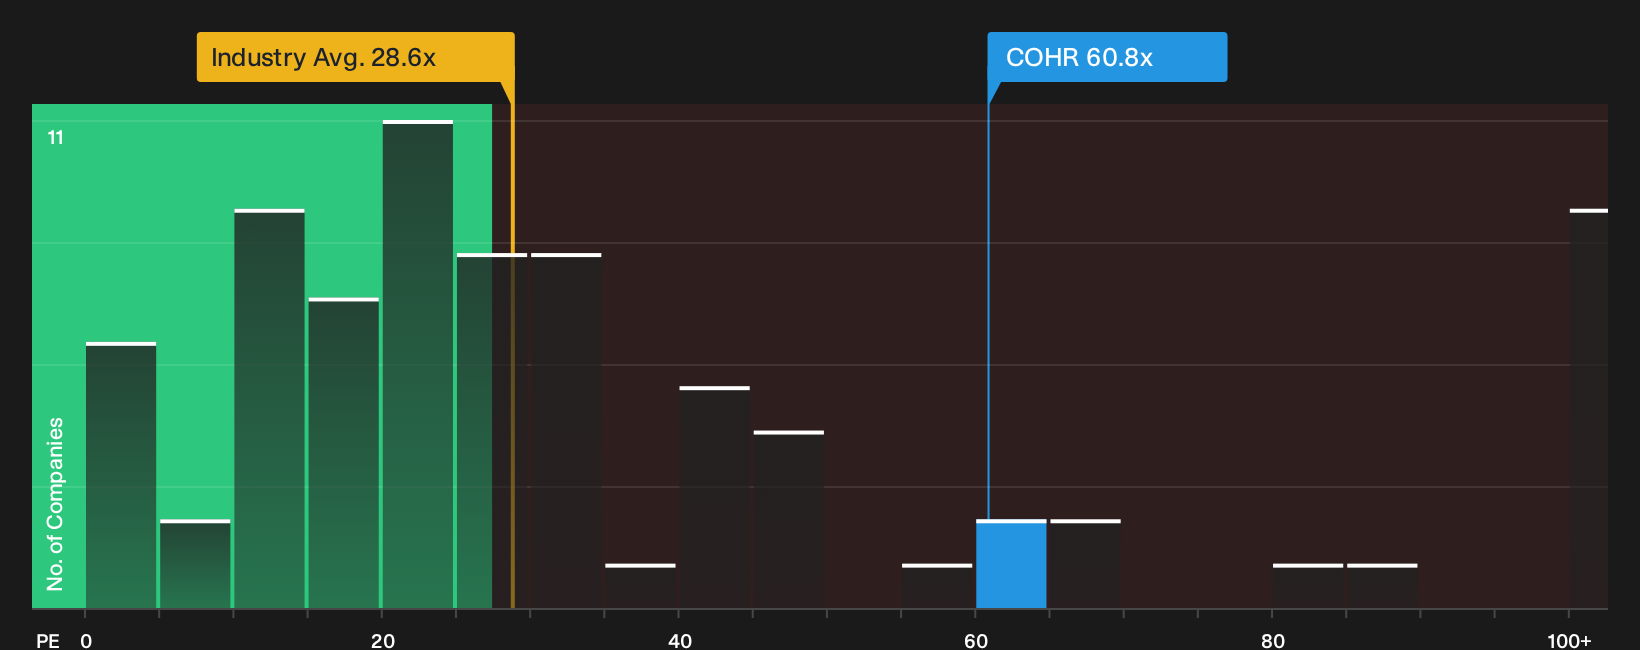
The 41% upside narrative leans heavily on long term cash flow potential. A simpler yardstick looks very different. Coherent trades on a P/E of 60.8x, compared with 28.6x for the US Electronic industry, a peer average of 69.4x, and a fair ratio of 55.8x.
The current valuation therefore sits above the fair ratio and well above the sector average, which points to meaningful valuation risk if expectations cool or earnings slip. The key issue is whether the growth story is strong enough to keep that premium intact, or whether a reset is only a wobble away.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Coherent is split, with sharp optimism on AI infrastructure set against real concern about concentration risk and rich earnings multiples. Act while the data is fresh and form your own stance by weighing the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Coherent?
Do not stop your research with Coherent. Use this moment to broaden your watchlist and pressure test your thesis against other quality opportunities on the platform.
- Target resilient businesses with steady balance sheets and clean fundamentals by scanning the list of solid balance sheet and fundamentals (25 results) that fit your risk limits.
- Hunt for potential mispricings by reviewing a curated 33 high quality undervalued stocks that already screen well on cash flows and financial strength.
- Build a more income-focused portfolio by checking out a handpicked group of 7 dividend fortresses that combine yield with rigorous balance sheet filters.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com