
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Endeavour Silver (TSX:EDR) Restored Guanaceví Capacity, Is Its 43% Undervalued View Convincing?
Endeavour Silver (TSX:EDR) just paired a repair milestone with fresh production data. Processing at the Guanaceví mine is back to full capacity, arriving days after detailed third quarter and nine month operating and sales figures.
Those stronger third quarter volumes and the Guanaceví repair milestone land after a choppy run for Endeavour Silver, with the share price down about 18% over the past month, still up nearly 5% over 90 days, and backed by a very large 3 year total shareholder return above 7x.
Scan beyond Endeavour Silver and compare its latest move with 10 top silver producer stocks that are also pushing production and sales momentum to the forefront.
Endeavour Silver now couples a repaired asset with higher recent production and a share price that just pulled back. Is this a strong miner on the ground, or is that already fully reflected in today’s CA$11.68 valuation?
Most Popular Narrative: 43% Undervalued
Against the latest CA$11.68 close, the most followed narrative pegs Endeavour Silver’s fair value at CA$20.38. This points to a wide valuation gap that only closes if the long pipeline of projects actually produces the cash flows analysts are modelling.
With the Terronera mine nearing commercial production and optimization of recoveries on track, Endeavour is poised for a significant, step-change increase in production and operating cash flows. This should drive revenue and margin expansion as the mine transitions from commissioning losses to full contribution. Integration and potential expansion of the Kolpa mine to 2,500 tpd could further boost production capacity in 2026, increasing the company's operating leverage to higher silver prices and supporting future revenue and earnings growth.
See why 25 investors see Endeavour Silver as 43% undervalued.
Result: Fair Value of CA$20.38 (UNDERVALUED)
Still, recurring mechanical setbacks at Guanaceví and liquidity pressure linked to negative working capital could quickly challenge the bullish valuation story for Endeavour Silver.
Find out about the key risks to this Endeavour Silver narrative.
Another View: What Multiples Say About Endeavour Silver
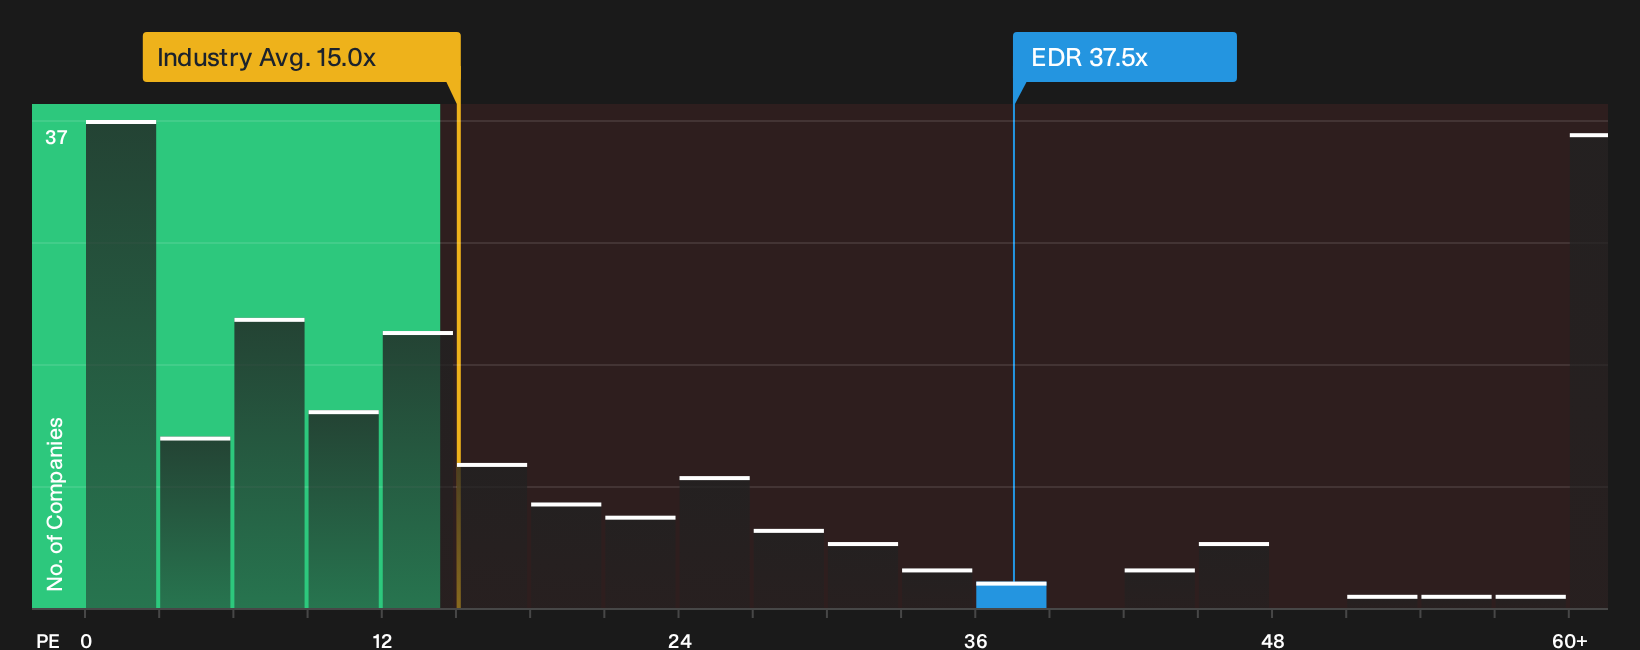
The story changes when the focus shifts from fair value estimates to what investors are currently paying for Endeavour Silver. The stock trades on a P/E of 37.5x, compared with a fair ratio of 18.9x, the Canadian Metals and Mining average of 15x, and a peer average of 37x.
That means the share price already bakes in a rich earnings multiple, which can magnify any disappointment if profits or sector sentiment wobble. The question for you is whether the upside case justifies paying so far above the fair ratio and industry level.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Endeavour Silver can feel noisy, so it may help to move quickly, review the underlying numbers, and weigh the bullish and cautious arguments directly against 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Endeavour Silver?
Do not stop your research with Endeavour Silver. Broader ideas from the Simply Wall Street Screener can help you stress test your thesis and uncover fresh opportunities.
- Target stability chasers who prioritize dependable income and cash returns through a focused set of 3 dividend fortresses.
- Hunt for quality at a discount by scanning a curated pool of 4 high quality undervalued stocks before the broader market pays attention.
- Prioritize resilience and capital protection by zeroing in on 8 resilient stocks with low risk scores that score well on fundamentals and risk controls.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com