
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Missed LG Electronics' 86% Gain? What Holders Had To Believe
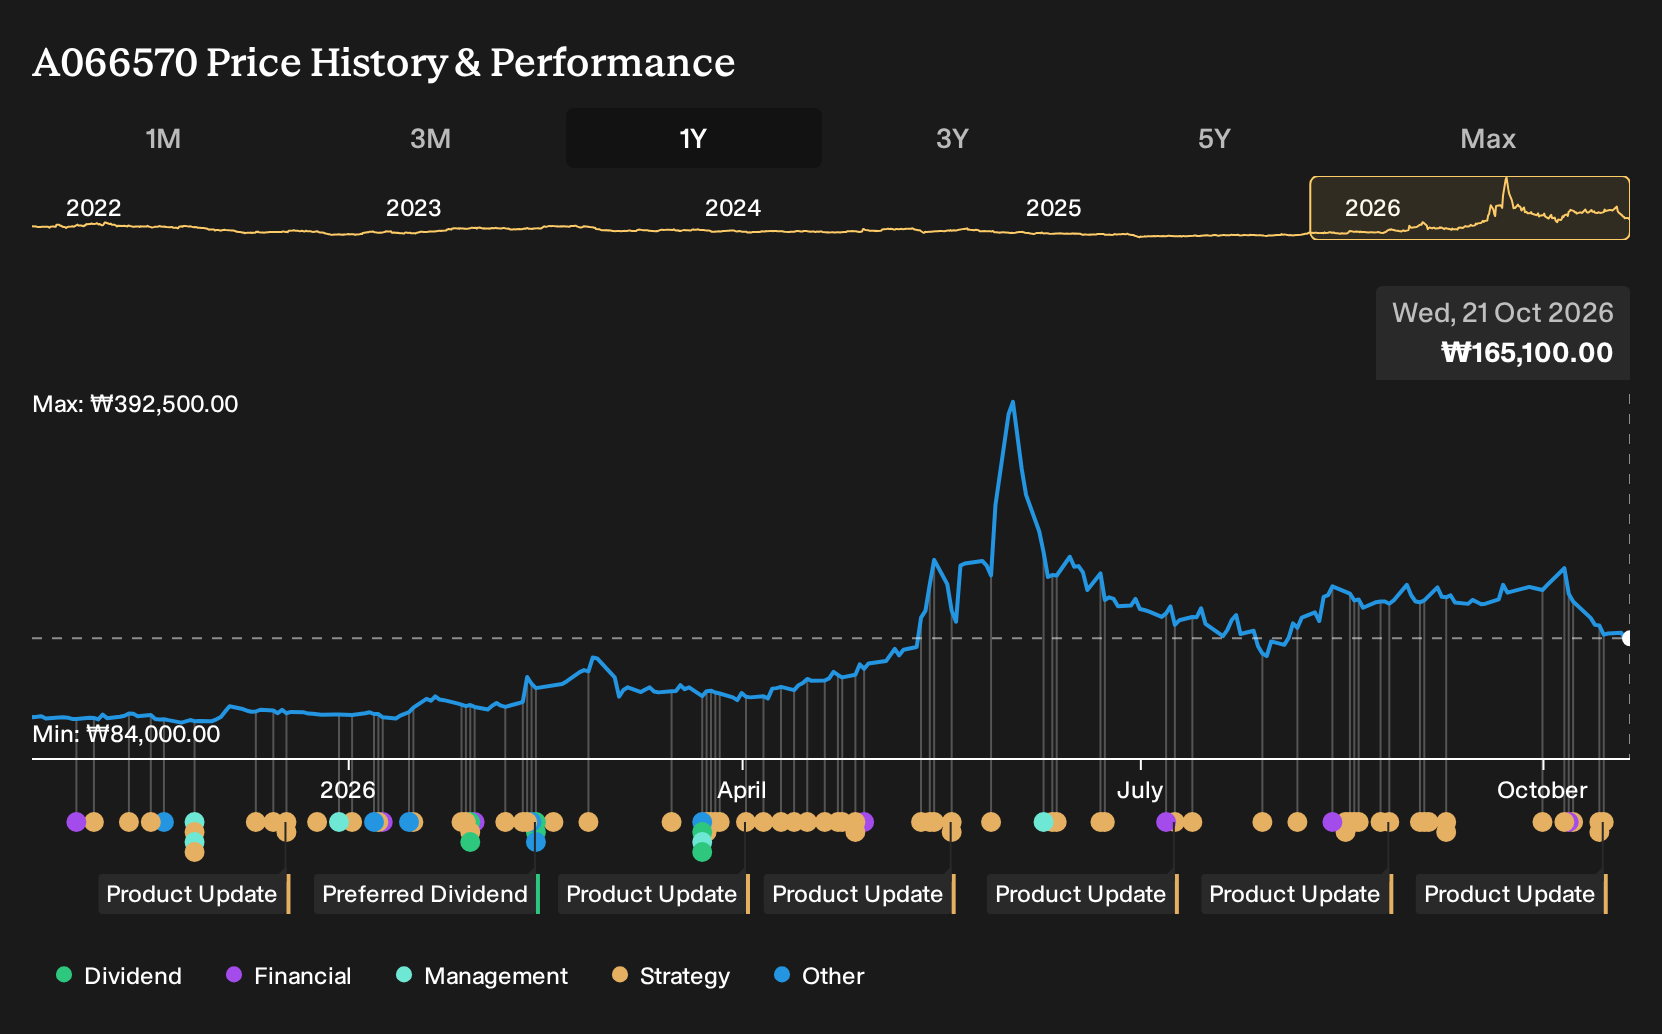
LG Electronics did not make this easy. Revenue for Q2 2026 was higher than a year earlier, yet net margin slipped from 2.9% to 2.5%, which hardly looks like the backdrop for a standout shareholder experience. Holding LG Electronics over the past year would have returned 86.2%, including dividends. If you had been weighing the bullish subscription and eco-services story against tariff and competition risks back in October 2025, what exactly was this contrast asking you to judge?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
LG Electronics is not the only name tied to this theme. Zero in on 129 healthcare AI stocks and compare how each one is priced.
The Argument LG Electronics Investors Were Really Having
The shares cost ₩88,800 at the start of the period, and anyone looking at LG Electronics then had to choose between two very different stories.
The bullish narrative put Fair Value at ₩95,865. It leaned on subscription services, eco-focused products and a 3.3% revenue growth assumption, supported by a profit margin target of 2.5% and a future P/E of 9.6x over three years.
The bearish view set Fair Value at ₩77,500. It treated rising US tariffs and aggressive Chinese competitors as central risks, with revenue growth assumptions of 2.8% and only a modest profit margin move to 1.1%.
What The Results Changed For LG Electronics
LG Electronics rolled out an AI-powered 25-inch WashTower and new DTS:X support for its Sound Suite, both of which supported the bullish focus on digital services and premium, eco-style hardware. At the same time, Q2 2026 results showed revenue at ₩23,826,468m and net income at ₩604,363m, with net margin slipping to 2.5%. The evidence cut both ways.
The lesson is simple. When a thesis leans on higher quality earnings, you watch margin and not just sales. For any other stock, take each new product story and test it against the next reported profitability line.
What LG Electronics’ Price Already Assumes
LG Electronics now trades at ₩165,100 after an 86.2% gain over the past year. The selected Narrative’s Fair Value sits below that level, so it treats today’s quote as already baking in a lot of good news.
The Narrative focuses on whether newer B2B, subscription and auto electronics earnings can comfortably outweigh flat appliances and TVs. Anyone paying today’s price is effectively betting that this shift scales smoothly. How do rising logistics and component costs affect that assumption?
"Key Takeaways: Bearish analysts expect rising trade barriers, input costs and supply chain friction to keep pressuring LG Electronics’ margins, as seen in higher logistics and memory component expenses across several divisions in 2026. The main thing that has to go right is that LG Electronics turns its push into B2B, subscriptions, AI data center cooling and automotive electronics into durable earnings that offset a flat to only modestly recovering global market for appliances and TVs."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Looking Beyond LG Electronics
LG Electronics leans on products that blend function with everyday identity. That mix is not unique.
Another global brand already treats sport, style and daily wear as one habit. It earns money when training gear also feels like casual clothing.
Instead of depending on one region or one activity, it spreads demand across multiple sports and fitness trends. That can support a different kind of resilience.
The open question for you is simple. How does a business built on global fan culture handle margin pressure while still investing in new products and digital experiences?
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 29% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com