
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Brookfield (TSX:BN) Stock Looks Rich As Earnings Face A Tough Test
Brookfield has delivered a strong share price run over the past few years, yet its recent pullback and changing earnings profile put the focus squarely on what investors are paying for each dollar of profit today. With the stock around US$52.65 at the last close and fresh news on distributable earnings, the open question is whether that market price lines up with the strength and quality of its earnings.
- Over the past 3 years the share price has gained about 96.0%, which makes the current earnings multiple especially important for anyone weighing up what is already priced in.
- Management reported a 15% rise in distributable earnings per share and committed around US$580 million to buybacks, which can support earnings per share over time and shapes how you might think about a fair earnings-based valuation.
- Your read on Brookfield is one view; the desks covering it have another. See what analysts think Brookfield's shares could be worth.
The issue now is whether Brookfield's current share price is justified by its earnings when set against the industry average.
If you are weighing Brookfield against other earnings focused ideas, it can help to set it beside companies screened for 4 high quality undervalued stocks.
Does Brookfield Look Pricey on Earnings?
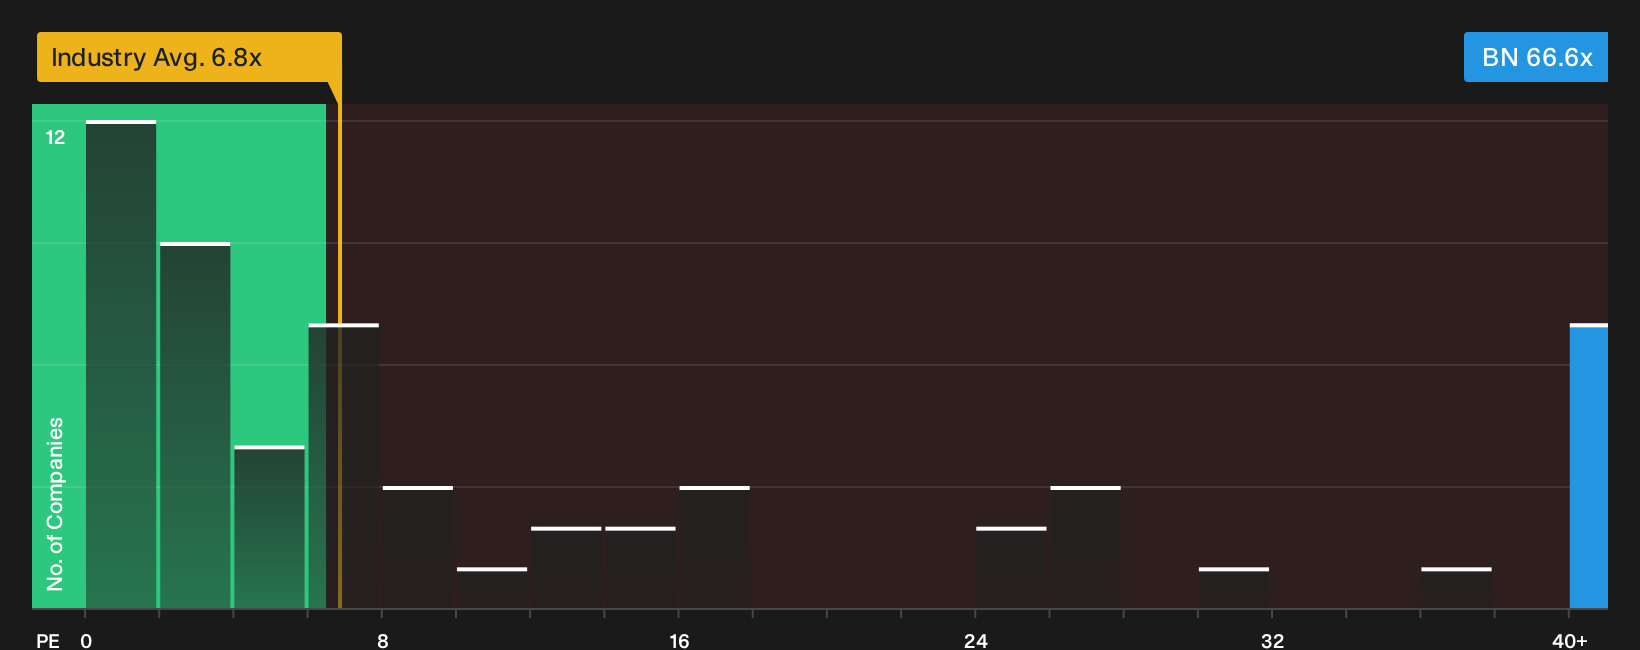
P/E makes sense for Brookfield because management and investors focus heavily on distributable earnings per share. On this metric, the stock trades on a P/E of about 66.6x, which is far above the Capital Markets industry average near 6.8x and also well ahead of the roughly 16.6x peer group level. That gap means every dollar of Brookfield earnings carries a much richer price tag than comparable firms in the same space.
The latest 15% rise in distributable earnings per share and the US$580 million of buybacks help explain some of that enthusiasm, yet the current multiple still screens as overvalued against the industry benchmark. For anyone considering Brookfield, the key question is whether its mix of asset management, insurance and real assets justifies paying such a premium earnings multiple relative to other capital markets stocks. Explore the numbers behind Brookfield's P/E valuation.
The Brookfield Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Brookfield's valuation puzzle leaves off by spelling out which growth, margin and earnings paths would need to play out for the current price to look materially higher or lower over time. Each narrative ties a specific fair value estimate to a clear story about Brookfield's potential catalysts and key risks, so you can track which version of events is gradually unfolding on the Community page.
One of the top community narratives on Brookfield: 36% undervalued
"The return comes from compounding earnings; any narrowing of the discount is the accelerant, not the engine..."
Discover why this Narrative puts Brookfield at 36% undervalued.
Brookfield's valuation is only part of the story
Price tags and earnings multiples tell only one side of Brookfield, while recent research has also surfaced specific business risks that deserve your attention before you form a view. Take a closer look at 2 warning signs (2 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com