
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Microsoft 365 Security Add Ons Altering The Investment Case For Commvault Systems Stock?
- Commvault Systems has rolled out new Microsoft 365 focused add ons called Data Posture 360 and Threat Scan that help customers locate sensitive data, hunt for threats across Exchange, OneDrive, SharePoint and Teams, and restore only clean backups from immutable storage.
- The tools are offered as paid extensions to existing Microsoft 365 backup services, which allows Commvault Systems to generate additional revenue from current deployments rather than relying solely on winning entirely new accounts.
- We will now look at how the Commvault Systems investment narrative might shift as Microsoft 365 threat hunting add ons begin to play a more prominent role.
Commvault Systems Investment Narrative Recap
To own Commvault Systems, you need to believe the business can keep converting rising cyber risk and complex data environments into recurring subscription and SaaS revenue, without letting supply constraints or currency swings sap momentum. The Microsoft 365 security add ons sit within that story, plugging into a very large seat base and deepening Commvault Systems' role in day to day protection.
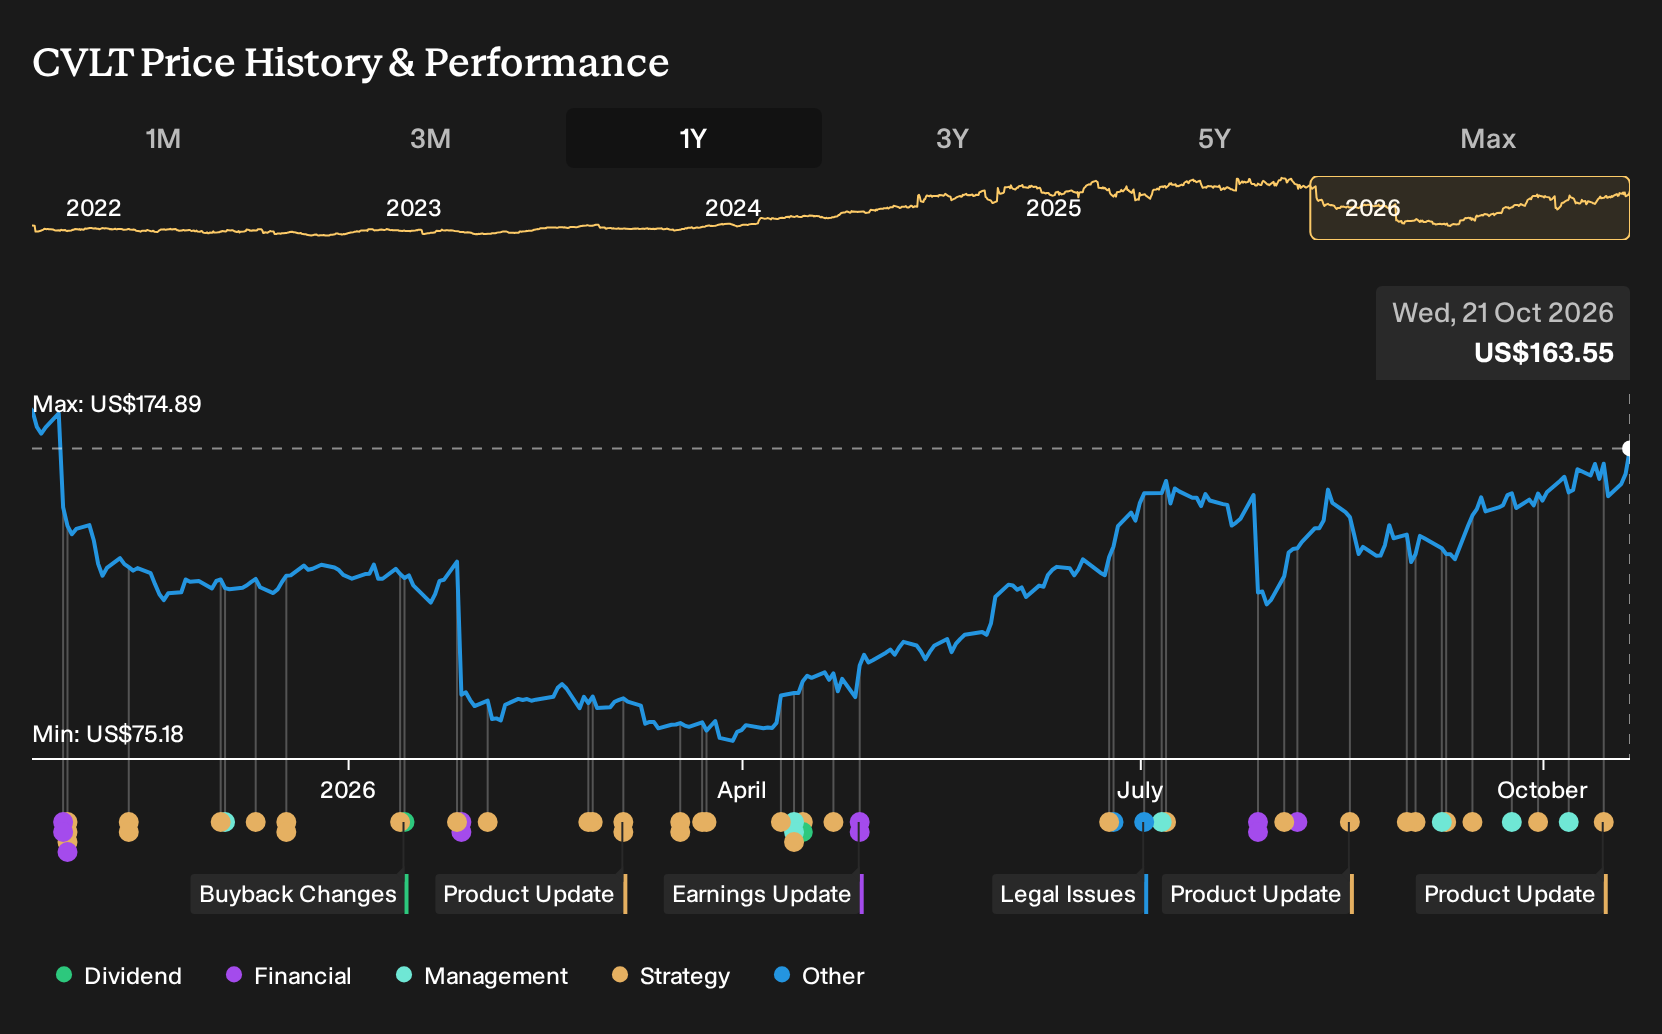
The key near term catalyst remains execution on subscription ARR and SaaS adoption, after management held FY27 ARR guidance at US$1.20b to US$1.21b despite an earlier beat. The biggest immediate overhang is the fiduciary duty investigation, which could influence perception and valuation even if operations track existing guidance.
The most relevant recent move is the launch of Data Posture 360 and Threat Scan as paid add ons to Commvault Backup & Recovery for Microsoft 365. These tools extend the platform from basic backup into ongoing data mapping and threat hunting across Exchange, OneDrive, SharePoint and Teams.
For investors, this matters because it ties subscription ARR more tightly to Microsoft 365 usage and potentially widens the spend per customer, while still carrying clear execution risk. Uptake of these extensions, set for early access soon and general availability targeted for early 2027, will feed directly into how credible current growth expectations look against the cautious guidance backdrop.
Commvault Systems' current analyst story assumes revenue of US$1.6b and earnings of US$167.2 million by 2029, based on 10.7% yearly top line growth and an earnings increase of about US$98.9 million from US$68.3 million today.
Uncover why Commvault Systems' fair value is effectively aligned with its current price.
Exploring Other Perspectives
One alternate view leans hard into Commvault Systems’ AI and identity resilience angle. The most bullish analysts were already pencilling in revenue of about US$1.7b and earnings of US$166.2 million by 2029, well above consensus, and saw the stock justifying a 53.6x P/E. This new Microsoft 365 push could nudge those expectations even higher or test them sharply, depending on how adoption actually plays out.
Explore 3 other Commvault Systems fair value estimates, including one that indicates potential upside of up to 55% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Commvault Systems research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Commvault Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Commvault Systems' overall financial health at a glance.
Looking for more Commvault Systems style investment ideas?
If the Commvault Systems story has you thinking about portfolio gaps, it can help to line it up against other opportunities with clear financial traits using the Simply Wall St Screener.
- For investors who prize balance sheet strength, focus on businesses with low leverage and solid fundamentals using the list of solid balance sheet and fundamentals (25 results).
- If you are hunting for mispriced opportunities, compare Commvault Systems with companies that pair quality metrics and potentially attractive valuations through the 33 high quality undervalued stocks.
- For those building a portfolio around income, see how Commvault Systems stacks up against higher yielding alternatives using the 7 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com