
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Greggs Stock And UK High Street Shares Facing Business Rates Pressure
UK high streets now sit at the crossroads of stubborn 3.5% inflation, war driven energy costs and a possible Bank of England rate hike that could push business rates higher and squeeze bricks and mortar margins. For investors, those pressures can separate fragile stories from resilient operators. This article unpacks three UK retail and hospitality stocks exposed to this rates backdrop, showing where some see pressure and others see potential opportunity.
The three stocks in focus are just a starting sample from this high street rates theme, and the wider screen pulled out 31 more UK retail and hospitality businesses with equally detailed stories that are not covered below. To size up that broader field, identify rate sensitive operators and analyze their fundamentals directly, head straight to the UK High-Street Retail and Hospitality (Business Rates Pressure Plays) screener.
Greggs (LSE:GRG)
Greggs is a high street heavyweight in this business rates theme, with a dense shop network and value focused menu putting it right in the firing line of higher property costs while giving it scale advantages that many smaller rivals cannot match.
Greggs runs a UK wide food on the go chain, generating about £1.95b from company managed shops and £275 million from B2B outlets, supported by its delivery channels, and carries a market value of roughly £2.29b.
"Greggs is actively expanding its store estate into underrepresented high‑convenience channels such as drive‑thrus, retail parks, supermarkets, and transport hubs. These locations align with rising demand for food‑on‑the‑go and busy urban lifestyles, providing significant headroom for future revenue growth without cannibalizing the existing estate."
What really matters next is how one unseen cost pressure interacts with that expansion agenda and filters through to everyday shop level margins.
That margin question is exactly what the full narrative for Greggs unpacks, showing where rates pressure might be masking the next phase of store led growth for Greggs.

Whitbread (LSE:WTB)
Whitbread ties directly into the high street business rates theme because Premier Inn hotels and their adjoining pubs and restaurants rely heavily on UK bricks and mortar. This makes its property decisions and capital spend plan crucial to how future costs and returns play out.
Whitbread runs the Premier Inn and associated restaurant brands across the UK and Europe, generating about £3b from accommodation, food and beverage, and carries a market value of roughly £4.4b.
"The plan to recycle £1.5b of freehold property and shift towards a capital lighter hotel estate is intended to reduce net capex to £200 to £250m a year. This can support future earnings by directing more cash towards projects that aim to lift returns and net margins."
What really matters is how that property reshuffle interacts with UK rate moves and one key cost pressure that could reshape future profitability.
That hidden cost pressure is exactly what the full narrative for Whitbread pulls apart, showing where rates risk might be masking an accelerating earnings story for Whitbread.

Mitchells & Butlers (LSE:MAB)
Mitchells & Butlers runs a large estate of UK pubs, bars and restaurants under brands like Harvester, Toby Carvery and All Bar One, putting it squarely in the business rates theme. It generated about £2.75b from operating pubs, bars and restaurants and carries a market value of roughly £1.86b.
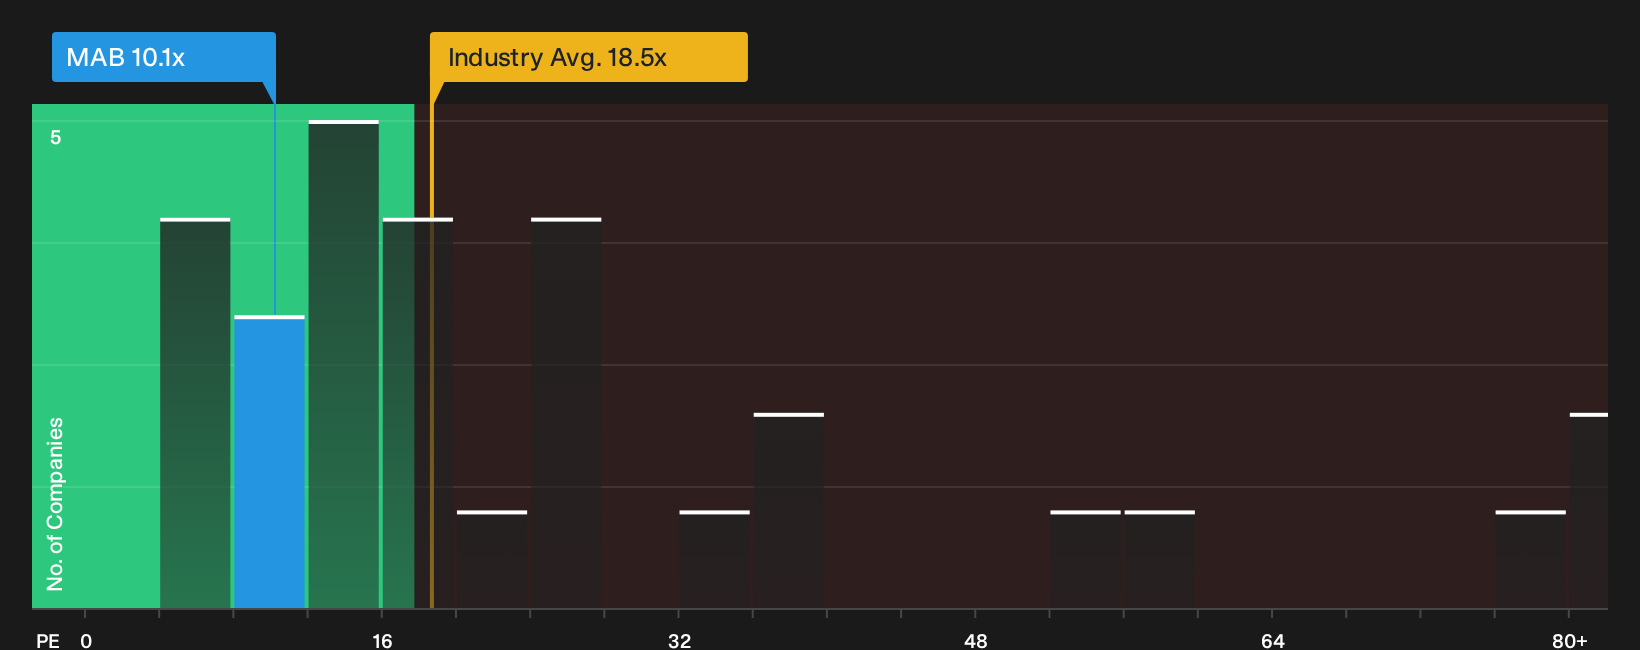
Mitchells & Butlers offers something rare in a high street heavy operator. The group has a big UK pub and restaurant footprint exposed to rising business rates, yet trades on a P/E of 10.1x. The real swing factor is what happens if one unseen pressure on those pub level margins keeps building.
If that margin squeeze is the real swing factor, the analysis report for Mitchells & Butlers shows where Mitchells & Butlers could be mispriced before sentiment catches up.
Seeking Alternatives Before The Crowd?
Fresh opportunities can move from quiet to flying under new momentum before most investors even look up. Scan what others may miss while it still matters and get in early.
- Spot potential breakouts among smaller businesses that already generate cash and are not just burning runway by checking the 38 profitable AI stocks that aren't just burning cash.
- Track companies aiming to ride long term demand for critical metals before sentiment fully catches up by reviewing the 33 best rare earth metal stocks.
- Target strong balance sheets and cleaner fundamentals so short term noise does not dominate the story by using the list of solid balance sheet and fundamentals (9 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com