
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Celestica (TSX:CLS) Could Be 38% Undervalued After Its New AI Switch Launch
Celestica (TSX:CLS) has put its AI data center ambitions on display with the new DS6005 switching system, introduced alongside its appearance at the OCP Global Summit 2026 in San Jose.
Recent enthusiasm around Celestica’s AI data center hardware comes against a mixed price backdrop, with the share price at CA$428.26 after a 1-day share price return of 1.43% but a 30-day share price return that declined 11.35% as some investors reassess near term risk. Even with that pullback, the 1-year total shareholder return of 13.06% and a very large 3-year total shareholder return above 10x indicate that long term holders have already captured substantial gains, so the current consolidation appears to be a pause in the broader AI driven narrative rather than a clear reversal.
Scan beyond Celestica and size up other AI infrastructure plays by checking the hand picked 55 AI infrastructure stocks that are geared toward the same build out theme.
Celestica now sits in a tricky pocket, fresh off a sharp pullback yet still carrying big multi year gains for early holders. Should investors wait for a deeper reset or start considering the stock today?
Most Popular Narrative: 38% Undervalued
Against the last close of CA$428.26, the most followed narrative puts Celestica's fair value at CA$694.93, so the current wobble looks more like valuation compression than a thesis break.
Accelerated demand for advanced networking and AI infrastructure by hyperscaler customers is driving rapid growth in Celestica's CCS segment, with multiple new 800G and upcoming 1.6T program ramps, supporting robust revenue expansion and greater operating leverage over the next 12 to 24 months. Widespread digital transformation initiatives and technology transitions (AI/ML compute, next-generation racks) across hyperscalers and digital native customers are expanding Celestica's design pipeline and deepening customer engagements, which increases revenue visibility and improves per-customer revenue potential.
See why 176 investors see Celestica as 38% undervalued.
Result: Fair Value of CA$694.93 (UNDERVALUED)
Still, Celestica’s dependence on a handful of hyperscaler customers, along with execution risk around new 800G and 1.6T programs, could quickly challenge that undervalued thesis.
Find out about the key risks to this Celestica narrative.
Another View On Celestica’s Valuation
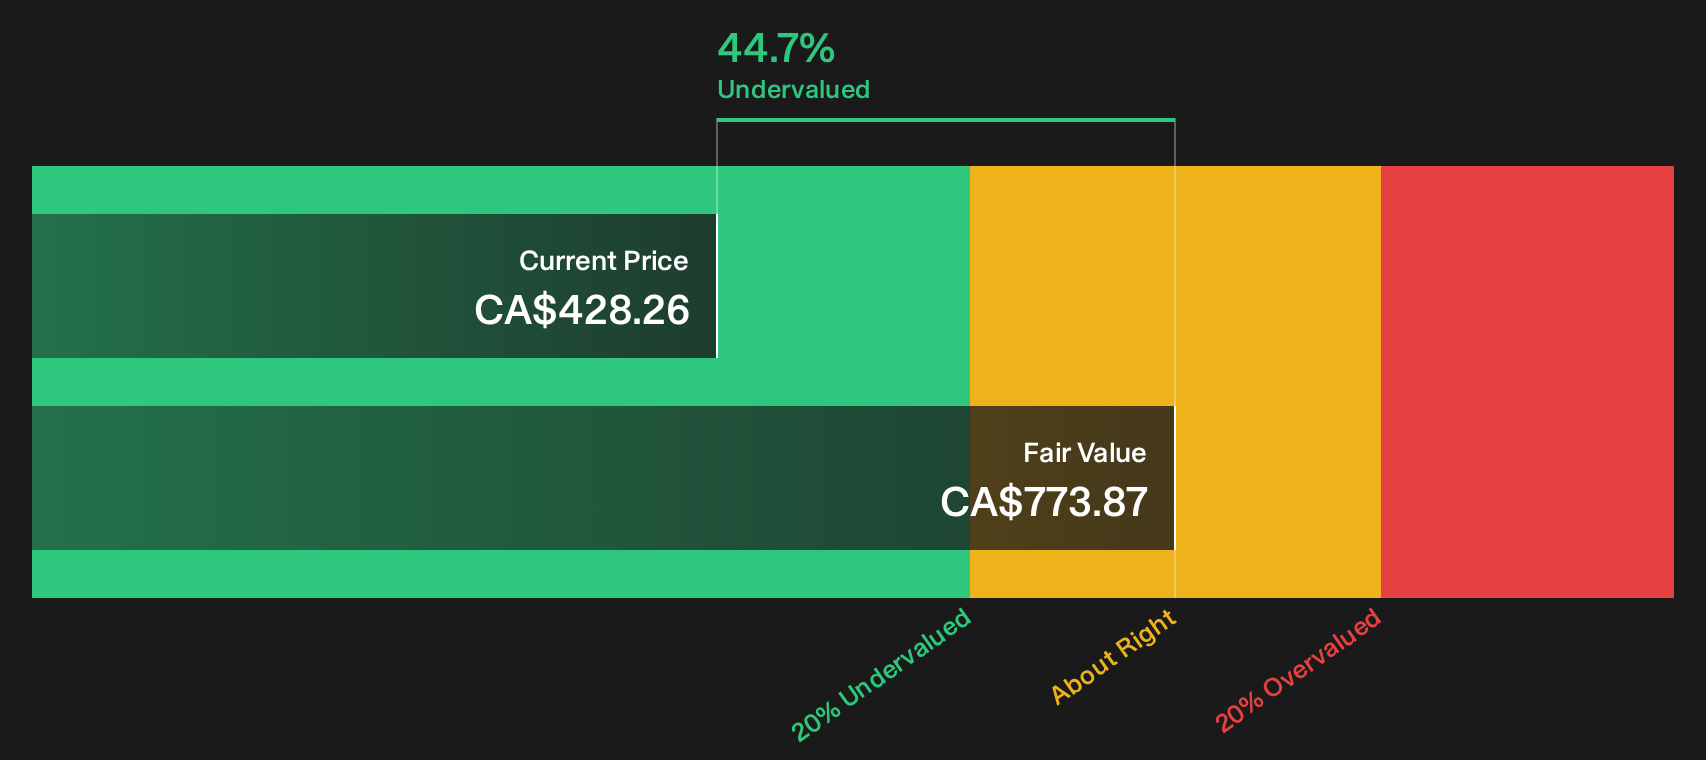
The SWS DCF model points to a fair value of CA$773.87 per share, compared with Celestica’s current CA$428.26 price. This suggests the stock screens as materially undervalued using projected cash flows. That is a wider gap than the analyst fair value of CA$694.93. Which framework do you trust more for a long term call?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed sentiment on Celestica is clear, with both concerns and bright spots on display. Move quickly, review the full data set yourself, and weigh the 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Celestica?
If Celestica has sharpened your focus on where capital could work harder, broaden your search now so you are not relying on a single opportunity.
- Target potential mispricings by scanning a curated pool of fundamentally strong companies through the 4 high quality undervalued stocks.
- Strengthen portfolio resilience by filtering for businesses with cleaner finances using the focused list of solid balance sheet and fundamentals (7 results).
- Get ahead of the crowd by reviewing the 10 high quality undiscovered gems that pair quality metrics with relatively limited market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com