
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Aritzia (TSX:ATZ) Investor Day Puts Its Growth Story And Valuation Back In Focus
Aritzia (TSX:ATZ) is heading into its October 27 Investor Day with fresh momentum after reporting second quarter sales of CA$1,169.81 million and net income of CA$201.69 million on October 8.
Investors have been leaning into that story, with Aritzia’s 1-month share price return of 22.61% and year to date share price gain of 31.30% feeding into a very strong 1-year total shareholder return of 67.44% and a multi year total shareholder return that is several times the original investment. This points to momentum that recent earnings, buybacks and fresh board experience appear to be keeping firmly intact.
Capitalize on the momentum around Aritzia's Investor Day by scanning a curated 10 high quality undiscovered gems that could be setting up for similar attention.Aritzia has already rewarded early believers. The recent surge, however, only sharpens the real fork in the road. Is most of the upside already booked, or does the current valuation still leave meaningful room ahead?
Most Popular Narrative: 15% Undervalued
The most followed narrative pegs Aritzia’s fair value at CA$181.93, above the last close of CA$153.86. This puts recent strength in a different light ahead of Investor Day.
Aritzia's ongoing U.S. boutique rollout, with new locations reportedly paying back in under one year and management indicating room to expand from roughly 76 to 82 to at least 180 to 200 boutiques, points to a continued store-led uplift to net revenue.
Further growth of digital revenue, which reached $403 million in Q2 fiscal 2027 with a higher mix of total sales, and deeper adoption of the mobile app that accounts for about 30 to 34% of digital sales, can keep lifting overall revenue and support operating leverage.
See why 67 investors see Aritzia as 15% undervalued.
Result: Fair Value of CA$181.93 (UNDERVALUED)
Still, the bullish Aritzia story can wobble quickly if U.S. tariffs climb toward 20% or if new American boutiques see weaker productivity than analysts expect.
Find out about the key risks to this Aritzia narrative.
Another View: Aritzia Looks Expensive On Earnings
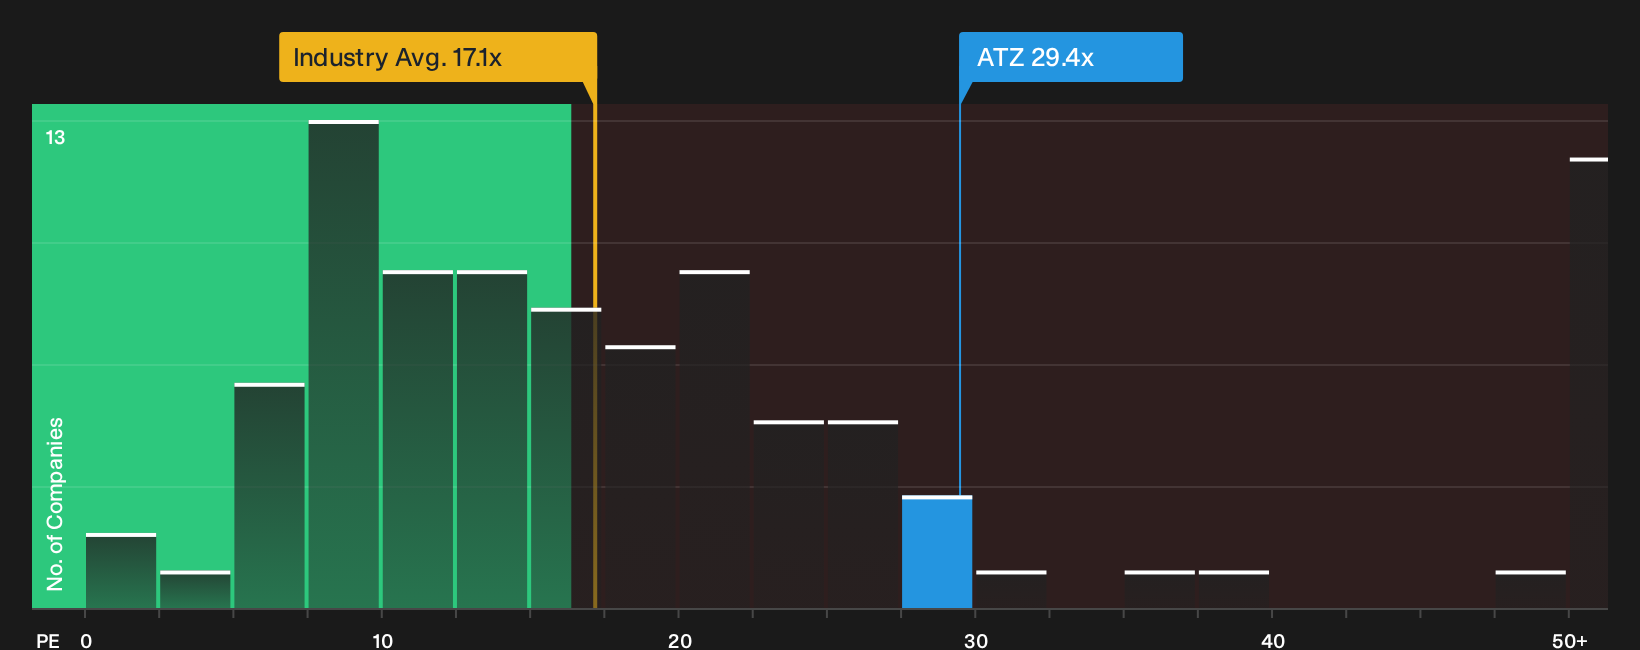
The analyst target pegs Aritzia at a 15.4% discount to fair value, yet the current P/E of 29.4x is above both its fair ratio of 26.6x and the North American Specialty Retail average of 17.1x. That richer multiple can reward believers if growth stays on script, but it also raises the question of how much margin for error is left.
For a closer look at how that earnings multiple stacks up across peers and where the fair ratio suggests the market could drift over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of enthusiasm and caution around Aritzia feels familiar, take action while the data is fresh and weigh the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Aritzia?
Do not stop with a single ticker when a broader watchlist could surface opportunities that fit your style and risk tolerance far better.
- Target potential mispricing by scanning a focused pool of quality candidates through the 4 high quality undervalued stocks.
- Build staying power into your holdings by reviewing a list of solid balance sheet and fundamentals (7 results).
- Identify dependable income streams by screening for 3 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com