
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What DCC Energy Holders Bought Into
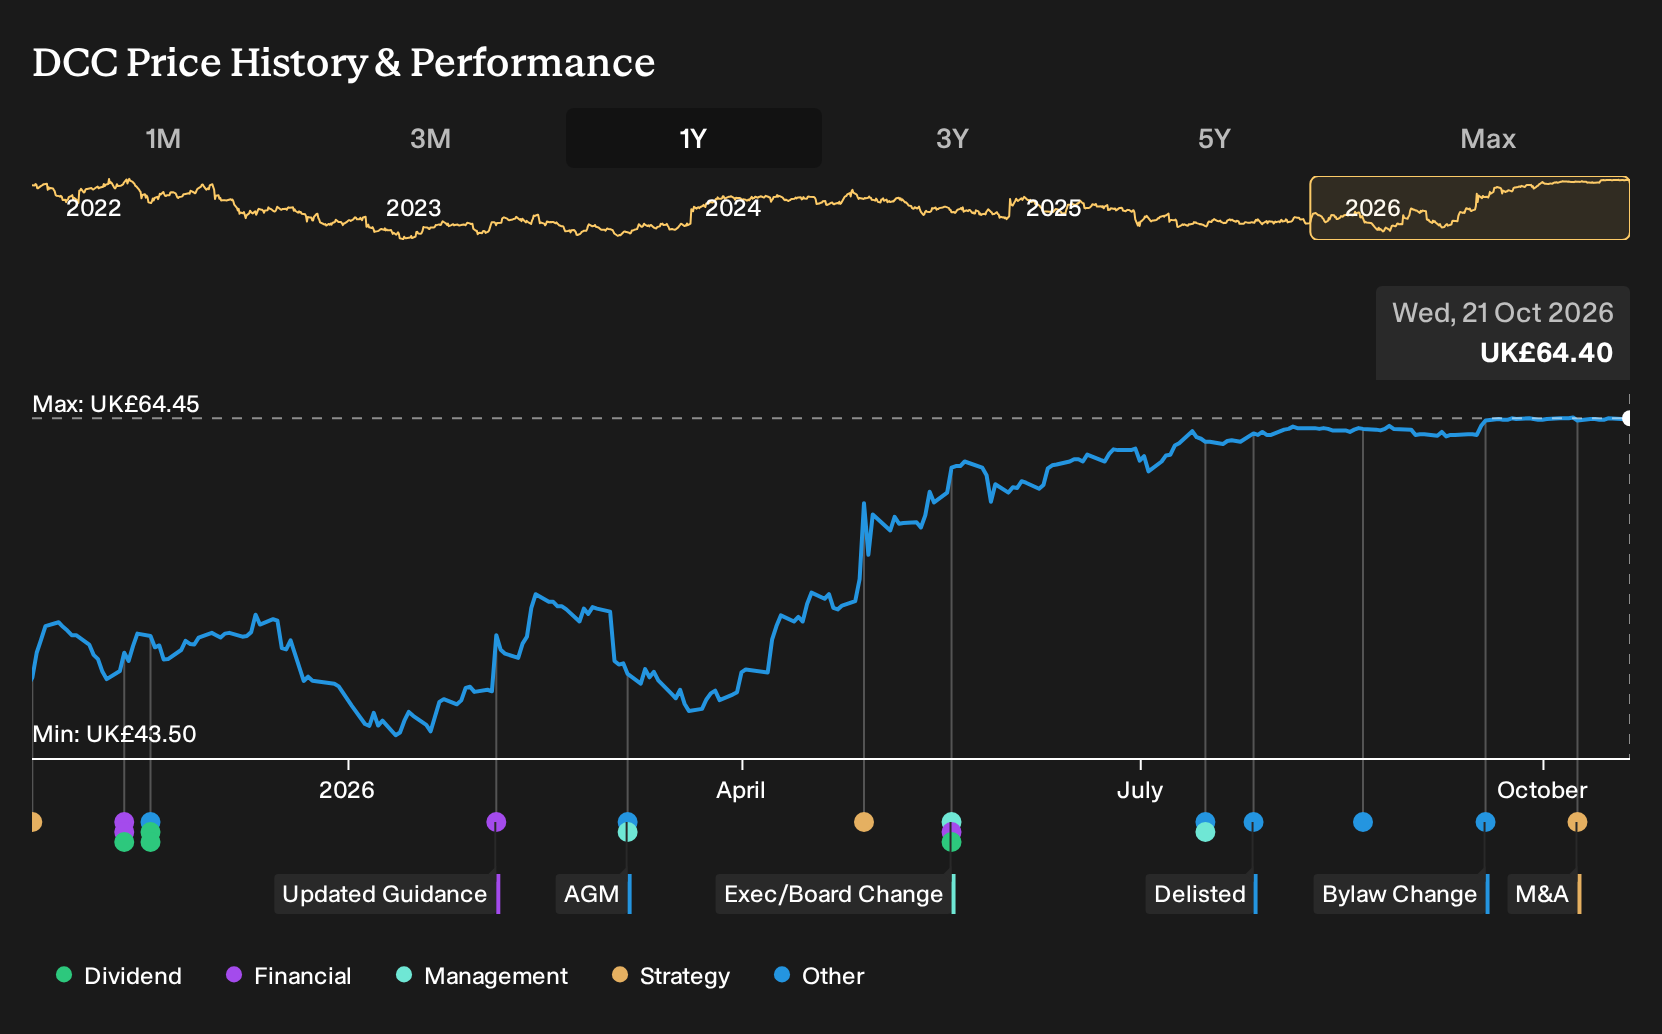
If DCC Energy was on your watchlist rather than in your portfolio, the result may feel like a missed swing. Investors who held DCC Energy over the past year are up 36.8%, including dividends. That outcome sits against a backdrop where one side expected cleaner fuels and solar solutions to lift the Energy arm, while others worried legacy hydrocarbons would shrink. If you roll the clock back to October 2025, how could you have weighed that bet on concentrating the whole group around Energy?
The easy part of this move is behind DCC Energy. Zero in on 6 high quality undervalued stocks for companies trading below our estimates.
The Two Competing Stories Around DCC Energy
The shares cost £47.3 at the start of the period, and anyone weighing up DCC Energy then had to decide which future seemed more realistic for a focused Energy group.
On the optimistic side, the cleaner energy story pointed to a Fair Value of £62.65. This price would only make sense if expansion in biofuels, liquid gas and solar solutions successfully shifted the group toward more stable, recurring earnings.
The more cautious view anchored on a Fair Value of £44.91. This view assumed legacy hydrocarbon activities in mature markets would face declining demand, while higher compliance costs and extra capital spending for greener services would pressure profitability.
What The Evidence Did To The DCC Energy Argument
DCC Energy received a €6.67b buyout offer from a KKR led consortium and moved to sell its Nexora technology arm, which backed the cleaner energy focus in the optimistic case. H2 2026 results gave another data point. Revenue reached £8,061.2m and net income was £276.2m, with net margin at 3.4%. The evidence cut both ways.
The key assumption here was that a pure play energy focus would translate into higher, more resilient profitability. For a different stock, you would track net margin alongside any portfolio reshuffle to see whether divestments and new deals actually improve earnings quality.
What DCC Energy’s Price Already Assumes
DCC Energy now trades at £64.4, after a 36.8% gain over the past year. The selected Narrative’s Fair Value sits below that level, which implies its authors see the current quote already baking in a lot of good news.
The Narrative centres on how far the pure play structure, cash generation and balance sheet can fund disciplined consolidation. A buyer at today’s price has to judge whether DCC Energy can keep turning that firepower into solid returns while Energy Services projects and liquid fuel volumes remain harder to predict.
"The main thing that has to go right is for DCC Energy to convert its simplified pure play structure, strong free cash flow and balance sheet headroom into value accretive consolidation of fragmented liquid gas and multi energy markets, while growing higher margin Mobility and energy transition services despite recent headwinds."
The price and this Narrative do not agree. → Uncover what this Narrative says DCC Energy is actually worth
Another Step In The Energy Chain
DCC Energy narrows your focus onto cleaner fuels and services. Yet the wider energy world still relies on something more basic.
Every cleaner project, whether gas, biofuel or power, still needs dependable supply and trading of molecules and electrons.
One large integrated group leans into that task, linking hydrocarbons, liquefied gas and electricity so customers can keep energy flowing.
It pursues lower emission projects and power generation, aiming to keep cash coming in even when commodity prices swing.
If that mix keeps shifting toward power and lower carbon fuels, the role of a traditional producer can start to look very different.
One Narrative has already put a figure on it. → Uncover the company trading 19% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com