
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
DFI Retail Group Holdings (SGX:D01) Following Board Changes And AI Push Faces Valuation Questions
DFI Retail Group Holdings (SGX:D01) has become a talking point after fresh board appointments and lingering questions about whether its current share price lines up with discounted cash flow estimates.
Despite fresh board appointments and management talking up digital and AI projects, DFI Retail Group Holdings’ recent price action has been mixed, with a 30 day share price return of 4.66% and a year to date share price decline of 14.25%.
Scan how DFI Retail Group Holdings compares with other retailers being priced for a potential reset in expectations by reviewing our hand-picked 190 high quality undervalued stocks.
Recent gains after a weak start to the year leave DFI Retail Group Holdings at an awkward crossroads. Are investors now paying up for genuine business strength, or for a swing in sentiment that the cash flow math does not fully support?
Most Popular Narrative: 34% Undervalued
On the most followed narrative, DFI Retail Group Holdings screens as undervalued, with a fair value estimate of $5.11 against a last close of $3.37, and that gap is being pinned on how its future earnings mix and digital push are modeled.
The group is aggressively expanding its higher-margin Health & Beauty and Ready-to-Eat (RTE) convenience food offerings, in response to growing demand for health-conscious and premium products among Asia's expanding middle class; this product mix shift supports higher net margins and improved top-line growth.
Strategic investments in direct sourcing, private label (Own Brand) development, and a broadened supply chain are enabling lower input costs, allowing DFI to invest in price while still protecting gross margins and improving profitability in competitive core markets, a long-term operational lever for enhanced earnings.
See why 8 investors see DFI Retail Group Holdings as 34% undervalued.
That valuation story uses a 7.20% discount rate and arrives at fair value of $5.11, which sits well above the current $3.37 share price. The model leans on margin assumptions, product mix shifts and capital allocation choices rather than simple multiples or short term trading moves.
Result: Fair Value of $5.11 (UNDERVALUED)
Still, the bullish DFI Retail Group Holdings story runs into real friction if cigarette driven traffic in convenience stalls further or if price competition in online channels continues to pressure margins.
Find out about the key risks to this DFI Retail Group Holdings narrative.
Another View: Cash Flows Point The Other Way
A different lens on DFI Retail Group Holdings comes from the SWS DCF model, which puts future cash flow value at $2.89 per share against the current $3.37 price. On this framework, the stock screens as overvalued. If earnings execution wobbles, does the cash flow math start to matter more than the multiple story?
Look into how the SWS DCF model arrives at its fair value.
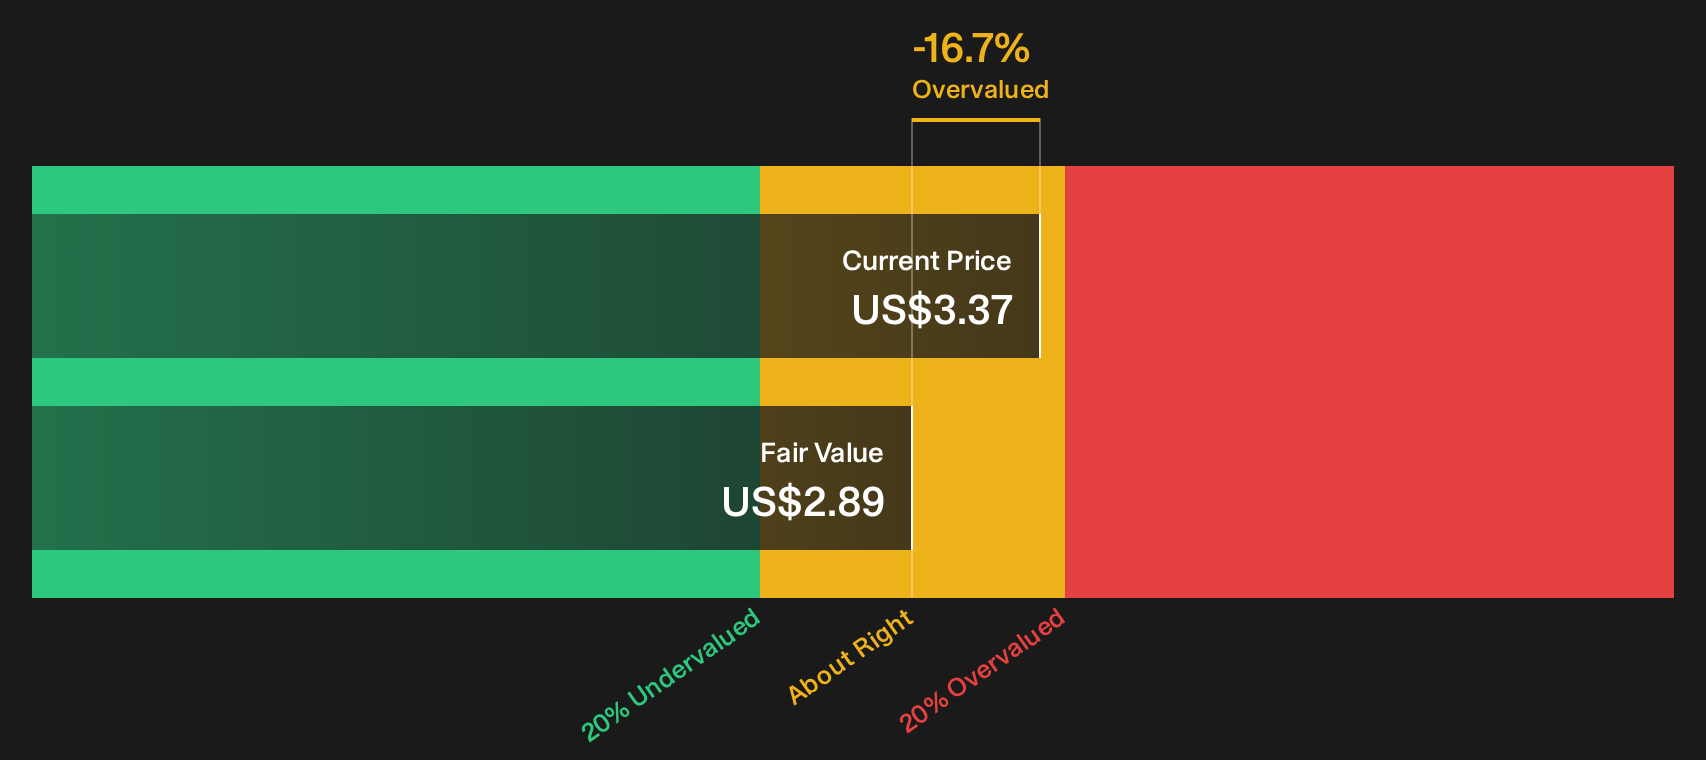
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out DFI Retail Group Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 190 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around DFI Retail Group Holdings can either paralyze you or push you to inspect the numbers yourself and decide where you stand. If you want to weigh the concerns against the potential upside in a single place, start with these 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond DFI Retail Group Holdings?
If you only focus on DFI Retail Group Holdings, you might miss other compelling opportunities sitting in plain sight across the market right now.
- Target potential mispricings by scanning a curated pool of quality opportunities through the 190 high quality undervalued stocks.
- Identify income-focused ideas that align with your need for yield and staying power with the 218 dividend fortresses.
- Prioritize resilience and sleep-at-night holdings by filtering for companies on the 229 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com