
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
OFG Bancorp (OFG) Stock Price Drops Despite Resilient Q3 Earnings
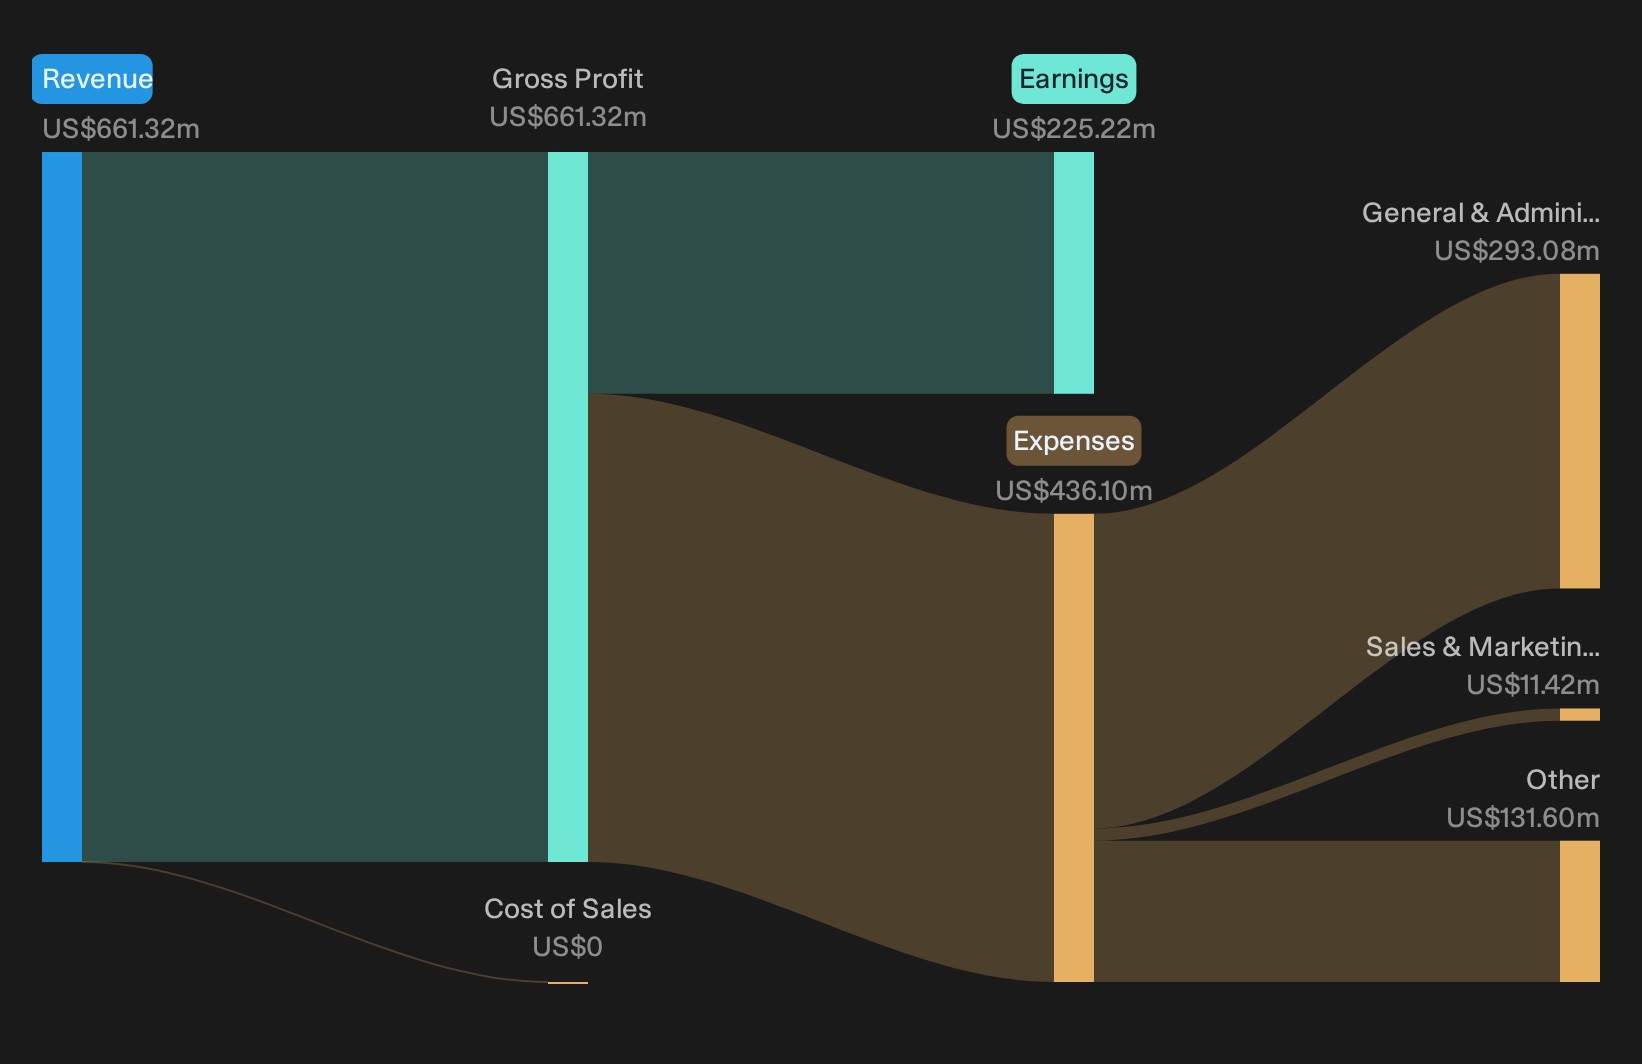
The market fired first, then asked questions. OFG Bancorp dropped about 4.6% to US$50.50 the day after releasing Q3 2026 figures, even though earnings per share landed near US$1.34 and net income reached about US$56.6m. That is not a collapse in profitability for a regional bank. The real story sits in sentiment. Traders focused on a softer top line and headline revenue of roughly US$168.1m, while largely ignoring an earnings profile and net margin trend that present a picture of resilience compared with what the price move suggests.
Like the earnings power at OFG Bancorp but uneasy about the market's quick reaction to softer revenue? Consider using the solid balance sheet screener to compare this move against a broader list of solid balance sheet and fundamentals stocks (25 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$168.1m vs. US$157.9m (up about 6.5%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$56.6m vs. US$51.8m (up about 9.2%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.34 vs. US$1.17 (up about 14.8%)
- Net Margin (Trailing 12 Months vs. Prior Year): 34.1% vs. 32.0% (indicating improved profitability on recent earnings)
Ask Charlie what OFG Bancorp’s AI push means for growth.
OFG Bancorp: Bull Case Meets Hard Data
Bulls argue that OFG Bancorp can turn digital engagement and a Puerto Rico focused franchise into durable earnings and capital return power.
"Strong adoption and expansion of digital banking channels are driving increased customer engagement and facilitating operational efficiency, with recent 11% growth in active digital users and rising digital transaction usage supporting potential future improvements in operating expenses and net margins."
Q3 shows this thesis has traction. An efficiency ratio near 52% pairs with higher net margin on a trailing 12 month view, while EPS and net income both grew faster than revenue. Management is also confident enough to resume buybacks, with US$13.5m repurchased and US$180m still authorized.
Risks To OFG Bancorp’s Margin Story
Bears worry that funding costs and loan mix will quietly chip away at that digital and capital return story.
"Several independent analyses point to projected declines of about 2.1% to 2.2% in net interest income over the next 12 months following a roughly 59 basis point drop in net interest margin over the last two years due to pricing concessions to defend market share. If this pressure persists it could weigh on revenue growth and overall earnings even if loan volumes remain healthy."
Recent results only partially ease that concern. NIM sits at 5.23%, slightly below the 5.45% referenced earlier, and loan yields softened after a one off prepayment boost. Core deposit costs continue to edge higher, while auto balances and production are already under pressure.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Hunt For Mispriced Earnings Power
OFG Bancorp shows how a single quarter can trigger a sharp reaction even when profitability appears intact. The real opportunity could be finding stocks that look mispriced before sentiment adjusts.
- Company 1 - 50% below our estimate - uses a dense store network, app ordering and rapid menu testing to convert heavy operating spend into stickier, higher value coffee habits.
- Company 2 - 40% below our estimate - channels heavier investment in payments technology, AI tools and niche deposit platforms into fee-driven banking relationships that deepen as clients scale.
- Company 3 - 39% below our estimate - turns government-backed trade-in incentives and rising demand for recommerce into higher margin device refurbishment volumes across its resale channels.
That is three of the list. See all 33 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com