
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Markel Group (MKL) Could Be 4% Below Fair Value After New Contractors Push
Markel Group (MKL) has introduced a Contractors & Trades sector within Markel Insurance, targeting brokers that serve contractors and specialist construction firms. The launch combines bundled casualty, property and specialist coverages into one coordinated package.
Recent trading has been choppy for Markel Group, with the share price down 12.13% year to date despite a 5.48% 1 month share price return and a 4.16% gain over the past week. Longer term total shareholder returns of 28.07% over three years and 43.77% over five years point to a sturdier multi year record and suggest this kind of product expansion could be read as a test of whether momentum can rebuild from here.
Scan other insurance and construction exposed opportunities moving on similar themes with our curated list of solid balance sheet and fundamentals (25 results) for a tighter, fundamentals first comparison set focused on Markel Group.
Markel Group now trades about 4% below the average analyst target and at a much larger discount to one intrinsic value estimate. As the recent gains fade into the wider year-to-date decline, which anchor looks closer to fair value?
Most Popular Narrative: 4% Undervalued
On the most followed view of Markel Group, a fair value of $1,956.33 sits modestly above the last close at $1,871.94, so the debate shifts to whether the operating model can justify that gap.
The ongoing build out of AI enabled underwriting and operations, including the launch of the Cortex casualty unit, the rewiring of six classes of business with Agentic AI and the internal AI accelerator fund, is already shortening underwriting cycle times and is expected to support higher quote volumes, better loss ratios and a more attractive expense ratio, which would benefit both revenue and net margins.
See why 19 investors see Markel Group as 4% undervalued.
Result: Fair Value of $1,956.33 (UNDERVALUED)
Still, the Markel Group story can crack if legacy reserves flare up again, or if the reorganization and AI rollout introduce more execution mistakes than benefits.
Find out about the key risks to this Markel Group narrative.
Another View: Cash Flows Point The Other Way
While the consensus narrative frames Markel Group as about 4% undervalued on earnings based fair value, the SWS DCF model presents a very different picture. On that lens, MKL at $1,871.94 trades well above an estimated future cash flow value of $1,332.10, which signals an overvalued outcome instead. For investors weighing both signals, the key question is which matters more right now: nearer term profit power or long term cash generation potential?
For a closer look at how this cash flow view is built and what would need to change for it to shift, Look into how the SWS DCF model arrives at its fair value..
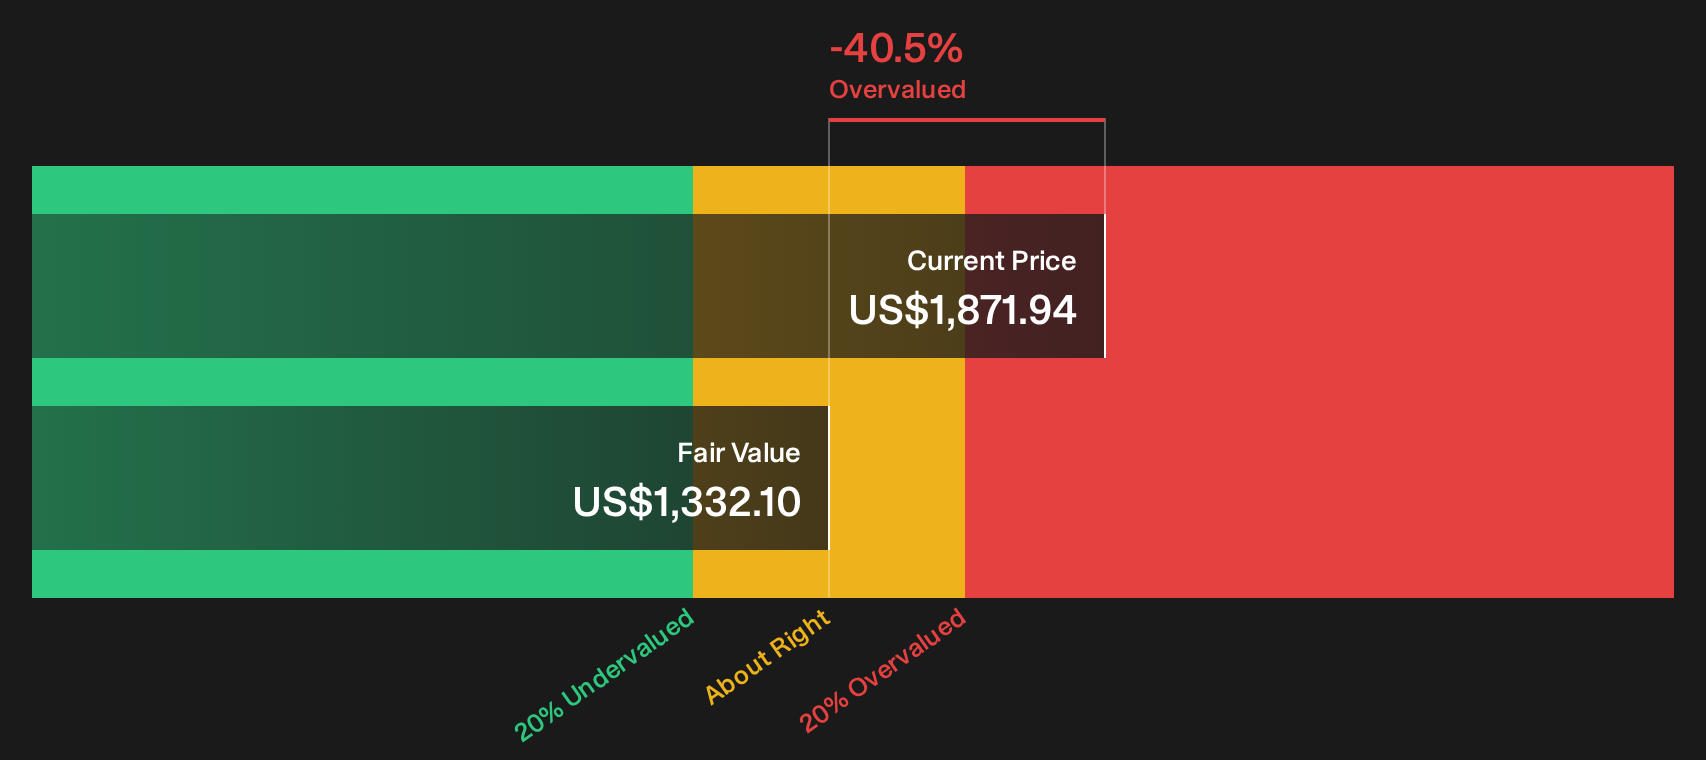
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Markel Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Markel Group so far. If you want to move fast and anchor your own view in the numbers, start with the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Markel Group?
Markel Group gives you a detailed case study, but your portfolio benefits when you line it up against other high quality opportunities found through focused screeners.
- Target resilience first by scanning companies with strong finances and clean balance sheets through the list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced quality and compare Markel Group with a curated pool of 33 high quality undervalued stocks that pair fundamentals with appealing entry prices.
- Spot potential future winners early by reviewing a tightly filtered set of 21 high quality undiscovered gems that many investors may still be overlooking.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com