
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Investors Got Wrong About Nexteer Automotive Group Before The Drop
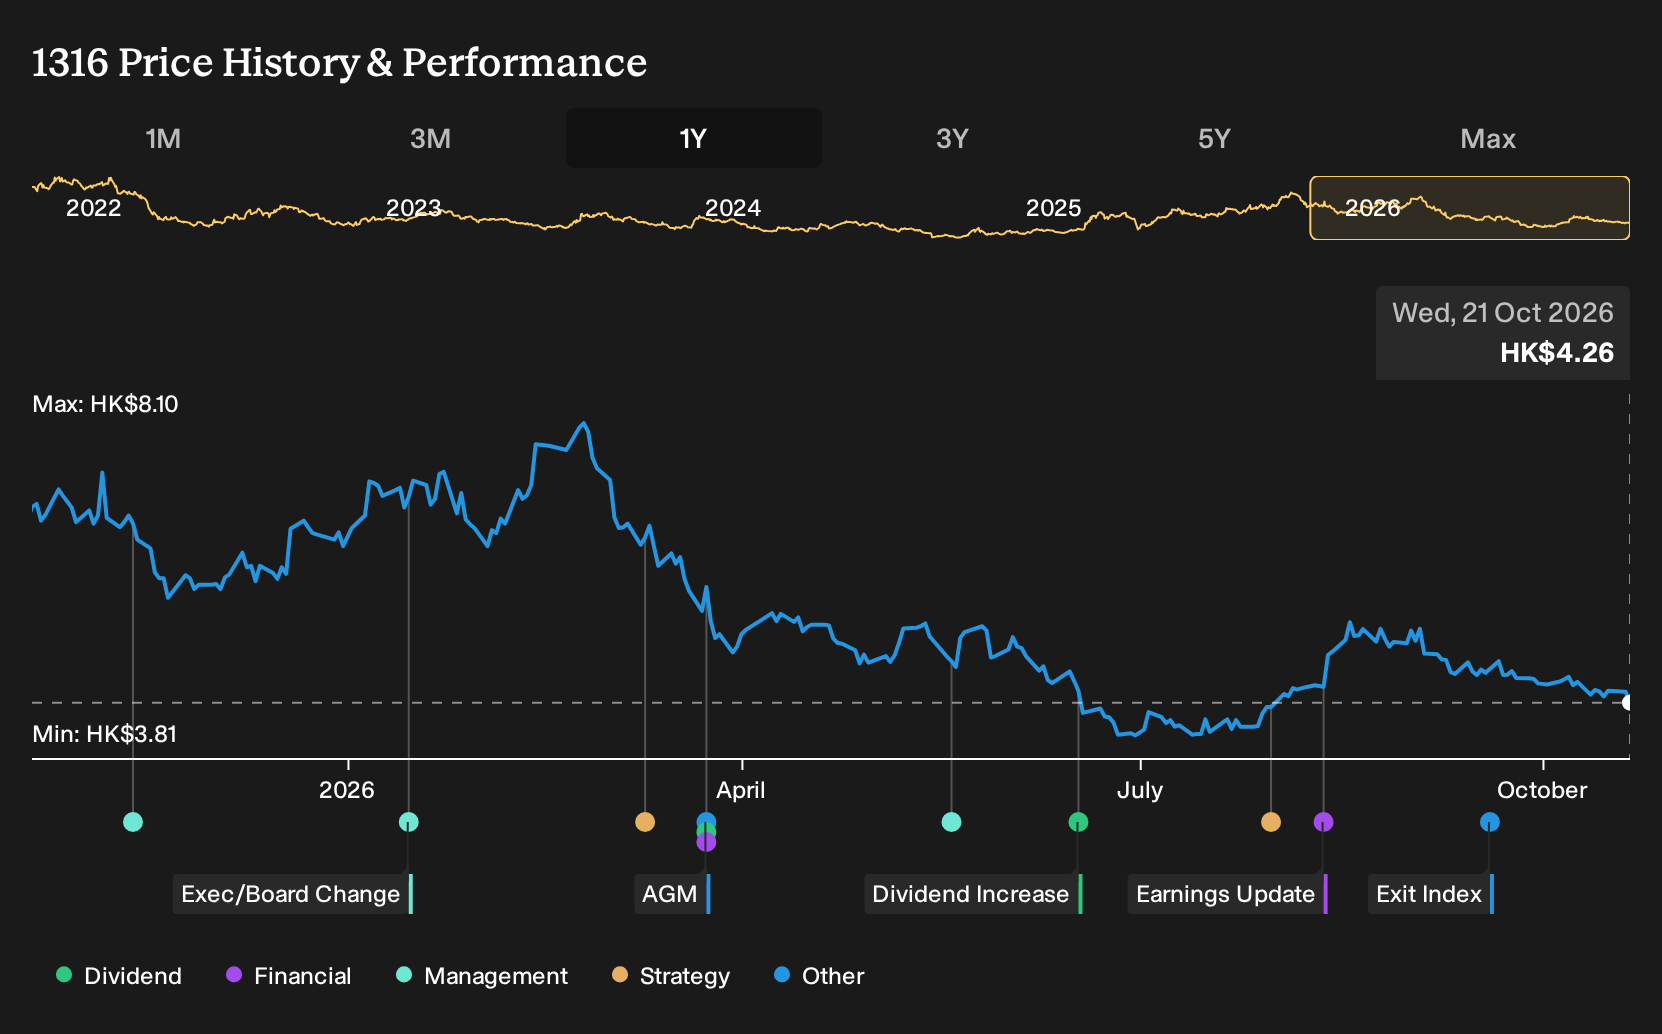
If you only glanced at Nexteer Automotive Group’s recent headlines, the story might look straightforward. Record bookings, new steer-by-wire launches in Chinese NEVs, and a growing APAC footprint sound like the kind of progress long term holders hope for. Investors who held Nexteer Automotive Group over the past year are down 36.9%, including dividends. If you were weighing a purchase a year ago, what clues were on record that this gap between business progress and share price could open up?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
If the move has made Nexteer Automotive Group harder to judge, start where the gap is still open and scan 190 high quality undervalued stocks.
The Two Nexteer Automotive Stories Investors Had To Price
The shares cost HK$6.95 at the start of the period, which meant anyone considering Nexteer Automotive Group had to choose which future felt more realistic.
On the upbeat side, the APAC expansion and electrification narrative put Fair Value at HK$7.72, or 11% above the start price. This scenario assumed 4.4% annual revenue growth and profit margins reaching 3.5% as by-wire and software systems gained traction.
The cautious view pointed to a Fair Value of HK$5.02, or 28% below the start price. It focused on risks such as shifting EV demand, customer concentration, and rising supply chain and regulatory pressure on margins.
What The Results Changed For Nexteer Automotive
Nexteer Automotive moved its steer-by-wire story from slide deck to factory floor as production launched in a Chinese NEV alongside record H1 2026 revenue of US$2,328.8m and net income of US$85.8m. Net margin reached 3.7%, above both the bullish and bearish 2025 starting point assumptions. The evidence therefore leaned toward the optimistic case on profitability.
The hinge assumption was whether higher tech content would show up in margins. When you assess another supplier, compare claimed content-per-vehicle gains with reported net margin over several periods rather than focusing only on headline bookings.
What Nexteer Automotive’s Lower Price Asks You To Believe
Nexteer Automotive Group now trades at HK$4.26, well below where it sat a year ago. The selected Narrative’s Fair Value sits above the current price and leans on balance sheet strength, Motion by Wire exposure and APAC cash generation to argue that today’s quote may not fully reflect those supports.
If you are weighing that view, the key question is whether Nexteer Automotive can keep turning Motion by Wire awards and APAC growth into durable, higher margin earnings while commodity costs, EV program hits and higher payouts stay manageable enough for the fall to look like an opportunity rather than a warning.
"The current numbers on revenue outperformance, EBITDA margin, free cash flow and net cash imply a share price that does not fully reflect Nexteer Automotive Group’s balance sheet strength, margin trajectory and Motion by Wire optionality."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Looking One Step Beyond Nexteer
Nexteer Automotive keeps pointing you toward Motion by Wire and software rich vehicles. That shift raises a different question about where value collects.
If cars become rolling computers, someone needs to supply the digital brains. Another business is betting that physical machines will rely on its AI hardware and software stack.
This group is not just chasing car sales. It is trying to sell intelligence that can move through vehicles, robots and energy systems.
The interesting part for you is the link between that AI push and Nexteer’s world of motion control. If more work and transport rely on autonomous systems, whose platform gets paid for every extra mile and task?
One Narrative has already put a figure on it. → Uncover the company trading 42% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com