
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Dear Spotify Stock Fans, Mark Your Calendars for October 22
Keep an eye on Spotify (SPOT). On Thursday, Oct. 22, before the market opens, the company will post third-quarter earnings. Wall Street is looking for EPS of between $2.86 and $3.26 on revenue of between $5.58 billion and $5.65 billion. Making the stock even more attractive, it ended its prior quarter with 300 million Premium subscribers, up 9% year over year. Monthly users in its second quarter grew 12% to 777 million. Gross margins hit a record high of 33.4% as well. For its most recent quarter, it expects to see 305 million Premium subscribers and 788 million monthly active users. However, guidance calls for margins of 32.9%, a number that investors should pay very close attention to.
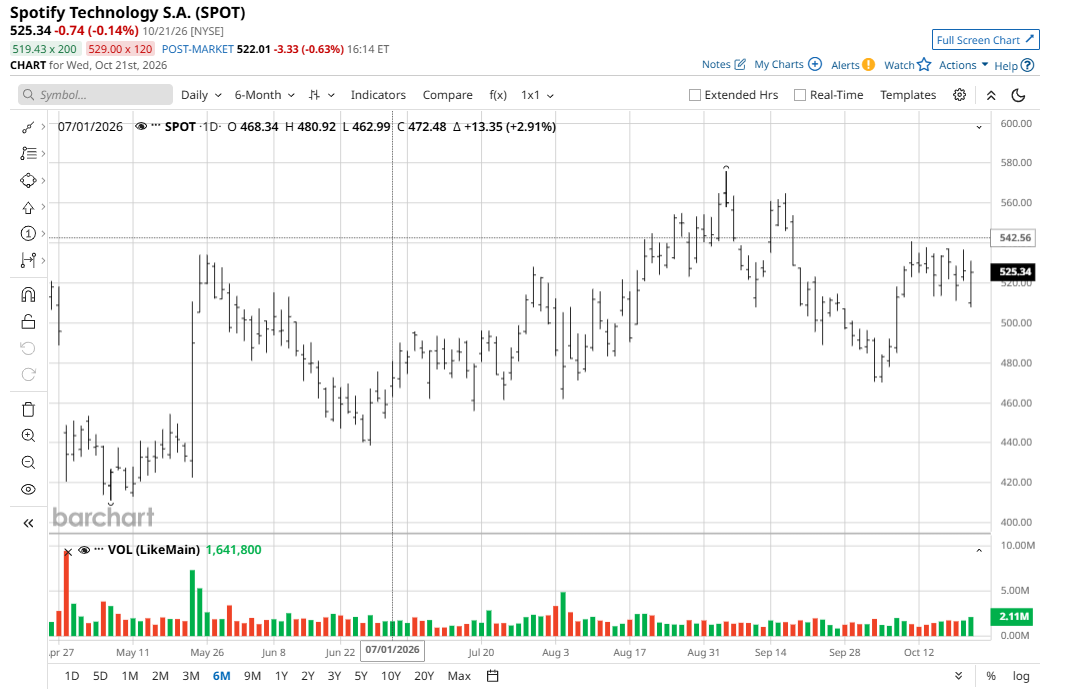
While We Wait on Margin Growth, Analysts Are Bullish
Fueling excitement, Morgan Stanley just reiterated its “Overweight” rating on the stock with a price target of $640. The firm cited the potential for stronger subscriber growth and margin expansion from its audiobooks, video podcasts, and artificial intelligence tools. Analyst Sean Diffley, as noted by Seeking Alpha, expects SPOT revenue to grow at a compound annual rate of about 13% over the next five years. He also expects EBITDA to grow about 25%.
An analyst at Jefferies reiterated a “Buy” rating on the stock with a price target of $620. The firm cited improvements in advertising revenue growth and a likely artificial intelligence product launch as a potential catalyst. As quoted by Street Insider, “In our view, investors are looking for Q3 gross margin of ~33.1% (vs. guide 32.9%) with a Q4 guide of 33.7%, which is below the street's 33.9%. We reiterate our Buy rating and raise our PT to $620, which implies 26x our FY27 FCF (vs. 20%+ FCF CAGR).”
The Upcoming AI Product Launch
Over the last few months, Spotify launched a ChatGPT-like music assistant in an effort to help users interact with the app’s catalog of music, podcasts, and audiobooks. The company also created an AI DJ, which allows users to directly engage with it. Reportedly, the AI DJ now has 90 million users and 4 billion hours listened. It launched an AI remix and cover tool in partnership with Universal Music Group. It created prompted playlists that allow Premium users to create playlists from user prompts.
Spotify also just struck a content licensing deal with Believe ahead of the launch of its AI-powered remixing tool. According to Variety.com, the service would give fans a company-controlled platform to create remixes and covers of their favorite artists’ songs, while opening up another way for musicians and music companies to earn money. The idea is to offer an alternative to the unauthorized AI-generated versions spreading across social media. All of which could help SPOT bring in more subscribers, keep them longer, and help bring in more revenue per month.
What Do Analysts Say About SPOT Stock?
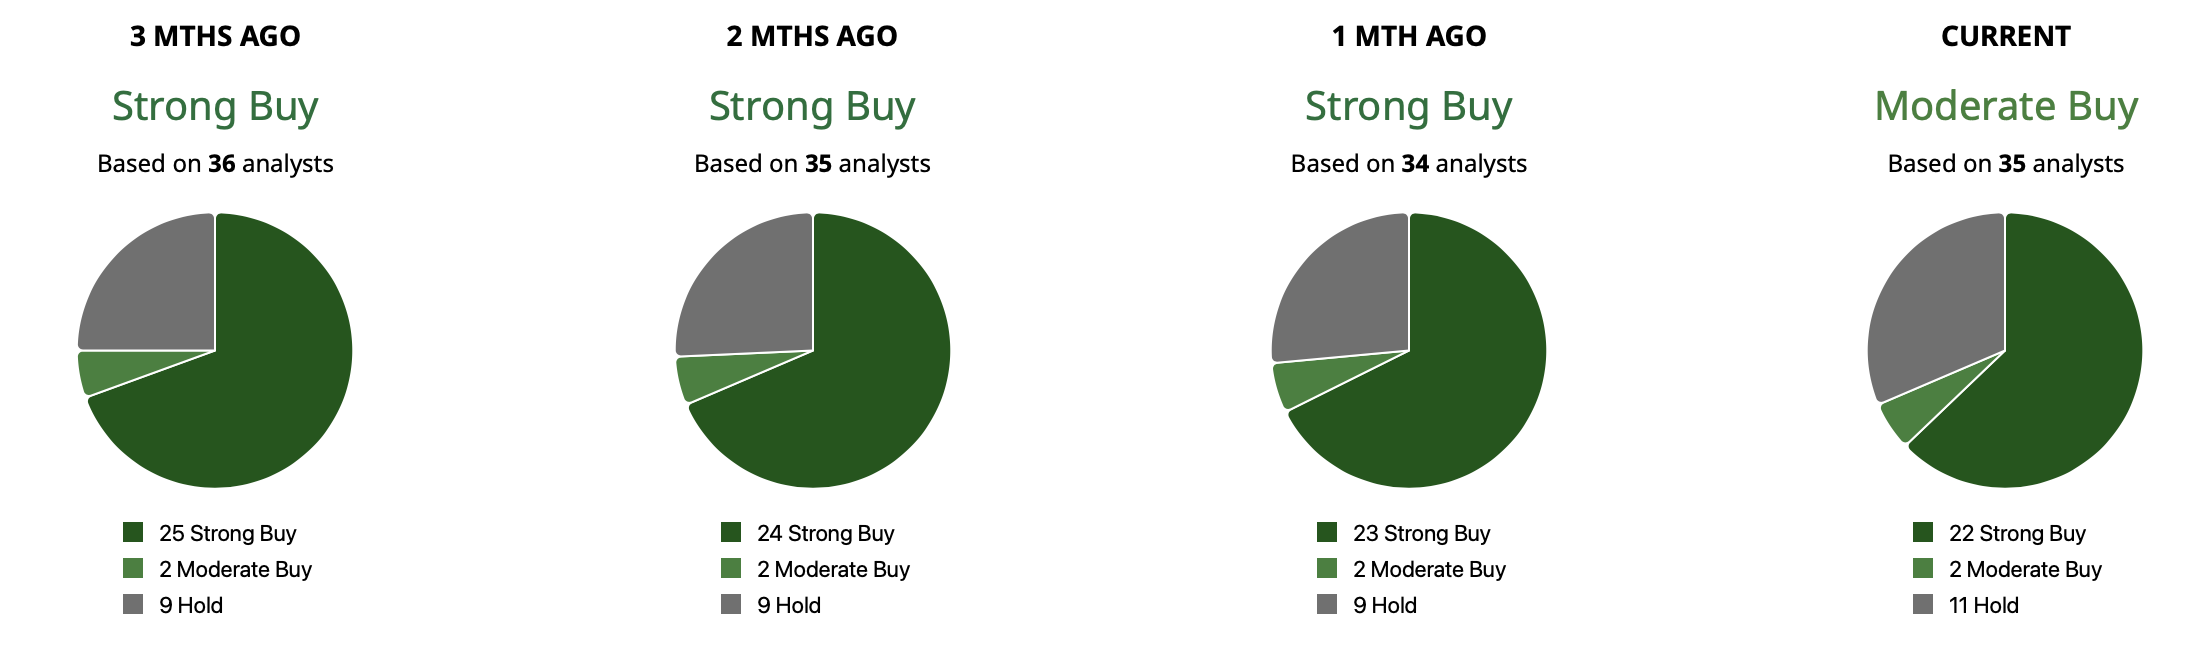
Overall, Spotify has a consensus “Moderate Buy” rating on Wall Street. Of the 35 analysts covering SPOT stock, 22 have a “Strong Buy” rating, two have a “Moderate Buy” rating, and 11 have a “Hold” rating. The mean target price of $601.36 implies potential upside of 15% from current levels. Meanwhile, its high-end price target of $720 implies potential upside of 38% from its current price of $521.88.
Adding subscribers is encouraging, but investors will also want to see healthy margins and an outlook that supports Wall Street’s optimism. Its AI tools could give listeners more reasons to sign up and keep paying. The bigger test is whether those features generate enough additional revenue to justify their costs. Strong subscriber growth and improving profitability could strengthen the bullish case for SPOT.
On the date of publication, Ian Cooper did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.