
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Meta’s (NASDAQ:META) Q3 2026 sales top estimates, quarterly revenue guidance slightly exceeds expectations
Social network operator Meta Platforms (NASDAQ:META) reported Q3 2026 results beating Wall Street’s revenue expectations, with sales up 26.1% year on year to $64.6 billion. Guidance for next quarter’s revenue was better than expected at $74.5 billion at the midpoint, 1.2% above analysts’ estimates. Its GAAP profit of $3.83 per share was 29.9% below analysts’ consensus estimates.
Is now the time to buy Meta? Find out by accessing our full research report, it’s free.
Meta (META) Q3 2026 highlights:
- "In August 2026, we announced an agreement with 52 attorneys general to resolve litigation related to teen mental health and social media, which provides for payments of up to approximately $18.59 billion. Third quarter 2026 costs and expenses includes a $9.89 billion charge related to this agreement."
- Revenue: $64.6 billion vs analyst estimates of $63.35 billion (26.1% year-on-year growth, 2% beat)
- EPS (GAAP): $3.83 vs analyst expectations of $5.46 (29.9% miss, but excluding this, EPS would have been $7.40, a strong beat)
- Revenue Guidance for Q4 2026 is $74.5 billion at the midpoint, above analyst estimates of $73.61 billion
- Operating Margin: 20.1%, down from 40.1% in the same quarter last year
- Free Cash Flow was -$2.12 billion, down from $784 million in the previous quarter
- Daily Active People: 3.64 billion, up 100 million year on year
- Market Capitalization: $1.77 trillion
"We hit major milestones this quarter toward delivering personal superintelligence for everyone - including launching Muse and Muse Wonder, our first frontier model," said Mark Zuckerberg, Meta founder and CEO. "Our investments are paying off, the core business is strong, and we're seeing velocity across the board."
Company overview
Famously founded by Mark Zuckerberg in his Harvard dorm, Meta Platforms (NASDAQ:META) operates a collection of the largest social networks in the world - Facebook, Instagram, WhatsApp, and Messenger, along with its metaverse focused Reality Labs.
Revenue growth
Reviewing a company’s long-term sales performance reveals insights into its quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Luckily, Meta’s sales grew at an excellent 23.9% compounded annual growth rate over the last three years. Its growth surpassed the average consumer internet company and shows its offerings resonate with customers, a great starting point for our analysis.
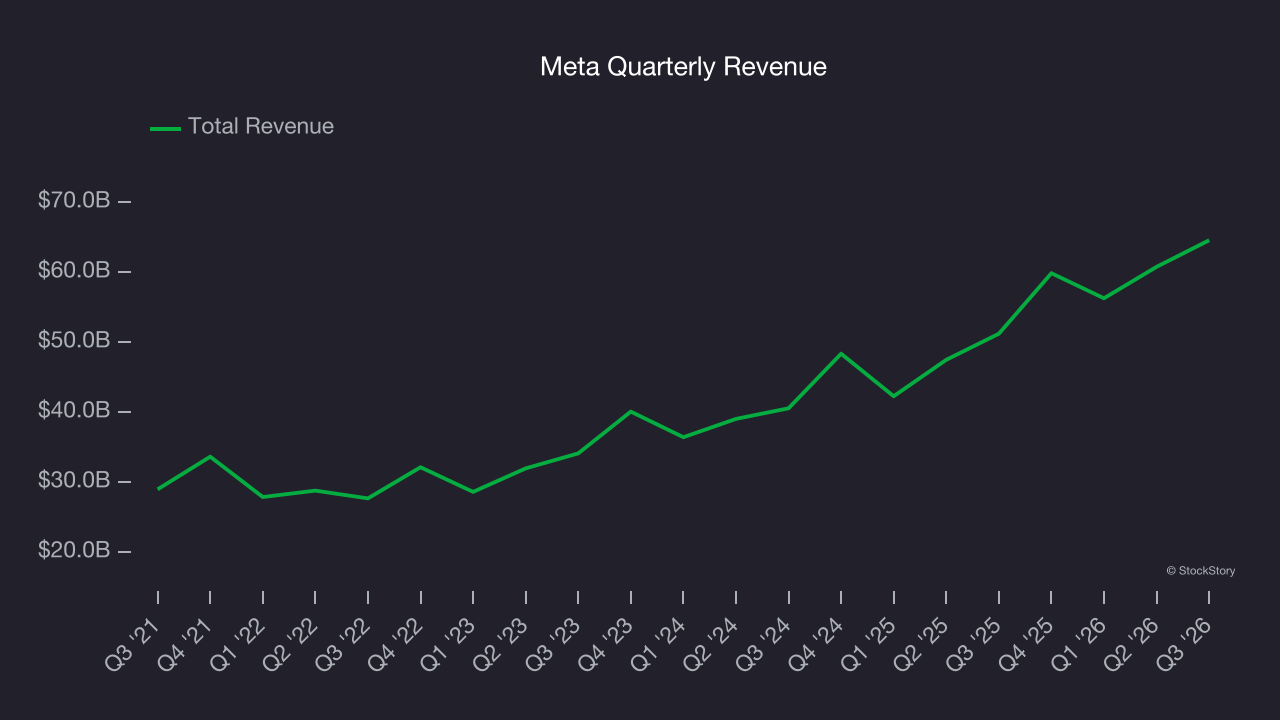
This quarter, Meta reported robust year-on-year revenue growth of 26.1%, and its $64.6 billion of revenue topped Wall Street estimates by 2%. Company management is currently guiding for a 24.4% year-on-year increase in sales next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 20.7% over the next 12 months, a deceleration versus the last three years. We still think its growth trajectory is attractive given its scale and suggests the market is baking in success for its products and services.
WHILE YOU’RE HERE: The Next Palantir? One satellite company captures images of every point on Earth. Every single day. The Pentagon wants it. Hedge funds are using it to beat earnings. You’ve probably never heard of it.
This is what the early days of Palantir looked like before it became a giant. Same playbook. Different technology. If you missed Palantir, you need to see this. Claim The Stock Ticker for Free HERE.
Daily active people
User growth
As a social network, Meta generates revenue growth by increasing its user base and charging advertisers more for the ads each user is shown.
Over the last two years, Meta’s daily active people, a key performance metric for the company, increased by 2.6% annually to 3.64 billion in the latest quarter. This growth rate is one of the lowest in the consumer internet sector, largely a function of its already massive scale and saturated market. If Meta wants to reaccelerate growth, it likely needs to innovate with new products. 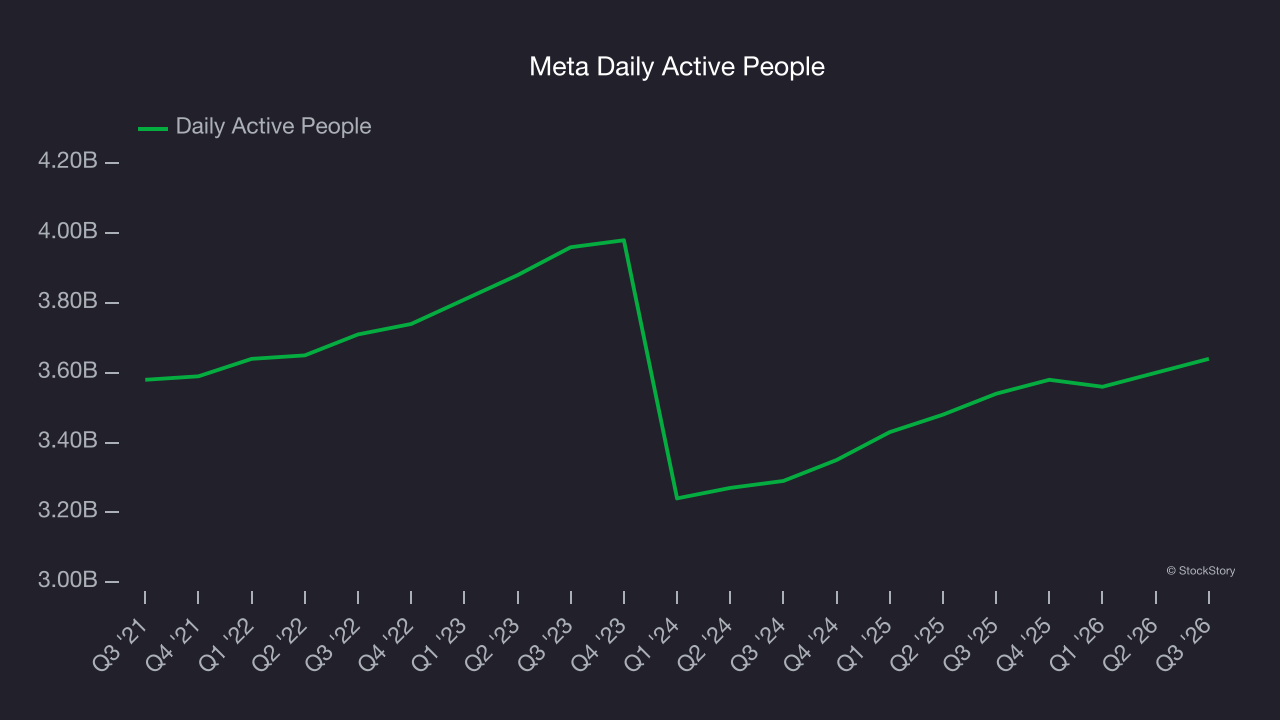
In Q3, Meta added 100 million daily active people, leading to 2.8% year-on-year growth. The quarterly print isn’t too different from its two-year result, suggesting its new initiatives aren’t accelerating user growth just yet.
Revenue per user
Average revenue per user (ARPU) is a critical metric to track because it measures how much the company earns from the ads shown to its users. ARPU can also be a proxy for how valuable advertisers find Meta’s audience and its ad-targeting capabilities.
Meta’s ARPU growth has been exceptional over the last two years, averaging 21.9%. Its ability to increase monetization while growing its daily active people demonstrates its platform’s value, as its users are spending significantly more than last year. 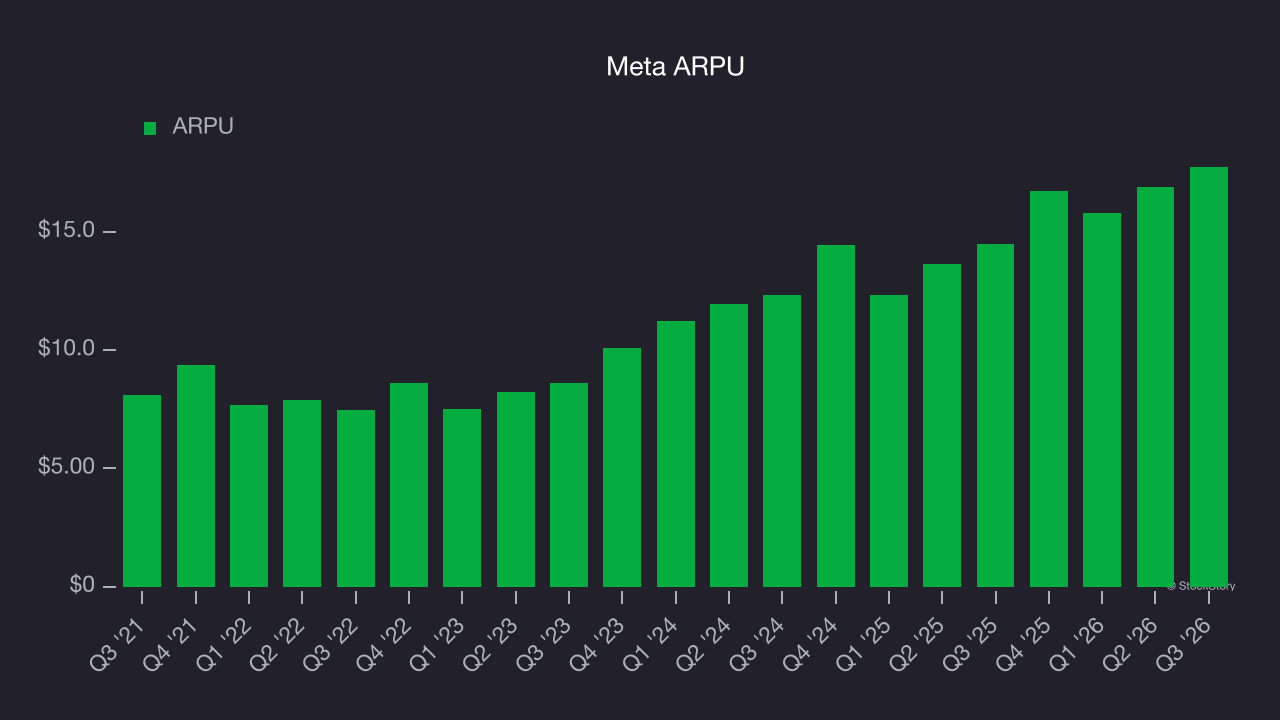
This quarter, Meta’s ARPU clocked in at $17.75. It grew by 22.6% year on year, faster than its daily active people.
Key takeaways from Meta’s Q3 results
It was good to see Meta provide revenue guidance for next quarter that slightly beat analysts’ expectations. We were also happy its revenue outperformed Wall Street’s estimates. Excluding the one-time charge, EPS would have also beat handily. Overall, this print had some key positives. The stock traded up 3.5% to $725.88 immediately after reporting.
So should you invest in Meta right now? The latest quarter does matter, but not nearly as much as longer-term fundamentals and valuation, when deciding if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).